
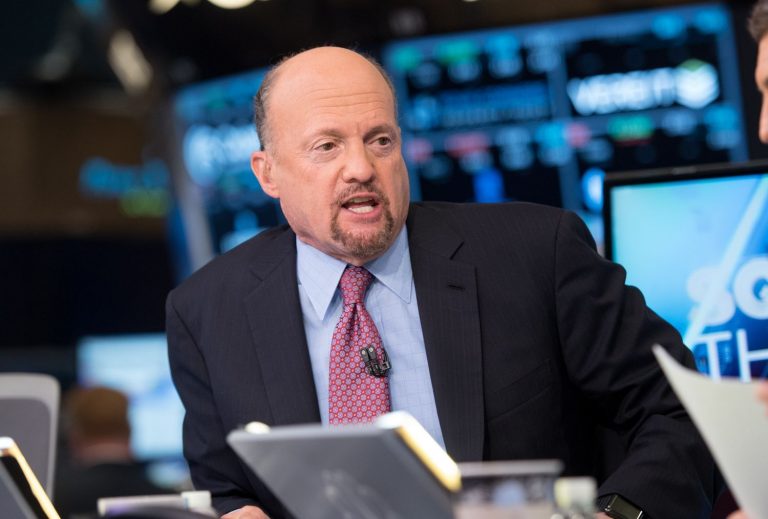
CNBC’s Jim Cramer said he is becoming less skeptical of CoreWeave after the artificial intelligence infrastructure provider delivered stronger-than-expected quarterly results and its chief executive addressed concerns over demand, financing, and the value of its computing equipment.
CoreWeave shares surged nearly 25% on Wednesday after the company reported quarterly revenue above market expectations and raised its 2026 guidance. The results, released on Tuesday evening, helped ease concerns that spending on AI infrastructure could be slowing.
An interview between Cramer and CoreWeave CEO Michael Intrator on CNBC shortly after the opening bell on Wednesday provided further support for the company’s investment case, particularly its claim that demand for computing capacity continues to exceed available supply.
Register for the next Tekedia Mini-MBA.
Register for Tekedia AI in Business Masterclass.
Join Tekedia Capital Syndicate and co-invest in great global startups.
One of the most significant disclosures from Intrator was that customer demand for CoreWeave’s computing capacity is 10 times greater than what the company can currently provide. The figure was also discussed during the company’s post-earnings conference call.
That imbalance gives CoreWeave considerable pricing power. Intrator said the company has been able to raise prices consistently, helping support gross margins even as it commits substantial capital to building additional data center capacity.
For investors concerned about whether the AI infrastructure boom can sustain the level of investment flowing into it, the disclosure offers evidence that demand for specialized computing remains strong. However, the gap between demand and available capacity also highlights the scale of the infrastructure expansion CoreWeave must finance and deliver to convert customer interest into revenue.
CoreWeave’s financing structure has been a major source of investor concern. The company carries substantial debt as it expands its data center footprint, leaving its shares vulnerable to questions about borrowing costs, refinancing, and the returns generated by new infrastructure.
Intrator addressed the issue by explaining that CoreWeave has increasingly relied on financing backed by equipment and customer contracts rather than depending exclusively on conventional bond-market borrowing.
Cramer said he had challenged the CEO over why the company did not buy back its own bonds, which have been trading at depressed prices.
“When I pressed him, asking why he doesn’t just go into the open market and buy these bonds that are trading so poorly, he admitted that he’s been tempted to, but ultimately he still believes he can make an even better return building data centers,” Cramer said.
The explanation reassured Cramer that management continues to see greater potential returns from expanding infrastructure than from using available capital to repurchase discounted debt.
However, the decision also underpins the trade-off facing CoreWeave. Investing in additional data centers could generate higher earnings if demand remains strong, but it requires continued capital expenditure and exposes the company to execution, financing and utilization risks.
Another notable disclosure concerned the resale and contract value of Nvidia’s graphics processing units. Intrator said some H100 chips purchased four years ago are now being contracted at premiums of 20% to 50% above their original purchase cost.
The claim suggests that certain high-performance AI processors are retaining their economic value longer than investors may have expected. This matters because the useful life and residual value of computing equipment influence the economics of data center investment, including depreciation costs and the amount of capital operators must commit to replacing hardware.
If older processors continue generating attractive returns, infrastructure providers could have more flexibility in managing equipment cycles. However, the reported premiums relate to specific H100 chips and contracts and do not establish that all AI hardware will retain its value at the same rate.
Intrator also addressed concerns that growing opposition to data center construction could constrain CoreWeave’s expansion. The CEO maintained that demand for computing power would continue to drive investment, even if tighter regulations forced some projects to move overseas.
The issue has become necessary for the sector as data center development faces scrutiny over electricity consumption, water requirements, land use and pressure on local infrastructure. Restrictions or delays could raise development costs and complicate the delivery schedules of companies seeking to expand computing capacity.
For CoreWeave, the possibility of relocating projects could preserve some growth opportunities, but it would not eliminate the financial and operational challenges associated with building infrastructure across different markets.
The company’s strong results have helped counter recent pessimism surrounding AI infrastructure stocks, although its share-price performance shows how sharply investor sentiment has shifted. CoreWeave shares remain down about 15% year to date and 55% below their 52-week high of $138, reached on May 6.
The past month has also been volatile for other specialized cloud infrastructure providers, including Iren and Nebius. Iren reported strong earnings last week, while Nebius was scheduled to publish its quarterly results on Thursday morning.
Cramer said the latest developments had made him less cautious about CoreWeave, but he stopped short of recommending that investors abandon their concerns about the broader data center trade.
“We’ve taken some data center and related stocks off the table, unfortunately not Nvidia, [for the CNBC Investing Club] because our composure and our prudence dictates that to have too much data center is still too dicey,” he said.
He added that the Club had retained exposure to the AI theme through semiconductor companies, software providers, networking businesses, data center builders, turbine manufacturers and cooling-equipment suppliers.
The CNBC Investing Club does not own any neocloud companies, including CoreWeave. Its remaining exposure is spread across businesses supplying the chips, software, networking systems and power infrastructure needed to support AI development.
Strong demand for computing capacity does not guarantee that every infrastructure provider will earn attractive returns. Companies must still manage debt, secure power, complete construction projects and generate sufficient revenue from expensive equipment.