DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 92

Germany’s Labour Shortage Is Worsening as Skilled Worker Gap Nears 723,000, as Volkswagen Plans 50,000 More Job Cuts

0

Germany’s economic strength has long depended on a highly skilled workforce, from engineers and manufacturers to healthcare professionals, technicians and information-technology specialists. But that foundation is facing growing pressure.

According to a study by the employer-linked German Economic Institute (IW), Germany could face a shortage of around 723,000 skilled workers by 2029, nearly twice the level recorded in 2025.

The projection highlights a structural challenge that could increasingly constrain Europe’s largest economy. The problem is not simply that Germany needs more workers.

It needs workers with the right qualifications for an economy undergoing major technological and demographic transformation.

Industries are increasingly demanding expertise in artificial intelligence, software, engineering, renewable energy, advanced manufacturing and digital infrastructure.

At the same time, traditional sectors such as construction, logistics, healthcare and industrial production continue to require large numbers of trained employees. Demographics make the situation particularly difficult.

Germany has an ageing population, and large numbers of workers from the baby-boomer generation are approaching retirement. As experienced employees leave the labour market, younger generations are not large enough to replace them fully.

This creates a widening gap between the number of people retiring and the number entering employment. The consequences could extend well beyond individual companies.

A shortage of skilled workers can limit production, delay infrastructure projects and increase labour costs as businesses compete for a smaller pool of qualified employees.

Companies may become more reluctant to expand operations if they cannot find the engineers, technicians or specialists needed to run them. In an economy already facing competitive pressure from China, the United States and other industrial powers, that could become a serious disadvantage.

Germany’s manufacturing sector is particularly exposed. The country is attempting to modernize its industrial base while simultaneously transitioning toward cleaner energy and greater digitalization.

Electric vehicles, semiconductor production, robotics, artificial intelligence and renewable-energy infrastructure all require specialized skills. The paradox is clear: Germany needs technological transformation partly because its workforce is changing.

Yet that transformation itself creates demand for skills that are already scarce. Immigration is therefore likely to remain an important part of Germany’s response. Attracting qualified workers from abroad could help compensate for demographic decline.

Particularly in professions where domestic training cannot produce enough workers quickly. However, immigration alone cannot solve the problem.

Language barriers, recognition of foreign qualifications, housing shortages and bureaucratic procedures can make it difficult for international workers to enter and remain in the German labour market.

Education and vocational training will also be critical. Germany has historically benefited from its dual vocational-training system, which combines classroom education with practical workplace experience.

Expanding and modernizing such programs could help prepare younger workers for emerging industries while giving existing employees opportunities to acquire new skills.

Businesses may have to rethink how they recruit and retain talent. Greater investment in automation and artificial intelligence could allow companies to increase productivity even when labour is scarce.

Flexible working arrangements, improved career development and stronger incentives for older workers to remain employed could also help reduce the pressure.

The projected 723,000-worker shortfall by 2029 should therefore be viewed as more than a labour-market statistic. It is a warning about Germany’s economic model.

If the country can combine immigration, vocational education, reskilling, higher productivity and technological investment, the shortage could accelerate modernization.

If it fails, the lack of skilled workers could become a persistent constraint on growth. Germany’s next economic challenge may not be finding enough jobs, but finding enough people capable of doing them.

Volkswagen Plans 50,000 More Job Cuts as Historic Overhaul Reshapes German Auto Industry

Volkswagen is preparing for one of the most consequential transformations in its history, with plans to eliminate as many as 50,000 additional jobs as the German automotive giant attempts to reduce costs, adapt to electric vehicles and confront intensifying global competition.

The scale of the proposed workforce reduction highlights the extraordinary pressure facing a company that has long been one of Europe’s industrial powerhouses.

For decades, Volkswagen’s business model was built around mass production of internal-combustion vehicles, supported by an extensive network of factories, suppliers and employees.

That model generated enormous revenues and helped make Germany a global automotive leader. But the industry is undergoing a structural transformation, and Volkswagen is being forced to rethink almost every part of its operation.

Electric vehicles require different manufacturing processes, fewer mechanical components and new technological capabilities. At the same time, Chinese automakers have become increasingly competitive.

Particularly in electric vehicles, while consumers are demanding more advanced software and connected-car features. Volkswagen therefore faces pressure not only to manufacture vehicles more cheaply but also to innovate faster.

The proposed job cuts are consequently about more than reducing headcount. They represent an attempt to reshape the company for an automotive market that could look dramatically different from the one Volkswagen dominated for generations.

Germany is at the center of this challenge. Volkswagen employs hundreds of thousands of people globally, with a significant portion of its workforce and manufacturing capacity located in Germany.

The country has traditionally provided highly skilled labor, sophisticated engineering and strong industrial infrastructure.German manufacturing is also expensive, particularly when compared with production locations in lower-cost economies.

That creates a difficult dilemma. Closing factories, reducing shifts or eliminating jobs can improve Volkswagen’s cost structure, but such decisions carry enormous social and political consequences.

Volkswagen is deeply embedded in the German economy, and its workforce has historically enjoyed strong representation through labor unions and employee representatives.

The company’s restructuring therefore cannot simply be treated as a conventional corporate cost-cutting exercise. Every major decision has implications for workers, communities and the broader German industrial base.

Yet standing still could be even more dangerous. Automotive companies that fail to adapt to electrification, software and changing consumer preferences risk losing market share permanently. Volkswagen has already invested heavily in electric vehicles and technology.

But competition has intensified faster than many traditional manufacturers anticipated. The planned reductions also illustrate a broader trend across European industry.

Companies are confronting high energy costs, regulatory pressures, weak demand in some markets and fierce competition from Asia.

Germany, in particular, is wrestling with questions about whether its traditional manufacturing model can remain competitive in an increasingly digital and electrified global economy. The challenge is finding the balance between efficiency and innovation.

Cutting thousands of jobs may reduce expenses, but the company must ensure that its restructuring does not weaken the engineering, software and technological capabilities needed for the next generation of vehicles.

The planned 50,000 job cuts therefore represent both a warning and a turning point. Volkswagen is not simply shrinking; it is attempting to redefine what it means to be a major automaker in the electric and software-driven era.

Its success will depend on whether the restructuring produces a leaner company capable of competing globally without sacrificing the technological ambition that will determine the future of mobility.
The Feds Took Their Best Shot at Big Tech — Here’s Why They Missed

0

The Federal government’s campaign against Big Tech was supposed to mark a turning point in the relationship between Washington and Silicon Valley.

For years, regulators and politicians had accused America’s largest technology companies of becoming too powerful, too influential and too difficult to challenge.

Antitrust lawsuits, regulatory investigations and congressional scrutiny all appeared to signal that the era of unchecked technology dominance might finally be coming to an end. Yet the results suggest something very different: the government took its best shot, and Big Tech largely survived.

At the heart of the confrontation was a simple question: have companies such as Google, Apple, Amazon and Meta become so powerful that competition itself is being undermined?

Regulators argued that these firms used their enormous scale, data advantages, distribution networks and control over digital platforms to protect their positions. The government therefore pursued cases designed not merely to impose fines, but potentially to force structural changes.


That threat was significant. Breaking up a major technology company would have been one of the most consequential interventions in American corporate history. Even the possibility of such action created uncertainty for investors, executives and employees.

But litigation moves slowly, while technology markets move at extraordinary speed. This became one of the government’s biggest disadvantages. By the time regulators established their arguments in court, the technology landscape was already changing.

Artificial intelligence emerged as the defining battleground. Cloud computing expanded. Digital advertising evolved. Social-media platforms changed their business models. Consumers continued moving toward services that were increasingly integrated into everyday life.

Big Tech, meanwhile, had something the government could not easily replicate: adaptability. The largest technology companies responded to regulatory pressure by investing billions of dollars in new technologies, expanding into adjacent markets and strengthening their ecosystems.

Artificial intelligence has become particularly important. The AI boom has created a new source of growth for companies that regulators were attempting to constrain, while simultaneously making their infrastructure more strategically important to the broader economy.

This creates a paradox for policymakers. The government may want to reduce the power of dominant technology companies, but it also increasingly depends on their infrastructure, investment and innovation. Data centers, cloud platforms, semiconductor supply chains and AI systems are now intertwined with national economic competitiveness.

That does not mean regulators were wrong to challenge Big Tech. Antitrust enforcement remains important. A company can be innovative while still engaging in behavior that damages competition.

Consumers can benefit from powerful platforms while simultaneously suffering when those platforms become unavoidable gatekeepers. But the outcome demonstrates the difficulty of regulating companies whose markets evolve faster than legislation and litigation.

The biggest lesson may be that simply attacking corporate size is not enough. Regulators need to understand how technology companies create and defend market power in rapidly changing environments.

Traditional remedies designed for industrial-era monopolies may not work effectively against platforms that can reinvent themselves before a legal case reaches its conclusion.

Big Tech therefore emerges from the confrontation bruised but far from defeated. The government demonstrated that it can investigate, sue and impose meaningful pressure. What it has not yet demonstrated is that it can fundamentally reshape the technology industry.

The battle is not necessarily over. AI could create entirely new concentrations of power, giving regulators another opportunity to intervene. But for now, the scoreboard is clear. Washington fired its strongest regulatory weapons.

While Silicon Valley absorbed the impact and continued expanding. The Feds took their best shot. They missed.

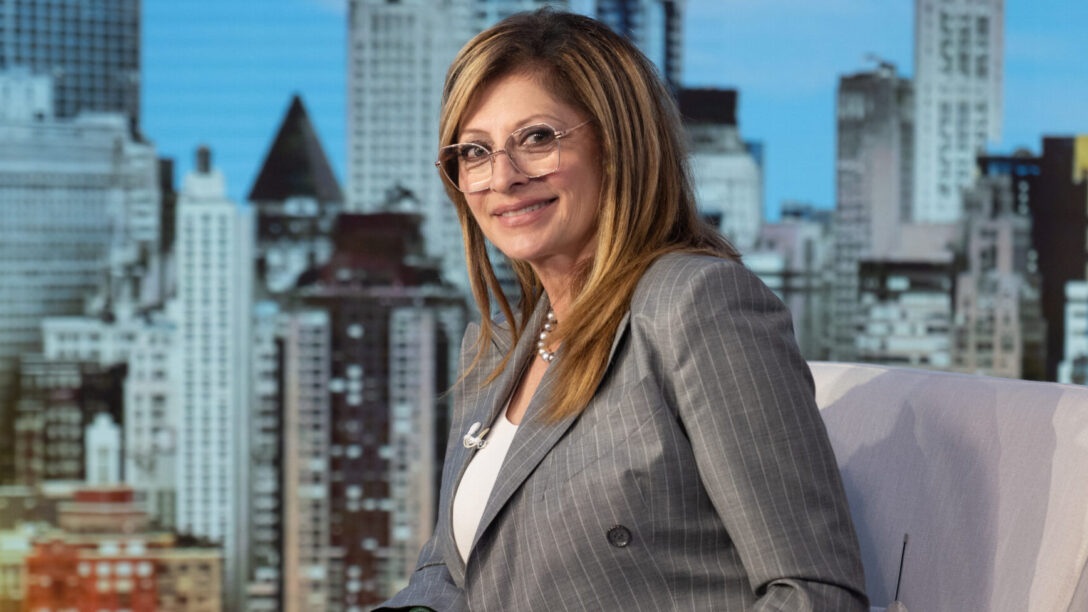
Dude Perfect CEO Exit, Chicken Shop Date Ending and Maria Bartiromo’s Fox Departure

0

The media and creator economy is entering another period of transition, with several high-profile departures and endings highlighting how quickly audiences, companies and entertainment brands are evolving.

From Dude Perfect to Chicken Shop Date and Fox Business anchor Maria Bartiromo, three very different stories point toward the same reality: even successful media institutions are being forced to reconsider what comes next.

At Dude Perfect, the departure of the company’s first chief executive represents a significant moment for one of YouTube’s most successful creator-led businesses.

The executive is reportedly leaving after disagreements with the board over the company’s next phase. That detail is important because Dude Perfect has grown far beyond the traditional YouTube channel model.

What began as a group of friends producing sports-trick videos developed into a major entertainment business built around sponsorships, merchandise, live events, television and digital media.

As creator companies mature, the priorities of founders, executives and investors can diverge. A business that once focused primarily on audience growth may eventually need to emphasize profitability, intellectual property, international expansion or new forms of entertainment.

Leadership changes can therefore reflect deeper strategic questions about how a creator brand should evolve without losing the authenticity that made it successful.

Meanwhile, the ending of Chicken Shop Date marks another emotional moment for digital entertainment. The YouTube series, known for its unusual combination of celebrity interviews, awkward humor and informal settings, became one of the platform’s most recognizable shows after more than a decade.

Its success demonstrated that YouTube could support distinctive formats that did not resemble traditional television. The show’s longevity is particularly notable in an industry obsessed with constant novelty.

Chicken Shop Date built a recognizable identity and loyal audience by remaining deliberately unconventional. Its ending therefore illustrates that even iconic digital formats eventually reach a natural conclusion.

For creators, the challenge is not simply producing something popular but knowing when a successful format has reached the end of its creative cycle. Then there is Maria Bartiromo, whose departure from Fox after more than 12 years represents a major change in the television news landscape.

Bartiromo became one of the most recognizable financial-news personalities on American television, building a reputation around markets, business and political coverage. Her exit closes another long chapter in the increasingly fluid world of broadcast media.

These developments reveal an industry experiencing a generational shift. Creator-led companies are becoming more corporate, established shows are reaching their natural endpoints, and veteran television personalities are leaving institutions where they built long careers.

The underlying lesson is that media success no longer guarantees permanence. Audiences move, platforms change, business models evolve and leadership strategies are constantly reassessed.

YouTube creators increasingly operate like traditional media companies, while traditional broadcasters face competition from personalities and formats born online.

Dude Perfect, Chicken Shop Date and Bartiromo occupy very different corners of the media ecosystem, but their stories converge around one idea: the next phase of media will be defined not only by who can build an audience, but by who can successfully reinvent what that audience expects.

African Startup Funding Rebounds to $455 Million in August, Driven by Mega-Deals

0

African startup funding staged a powerful rebound in August 2026, as a handful of mega-deals pushed the continent’s monthly funding total to its second-highest level in the past year.

The handful of large transactions was led by Moove’s $250 million Series C, driving the month’s impressive headline figure.

The round was led by Tiger Global, with participation from existing investors including Uber, Mubadala, BlackRock, and Prosus Ventures. The capital will be used to expand Moove’s autonomous vehicle business, strengthen its AI capabilities and grow its operations across more global markets.

According to report by Africa;The Big Deal, 31 African startups announced funding rounds of at least $100,000 in August, collectively raising $455 million, excluding exits.

The figure marked a significant rebound from the $102 million recorded in July and stood at more than twice the previous 12-month monthly average of $220 million.

August also recorded the second-highest monthly funding total of the past year, behind June 2026. However, the strong headline number masked a weaker level of overall fundraising activity. With only 31 startups securing $100,000 or more, August remained well below the previous 12-month average of 43 funded ventures per month.

The month’s funding was also highly concentrated among a small number of companies. The five largest transactions accounted for 84% of the total capital raised. Moove alone raised $250 million, representing approximately 55% of August’s entire funding haul.

Other major transactions included Jumia’s $50 million equity raise, Yellow Card’s $40 million round, Moment’s $22 million raise, and ValU’s $21 million corporate bond issuance.

The concentration became even more pronounced geographically. The so-called Big Four—Nigeria, Egypt, South Africa and Kenya accounted for 99.5% of the total capital raised and 94% of all $100,000+ deals, with 29 of the 31 funded startups based in those markets.

Nigeria was the dominant beneficiary, attracting approximately $364 million, or 80% of all funding raised across Africa during the month. Moove’s $250 million round was the biggest contributor to the country’s outsized share.

August also saw two notable startup exits. Tamweely was acquired by Egypt’s eFinance Group in a disclosed transaction valued at $95 million, while Kenya-based Chpter was acquired by Cloud9 for an undisclosed amount. The transactions brought the number of African startup exits recorded in 2026 to 30 year-to-date.

Despite August’s strong performance, the broader funding picture remains mixed. Between January and August 2026, African startups raised approximately $1.92 billion, putting the continent only 9% below the $2.1 billion raised during the same period in 2025.

Equity funding has performed particularly well. At $1.35 billion, equity investment is up 23% year-on-year, although that growth has been heavily influenced by a small number of mega-rounds, particularly those secured by Spiro and Moove.

The weakness becomes clearer when looking beyond total capital raised. Only 269 unique African ventures had secured at least $100,000 by the end of August, compared with 332 at the same point in 2025, representing a 19% decline.

Investor participation has also contracted. The number of named active investors fell from 368 in 2025 to 288 in 2026, a 22% year-on-year decline.

The August figures therefore point to a funding market that is recovering in value but not necessarily in breadth. Large, well-funded companies are attracting increasingly significant amounts of capital, while smaller startups continue to face a more challenging fundraising environment.

In effect, August strengthened Africa’s overall 2026 funding numbers, but it did little to reverse the underlying concentration of capital among a relatively small group of companies, countries and investors.

China’s Auto Exports Surge 77.5% Even as Domestic Sales Fall for 11th Straight Month

0

Chinese automakers are accelerating their overseas expansion as weak domestic demand pushes exports to a record pace, with BYD and Geely among the manufacturers posting fresh export highs.

China’s passenger-vehicle exports remained exceptionally strong in August, highlighting the growing importance of overseas markets for the country’s automakers as sales at home declined for an 11th consecutive month.

Passenger-vehicle exports jumped 77.5% from a year earlier to 894,000 units in August, according to data released Tuesday by the China Passenger Car Association (CPCA). The increase was slightly slower than the 88.2% year-on-year surge recorded in July but still represented a substantial expansion in overseas shipments.

The contrast with the domestic market was stark. Passenger-vehicle sales in China fell 23.7% from a year earlier to 1.55 million units in August, accelerating from a 21.1% decline in July.

Electric vehicles and plug-in hybrids accounted for 64.7% of domestic passenger-vehicle sales, but sales of those vehicles declined 10.1% year on year in August, compared with a 3.9% drop in July. By contrast, exports of new-energy vehicles surged 154.7%, accelerating from 147.8% growth a month earlier.

The widening gap between domestic and overseas performance is pushing Chinese automakers to intensify their international expansion. BYD and Geely Auto both reported record export volumes in August as manufacturers increasingly look abroad to offset fierce competition and weakening demand in China.

Chinese automakers have continued to gain ground in overseas markets despite rising trade barriers and regulatory scrutiny. Their combination of competitive pricing, sophisticated technology and expanding EV lineups has helped them attract customers in Europe and emerging markets.

The export push is also becoming a structural growth strategy rather than simply a response to weak domestic demand. CPCA Secretary-General Cui Dongshu expects China’s vehicle exports to reach 12 million units this year, with annual shipments potentially rising to between 18 million and 20 million vehicles by 2030.

Automakers that entered the international market later are increasingly under pressure to catch up. Xiaomi, which entered the EV market relatively recently, has signed agreements with German auto dealers ahead of its planned European launch next year as it seeks to establish an overseas distribution network.

Seres, which co-develops Aito vehicles with Huawei, illustrates the risks of falling behind in the export race. The company is facing intensifying competition in China’s crowded premium EV market, while its comparatively late overseas expansion has limited its ability to tap foreign demand. Its total vehicle sales plunged 44% last month.

The rapid growth in exports, however, is raising concerns that the intense price competition that has battered Chinese automakers, suppliers and dealers at home could spill into foreign markets. Chinese regulators last week issued new guidelines governing automakers’ overseas operations, warning manufacturers against frequent or steep price cuts and other practices that violate regulations, potentially harm consumers or damage Chinese brands’ reputations.

Major manufacturers including BYD, Chery and Geely Holding have pledged to comply with the new guidelines. Regulators have not yet specified penalties for violations.

The regulatory intervention comes as China’s auto industry undergoes a prolonged shakeout. Manufacturers are competing for market share in a saturated domestic market, while excess capacity and aggressive pricing have put pressure on profitability across the supply chain.

For the industry’s strongest exporters, overseas markets offer an important outlet for that capacity and a way to diversify revenue. But the faster Chinese automakers expand abroad, the greater the likelihood of additional trade restrictions and scrutiny from governments concerned about pricing, industrial competition and the impact of Chinese imports on domestic manufacturers.

That leaves China’s auto industry increasingly dependent on a delicate balance: finding new overseas customers quickly enough to compensate for weakness at home while avoiding the regulatory and trade backlash that could constrain its global expansion.