DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog

When the Cameras Go Dark, the Press Fight Gets Bigger

0

The confrontation between President Donald Trump and major American television networks has entered an unusual phase: the cameras that routinely follow the president have stopped rolling for many of his official events.

ABC, CBS, CNN, Fox News and NBC, which collectively operate the White House television pool, suspended pool coverage after the administration barred CNN, MS NOW and Politico from White House access.

The dispute is not simply about whether a particular network gets into a briefing room. It concerns the infrastructure through which millions of Americans receive images and sound from the presidency.

Under the traditional pool arrangement, the five major television networks rotate responsibility for filming presidential events and distribute the resulting footage to other media organizations. When one network is excluded from its scheduled assignment, the system becomes difficult to operate normally.

That is precisely what happened on Monday. CNN had been scheduled to provide pool coverage but was prevented from doing so following the White House ban. Rather than replacing CNN with another broadcaster, the other pool members suspended presidential pool coverage.

Fox News Washington bureau chief Bryan Boughton, who was serving as pool chair, told members that there would be no replacement pool under the existing circumstances. The immediate consequences were visible.

During an event at the White House unveiling a new helipad, Trump’s remarks were difficult for television viewers to hear because the normal pool audio was absent. Instead of the familiar combination of multiple cameras and professional sound, the White House’s own footage provided an incomplete substitute.

The dispute has also moved into the courts. CNN, MS NOW and Politico filed a federal lawsuit challenging their exclusion, alleging violations of First Amendment press protections and Fifth Amendment due-process rights.

The administration has defended its restrictions and Trump has accused the affected outlets of producing false or unfavorable coverage. Those competing claims are now part of a legal dispute rather than merely a disagreement between politicians and journalists.

For the public, the significance extends beyond television ratings or newsroom rivalries. Presidential events are part of the historical record. Pool cameras allow journalists across the country and internationally to see what the president says and does, often in real time.

When that shared infrastructure disappears, government communication can become increasingly dependent on footage produced directly by the government itself. The conflict has already reached Trump’s international schedule.

The television pool decided not to provide its customary coverage of his trip to the United Nations General Assembly, meaning an event normally guaranteed extensive broadcast documentation faced an unusual television blackout.

The White House has alternative ways to communicate. Government websites and social-media channels can distribute presidential remarks without relying on traditional broadcasters. Trump has also launched a 24-hour online video operation, giving the administration another direct channel to its audience.

That creates a new media environment in which presidents can increasingly bypass conventional television gatekeepers. But the reverse is also true: independent broadcasters provide context, questioning and verification that government-produced footage does not necessarily provide.

The central issue, therefore, is not whether television networks should always agree with the White House or whether the White House should never challenge media organizations. It is whether access to presidential information can remain open enough for competing journalists to independently document the exercise of executive power.

For now, the cameras have gone dark. The larger question is what kind of press-government relationship emerges when they come back on.
CME Group to Launch Bitcoin Cash and Uniswap Futures as Binance Invests $100M in Circle

0

The institutionalization of crypto markets is entering another phase as traditional derivatives infrastructure and stablecoin networks continue to expand. Two developments illustrate the direction clearly: CME Group is preparing to launch Bitcoin Cash and Uniswap futures.

While Binance is investing $100 million in Circle and extending its USDC partnership for another five years across emerging markets. The moves show how cryptocurrencies are increasingly being connected to conventional financial markets and global payment infrastructure.

CME Group’s planned launch of Bitcoin Cash and Uniswap futures on October 19 adds two more digital assets to one of the world’s most important regulated derivatives venues.

Futures contracts allow traders to gain or hedge exposure to an asset without directly holding the underlying cryptocurrency. For institutional investors, this can make participation easier because futures can be integrated into existing risk-management, trading and portfolio systems.

Bitcoin Cash, created as a fork of Bitcoin, has maintained a distinct market following, while Uniswap represents a different part of the crypto economy. UNI is closely associated with Uniswap, one of the largest decentralized-exchange protocols.

Bringing futures tied to both assets onto CME therefore expands the range of crypto exposures available through regulated derivatives markets. The significance extends beyond the individual tokens.

CME’s expansion suggests that demand for crypto derivatives remains broad enough for market infrastructure providers to continue adding products. Futures can also contribute to price discovery by bringing together participants with different expectations about future prices.

At the same time, derivatives introduce leverage, meaning traders can amplify both gains and losses. The growth of these markets therefore does not eliminate crypto volatility; it creates more sophisticated instruments for managing and expressing it.

Meanwhile, Binance’s $100 million investment in Circle connects exchange infrastructure with the rapidly developing stablecoin economy. Circle is the issuer of USDC, a dollar-denominated stablecoin designed to maintain a value close to one U.S. dollar.

Binance’s investment, alongside the extension of their USDC partnership for five years, places stablecoins at the center of a broader strategy focused on emerging markets. The emerging-market dimension is particularly important.

Traditional international payments can involve multiple intermediaries, banking restrictions, currency conversion costs and delays. Dollar-linked stablecoins offer another mechanism for moving digital representations of dollars across blockchain networks.

For businesses and individuals operating in countries with weaker local currencies or limited access to global financial infrastructure, this can create new options for dollar exposure and cross-border settlement.

For Binance, deeper cooperation with Circle can strengthen USDC liquidity and availability across its ecosystem. For Circle, a long-term relationship with one of the world’s largest cryptocurrency exchanges can expand distribution and potential usage.

Yet adoption will still depend on regulation, liquidity, local banking relationships and user trust. The two developments reveal two complementary sides of crypto’s maturation.

CME is building bridges between digital assets and institutional derivatives markets, while Binance and Circle are expanding the infrastructure around digital dollars. One focuses on trading and risk management; the other focuses on settlement, liquidity and payments.

The larger story is that crypto infrastructure is becoming increasingly segmented and specialized. Bitcoin Cash and UNI futures give professional traders additional regulated tools, while USDC partnerships seek to make blockchain-based dollars more accessible.

As these systems develop, the key question will increasingly shift from whether crypto can enter mainstream finance to how deeply its infrastructure can integrate with global markets.

“These Predictions Discourage Young People” – Nvidia CEO Jensen Huang Critiques AI Catastrophe Forecasts

0

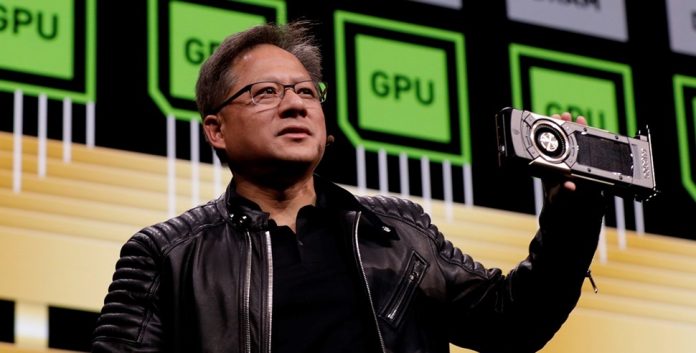
Nvidia CEO Jensen Huang has sharply criticized scientists who issue alarming forecasts about artificial intelligence causing societal collapse, arguing that such predictions lack scientific grounding and actively harm the field.

In a recent appearance on The Ezra Klein Show, Huang pushed back against what he described as “AI doomer” narratives, insisting they are not based on rigorous research and discourage young people from entering the industry.

He specifically addressed estimates from AI pioneer Geoffrey Hinton, who suggested a 10-20% chance that advanced AI systems could lead to societal collapse.

Huang rejected the figure, stating there is no scientific research supporting such precise probabilities. He argued that simply coming from a prominent scientist does not make a prediction scientific.

He said,

“I would tell Geoff that it’s irresponsible to say all that. All of his predictions have been wrong. Enough predictions. That 10 percent chance is not grounded in science. It’s not grounded in research. Just because it comes from a scientist doesn’t make it scientific. Those predictions are hurtful.”

“Is it good or bad that we scare young people about the future of A.I., so much so that they don’t even want to go to universities and don’t want to go to college anymore because they don’t think they’ll get a job? Is that helpful or hurtful, if it were to happen? It’s hurtful.

“Don’t think for a second just because you’re an alarmist that you’re doing a social good. It is not true. So I think that we ought to just all be wiser, more mature, be evidence-based, be scientific. If you want to be scientific, be scientific. Do the science.”

According to Huang, these forecasts have a poor track record and create unnecessary fear that steers talented students away from AI-related careers at a time when the technology needs more, not fewer, skilled contributors.

The Nvidia chief framed AI safety primarily as an engineering challenge rather than an existential philosophical crisis. He maintained that the industry should focus on practical, evidence-based approaches to building reliable systems instead of amplifying speculative worst-case scenarios.

Huang’s remarks come amid an ongoing and often polarized debate within the AI community. Figures such as Hinton, along with researchers associated with organizations focused on existential risk, have repeatedly warned that rapid progress in AI capabilities could outpace society’s ability to control or align the systems.

In defense, Huang’s comments reflect his longstanding position as one of the most prominent AI optimists in technology. As the leader of the company that supplies the majority of the specialized chips powering modern large language models and generative AI systems, he has consistently emphasized the transformative benefits of the technology while downplaying catastrophic risk narratives.

In contrast, Huang and other industry leaders argue that exaggerated doomerism risks slowing innovation, reducing investment, and creating regulatory overreactions that could cede technological leadership to less cautious actors.

Huang made clear which side he occupies. He expressed concern that constant emphasis on collapse scenarios could deter the next generation of engineers and researchers precisely when their contributions are most needed to improve safety, reliability, and usefulness.

Nvidia’s central role in the AI boom gives Huang’s words significant weight. The company’s GPUs remain the dominant hardware platform for training and running the largest AI models.

Any shift in public or regulatory sentiment driven by doomer narratives could affect demand for those chips, research priorities, and talent pipelines. Huang appears determined to counter the more alarmist messaging by stressing evidence, practical progress, and the tangible benefits already emerging from AI systems in science, industry, and everyday applications.

Outlook

The debate over AI’s long-term risks is likely to remain contentious as models become more capable and increasingly integrated into the economy.

Huang’s comments could reinforce the view among technology companies and investors that AI development should remain focused on measurable safety improvements, engineering controls, and practical applications rather than speculative probabilities of societal collapse. At the same time, warnings from researchers such as Hinton are unlikely to disappear.

As AI systems become more autonomous and capable of performing increasingly complex tasks, questions around alignment, misuse, labor-market disruption, and the ability of institutions to govern advanced systems are expected to remain central to the conversation.

Bitcoin ETFs See $715M Inflows as Jack Butcher’s Credits NFTs Top 100K Sales

0

Bitcoin’s institutional market is showing renewed strength as spot Bitcoin exchange-traded funds record a fourth consecutive day of net inflows, with roughly $715 million entering the products.

The NFT market is experimenting with a more financialized structure, as digital artist Jack Butcher sells more than 100,000 Credits NFTs through an X-based money mint while Tokenworks launches CREDITSTR, a vehicle designed to buy and relist Credits NFTs.

The developments illustrate two different sides of the crypto economy: one increasingly connected to traditional financial markets and another attempting to turn digital collectibles into tradable financial assets.

The Bitcoin ETF inflows are particularly important because sustained flows provide a clearer picture of institutional demand than a single strong trading session. Spot ETFs give investors exposure to Bitcoin through regulated market infrastructure without requiring them to manage wallets or private keys directly.

Four consecutive days of inflows therefore suggest that capital is continuing to find its way into Bitcoin through conventional investment channels. The $715 million figure also arrives at a time when Bitcoin’s market narrative remains closely tied to liquidity, interest rates and institutional positioning.

ETF flows can influence market sentiment because large creations require underlying Bitcoin exposure to be maintained by fund issuers. However, inflows should not automatically be interpreted as a guarantee of continued price appreciation.

Investors can change allocations quickly when macroeconomic conditions, risk appetite or portfolio strategies shift. The NFT developments represent a different experiment. Jack Butcher’s Credits ecosystem has long attempted to connect digital art, collectibles and financialized ownership.

Selling more than 100,000 Credits NFTs through an X money mint demonstrates the continuing ability of established digital artists to generate substantial demand when distribution, community and scarcity intersect.

The more intriguing development is Tokenworks’ CREDITSTR. Rather than simply creating another collection, the project introduces a mechanism intended to acquire Credits NFTs and relist them.

That structure pushes NFTs toward a model that resembles inventory management or an asset marketplace, where value can potentially be created through repeated acquisition, pricing and resale.

This approach raises an important question for the broader NFT industry: can digital collectibles evolve from primarily cultural objects into financial instruments with deeper liquidity? The answer remains uncertain.

Traditional financial markets rely on continuous price discovery, transparent information and large pools of buyers and sellers. NFTs often have much thinner liquidity, meaning that an apparent market price can change dramatically when only a small number of participants are willing to transact.

Buying and relisting assets can create additional market activity, but activity alone does not guarantee sustainable demand. CREDITSTR therefore represents an experiment in NFT market structure rather than proof that NFTs have become mature financial assets.

Its success will depend on whether genuine buyers emerge beyond speculative traders and whether the underlying Credits ecosystem maintains cultural relevance. The contrast with Bitcoin ETFs is revealing. Bitcoin is increasingly being absorbed into established financial infrastructure.

While NFTs are still searching for mechanisms that can create comparable liquidity and accessibility. Both developments nevertheless point toward the same broader trend: crypto markets are becoming increasingly financialized.

Bitcoin is moving deeper into portfolios through ETFs, while NFT entrepreneurs are experimenting with structures that treat digital collectibles as assets capable of being accumulated, priced and traded.

The next phase of crypto may therefore be less about creating entirely new asset classes and more about building financial infrastructure around the digital assets that already exist.

Airtel Money Plans London IPO as Africa’s $213bn Mobile Payments Business Targets Next Growth Phase

0

Airtel Money is preparing to list on the London Stock Exchange, setting the stage for one of the most significant public-market debuts by an African digital financial services business as it seeks to expand beyond its existing customer base and deepen its position in the continent’s fast-growing mobile payments market.

The company, which operates across 13 African markets, said it plans to publish a prospectus in early October, with the final offer price expected in mid-October after an institutional book-building process. The proposed offering will involve only existing shares, meaning Airtel Money itself will not receive proceeds from the sale.

The company expects at least 10% of its shares to be in public hands following the listing. The International Finance Corporation has agreed to invest up to £67.2 million, or about $90 million, as a cornerstone investor, subject to the final offer price and other conditions.

The decision to sell existing shares rather than raise fresh capital is significant. Airtel Money says it is debt-free, capital-light and highly cash-generative, allowing it to pursue a public listing without relying on the IPO to finance its expansion.

“Today marks the start of a new chapter for Airtel Money as we announce our plans to list on the London Stock Exchange,” CEO Ian Ferrao said.

He said the business had reached approximately 53 million monthly active users and was entering the market with the financial capacity to fund its next stage of expansion.

The numbers underpinning the IPO are substantial. Airtel Money processed $213 billion in total payment value in the 12 months to June 30, 2026, while revenue reached $1.346 billion in the financial year ended March 2026. EBITDA stood at $676 million, giving the business an EBITDA margin of roughly 50%.

The company also reported a pre-tax cash conversion ratio above 90% in each of the past three financial years. Capital expenditure accounted for only 3% of revenue in the year ended March 2026, while Airtel Money said it had no external borrowings.

That combination of high margins, low capital requirements and strong cash generation is likely to be central to the investment case as Airtel Money approaches international investors. It also distinguishes the business from many younger fintech companies that continue to rely heavily on external funding to finance growth.

Airtel Network Provides A Large Expansion Opportunity

Airtel Money’s existing scale is only part of the growth story. The company said its 53 million monthly active users represented about 41% of Airtel Africa’s 128.9 million telecommunications subscribers. That leaves more than 75 million Airtel subscribers who are not currently using Airtel Money, creating a large potential customer pool without requiring the business to build an entirely new distribution network.

The relationship with Airtel Africa is particularly important because the telecom company remains Airtel Money’s founding shareholder and distribution partner. The mobile operator provides access to an established customer base, retail presence, and agent network across its markets.

Customer numbers have grown at a compound annual rate of 20% from March 2018 through June 2026. Total payment value has grown even faster, with dollar-denominated TPV increasing at a 33% compound annual rate over the same period.

The growth also shows how mobile money has evolved beyond basic person-to-person transfers in many African markets. Airtel Money has expanded into a broader digital financial services platform, allowing customers to make payments and conduct other financial transactions through mobile devices in markets where traditional banking infrastructure remains uneven.

For investors, the opportunity extends beyond the current 53 million users. Airtel Money is effectively seeking to monetize an existing telecommunications ecosystem while increasing the frequency and value of transactions among its customers.

The proposed London listing also gives the business access to an international investor base at a time when global investors have increasingly focused on African financial technology and digital payments. The IFC’s participation as a cornerstone investor provides an additional institutional endorsement of the offering, although the eventual valuation will depend on the price range and market conditions disclosed in the prospectus.

The IPO has been in preparation for several years. Airtel Africa had been exploring a listing of its mobile money operation since at least 2025, when Citi was reported to have been selected as lead adviser. Airtel Africa subsequently identified London as its preferred listing venue in July 2026.

The business has expanded rapidly during that period. Airtel Africa reported that Airtel Money generated $1.08 billion in revenue in the financial year ended March 2026, compared with $770 million a year earlier.

The proposed transaction nevertheless comes with an important limitation for investors: Airtel Money will not receive new capital from the IPO. The offering is therefore primarily a shareholder liquidity event and a mechanism for establishing a public market valuation rather than a direct funding exercise for expansion.

That could make the company’s ability to sustain its existing growth rate crucial after listing. With the business already generating substantial cash and carrying no external debt, management will need to demonstrate that further expansion can continue through its existing operating model while converting the large pool of Airtel Africa subscribers who have yet to adopt its financial services.

The prospectus will provide the market with the missing pieces, including the indicative price range, offer size and detailed financial and risk disclosures. Those details will determine how investors value a business whose growth profile is closely tied to Africa’s continuing shift toward digital payments.

However, Airtel Money is positioning the London IPO around a combination of scale, profitability and further room for penetration. Its 53 million users and $213 billion in annual payment value already give it substantial weight in African digital finance, while the much larger Airtel subscriber base provides a built-in avenue for expansion.