
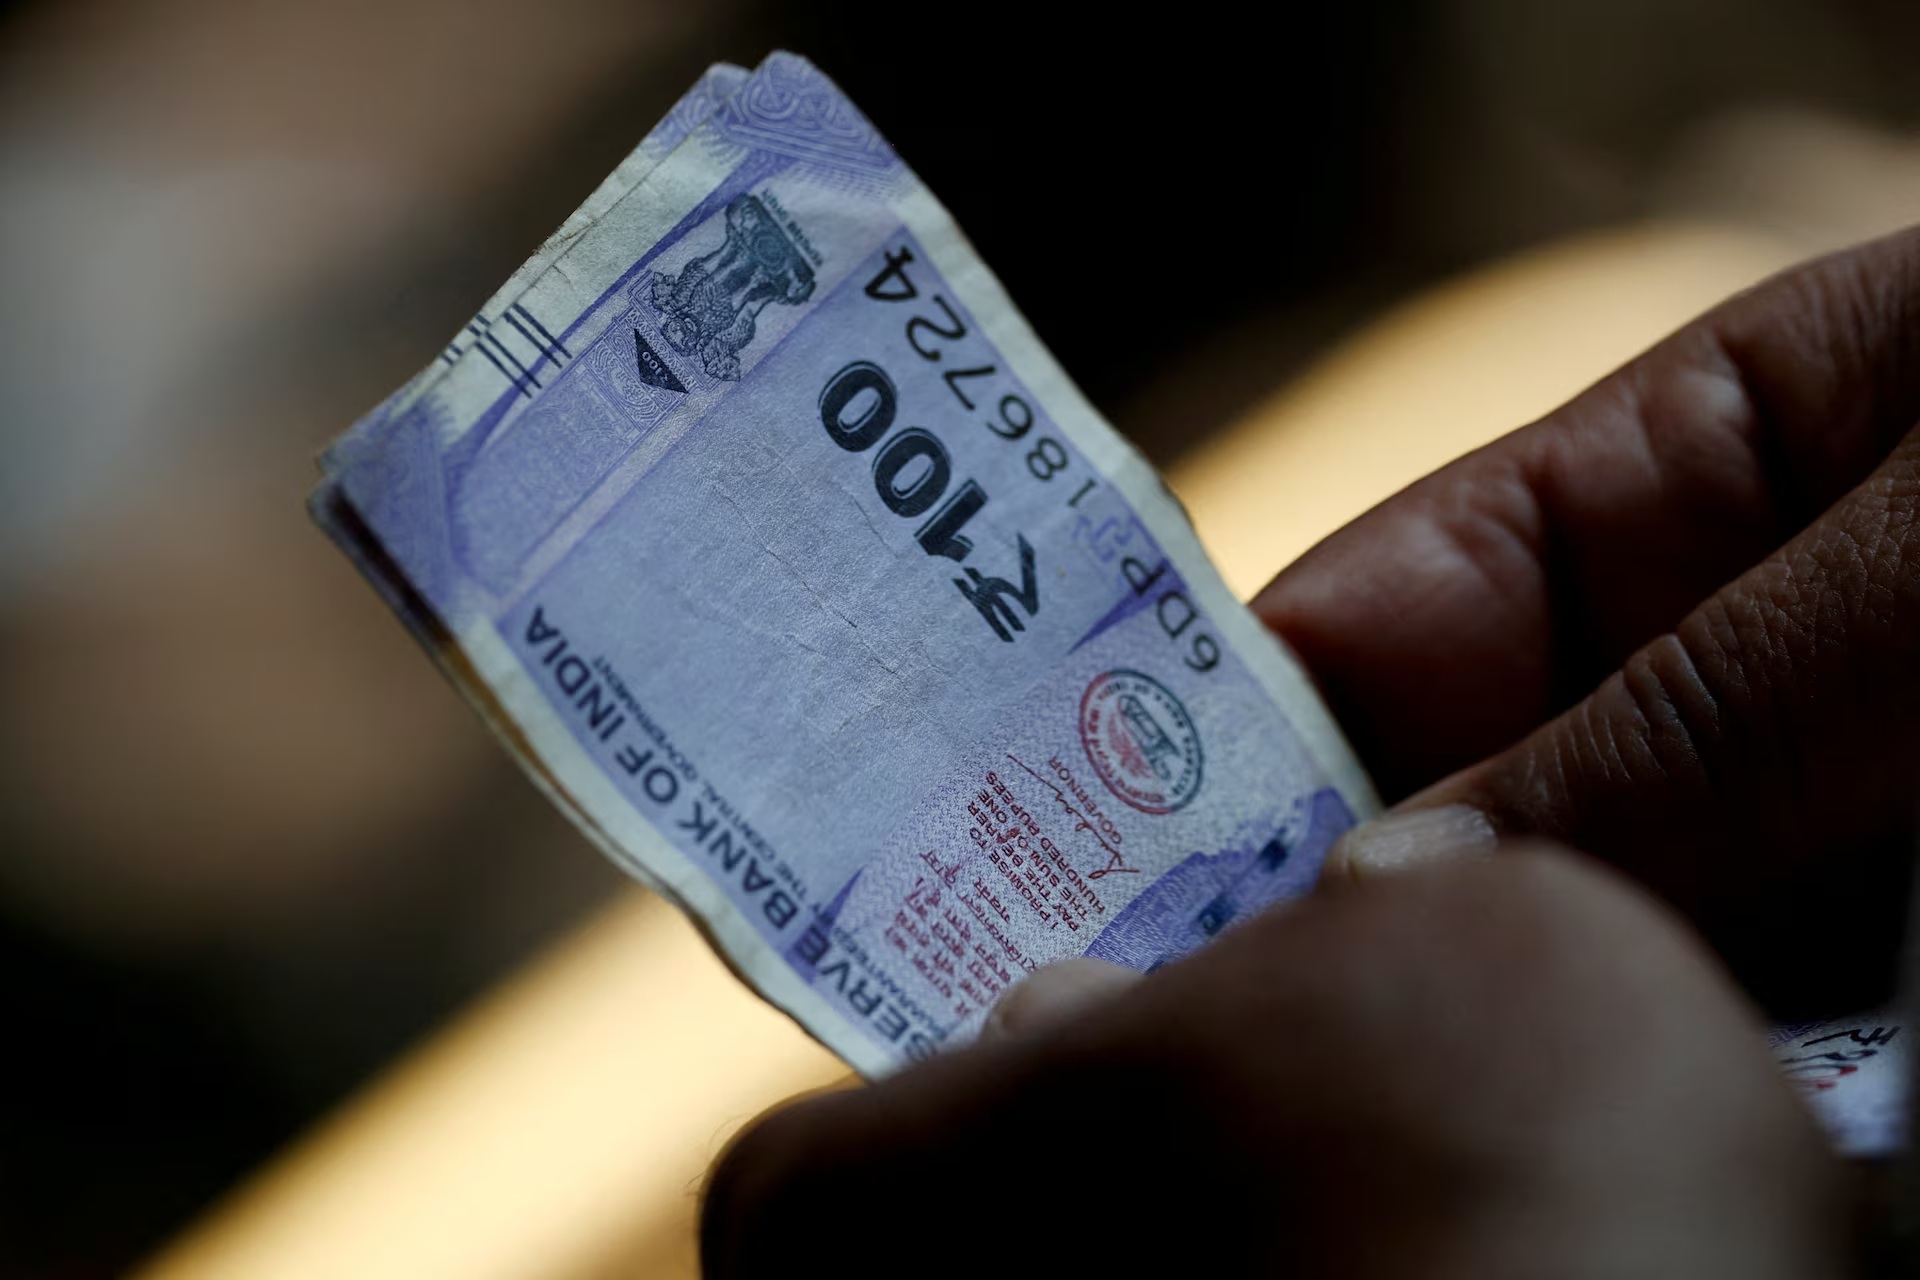
India’s central bank has introduced emergency measures to ease pressure on the rupee, redirecting major state-owned oil companies’ dollar purchases away from the spot foreign exchange market and raising the cost of currency hedging as the currency approaches record lows.
The Reserve Bank of India (RBI) announced the measures on Saturday as the rupee continued to weaken under pressure from surging oil prices, elevated global bond yields and persistent demand for dollars. The currency has lost more than 7% against the US dollar this year, despite sustained central bank intervention, fresh capital-raising initiatives and an interest-rate increase earlier in the week.
The new measures target two sources of pressure: the substantial dollar requirements of India’s oil importers and the growing demand for financial instruments that protect businesses against further rupee depreciation.
Register for the next Tekedia Mini-MBA.
Register for Tekedia AI in Business Masterclass.
Join Tekedia Capital Syndicate and co-invest in great global startups.
Under the first measure, the RBI will establish a special facility to meet the daily dollar requirements of Indian Oil Corporation, Hindustan Petroleum and Bharat Petroleum. The three state-run oil-marketing companies will be able to access the facility from Monday, allowing them to obtain dollars directly from the central bank’s foreign exchange reserves rather than competing for the currency in the spot market.
The arrangement is intended to reduce immediate demand in the market where dollars are bought and sold, potentially limiting the pressure that large oil-related transactions place on the rupee.
However, the intervention involves a trade-off. Supplying dollars directly to oil companies could stabilize market conditions in the short term while reducing the central bank’s foreign exchange reserves, particularly if elevated oil prices keep importers’ dollar requirements high.

“Addressing oil companies’ dollar requirements removes one of the largest sources of demand from the FX market, which should help reduce volatility but it will show up in a depletion of reserves,” said Dhiraj Nim, an FX strategist at ANZ Bank in Mumbai.
Following the announcement, the rupee strengthened by about 0.6% against the dollar in the non-deliverable forward market, although trading was thin. The initial response suggested that investors viewed the measures as supportive, but it did not establish whether the currency’s broader downward trend had been reversed.
RBI Raises The Cost of Betting Against The Rupee
Alongside the oil companies’ dollar facility, the RBI has tightened rules governing foreign exchange derivatives, seeking to curb excessive hedging and speculative activity that could intensify demand for dollars.

The measures come as Indian importers increasingly seek protection against further rupee depreciation, with demand for dollars significantly exceeding the supply coming from exporters. Currency derivatives allow companies and financial market participants to manage exposure to exchange-rate movements. Importers, for example, can use these contracts to lock in exchange rates for future dollar payments, reducing uncertainty over the domestic-currency cost of imported goods.
But when demand for protection against depreciation rises sharply, it can add to pressure on the currency market. The RBI’s latest rules are intended to moderate that demand without eliminating legitimate hedging by businesses with genuine foreign exchange exposure.
A person familiar with the central bank’s thinking told Reuters the RBI was “trying to moderate potentially destabilizing derivative demand, improve the integrity of underlying exposure verification and discourage circumvention through multiple transactions or repeated rebooking”.
The central bank has mandated that foreign exchange dealers maintain a 20% “foreign exchange risk reserve” on derivative contracts used to buy foreign currency against the rupee for hedging current-account transactions. The requirement applies to transactions with a notional value exceeding $2 million.
The reserve requirement is expected to increase the cost of providing these contracts, which could discourage excessive demand for protection against further rupee weakness. Two bankers said the measure would make it more expensive to buy such protection. Although the rule does not prohibit companies from hedging genuine exposures, the higher cost could lead some market participants to reduce the size or frequency of their transactions.
The RBI has also sharply reduced the threshold for derivative transactions that users can undertake without providing proof of an underlying exposure. The limit has been cut to $5 million from $100 million, with the lower cap applying across derivative products, including exchange-traded futures.
The reduction narrows the scope for large transactions without evidence of an underlying commercial or financial exposure. It also strengthens the central bank’s ability to distinguish risk management by businesses from activity that could amplify pressure on the currency.
China has previously used comparable measures to discourage one-way bets against the yuan, illustrating how authorities can use derivative-market restrictions to influence trading behavior during periods of currency stress.
For India, the challenge is to reduce destabilizing market activity without unnecessarily restricting businesses’ ability to manage foreign exchange risk. If the rules make legitimate hedging substantially more expensive, companies could face greater uncertainty over future import costs. If they successfully reduce speculative or excessive demand, however, they could help moderate short-term volatility.
Capital Inflows Have Failed to End Currency Pressure
The latest intervention follows a series of measures through which India has raised more than $140 billion in capital inflows, including initiatives to attract overseas foreign currency deposits and arrangements involving offshore borrowing by state-run companies and banks. Despite those efforts, the rupee remains under pressure. The persistence of the decline suggests that attracting additional foreign currency and intervening in the market have not been sufficient to offset the underlying demand for dollars.
Oil prices have become an important factor for India because the country depends heavily on imported crude. When oil prices rise, refiners and other importers require more dollars to settle purchases, increasing demand for foreign currency. Unless those requirements are matched by stronger dollar inflows, the additional demand can weigh on the rupee.
Higher global bond yields can compound the pressure by affecting international investment decisions and the relative attractiveness of dollar-denominated assets. When global financial conditions become less favorable for emerging markets, currencies such as the rupee can face additional headwinds from capital flows.
These pressures also complicate monetary policy. An interest-rate increase may support a currency by improving the relative return on domestic assets, but its effectiveness depends on broader market conditions. If oil prices remain elevated and foreign exchange demand continues to exceed supply, higher interest rates alone may not be enough to reverse depreciation.
The RBI’s latest measures therefore focus on managing the immediate mechanics of currency demand rather than addressing all the factors driving the rupee lower.
Directly supplying dollars to oil companies is expected to remove a significant source of spot-market demand, while the derivative restrictions may discourage transactions that increase pressure on the currency. Together, the measures give the central bank additional tools to manage market conditions as external pressures persist.
However, analysts warn that the oil facility could place further demands on foreign exchange reserves if it is used extensively. Reserves provide India with a buffer against external shocks and help reassure investors that the country can meet its foreign currency obligations. Using them to support the rupee may be justified during periods of stress, but sustained intervention can become more difficult if market pressure persists.
The effectiveness of the measures will consequently depend not only on the initial market reaction but also on the scale of dollar withdrawals from reserves, developments in oil prices and the direction of capital flows.
Nim said the steps should moderate, rather than eliminate, pressure on the rupee.
“The underlying drivers, including oil prices and capital flows, remain, and the real test will be how reserves and the rupee behave in the coming week,” he added.
That assessment captures the central challenge confronting the RBI. The new rules may reduce immediate dollar demand and make speculative positions more costly, but they cannot independently reverse the external conditions driving the currency lower.