DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 105

Congo Copper Floods U.S. Market as Buyers Seek Discounts to COMEX Prices

0

U.S. copper buyers are now turning to metal from the Democratic Republic of Congo as a cheaper alternative to COMEX-deliverable brands, driving the African producer’s shipments to the United States to a record level and reshaping global trade flows for the industrial metal.

U.S. imports of Congolese copper cathodes reached a record 53,290 metric tons in July, according to U.S. trade data. The volume represented 23.9% of total U.S. copper imports, which surpassed 220,000 tons for the first time as traders accelerated shipments ahead of the possibility of a U.S. tariff on copper.

The July figures mark a sharp increase from 2024, when the United States imported less than 32,000 tons of copper from Congo for the entire year. The surge reflects both rising U.S. demand and Congo’s growing ability to supply international markets. Congo is the world’s second-largest copper producer, and increased output has given traders more metal to place in markets beyond its traditional customer base.

The shift has gained attention because copper produced in Congo is not currently eligible for physical delivery against COMEX contracts. Only two African copper brands, both from Zambia, are listed as deliverable on the U.S. exchange, while more than one-third of approved COMEX brands originate from Chile and Peru.

That situation has created a significant pricing opportunity for U.S. industrial consumers.

Albert Mackenzie, a copper analyst at Benchmark Mineral Intelligence, said the import data suggested Congolese copper could be moving directly into the U.S. physical market rather than being used primarily to satisfy exchange-delivery requirements.

“And if it is, it will be a lot cheaper than the COMEX-deliverable brands,” Mackenzie said.

The economics became compelling during the summer as U.S. copper prices traded at a substantial premium to the London Metal Exchange benchmark.

Mackenzie said the premium for COMEX copper over the LME price reached $400 to $600 per ton at times over the summer. That created an incentive for end-users to purchase copper priced against the LME rather than pay the premium associated with COMEX-registered material.

“So buying non-CME registered material on an LME basis might actually have been cheaper for end-users,” he said.

Two industry sources involved in trading Congolese copper confirmed that the material is generally priced against the LME. One source said his copper is typically sold at a discount of $550 to $800 a ton, partly to compensate buyers for freight costs.

The discounts can make Congolese cathodes attractive to manufacturers that need physical copper for production rather than traders seeking exchange-deliverable inventory.

U.S. buyers include copper rod mills and tube manufacturers, according to one industry source.

The growing acceptance also reflects improvements in the quality of Congolese copper in recent years, the source said. Higher-quality material has made it easier for U.S. industrial consumers to incorporate Congo-origin cathodes into their supply chains.

The development demonstrates that COMEX registration is not necessarily a prerequisite for strong physical demand. Industrial users primarily need copper that meets their technical specifications and can be delivered reliably at a competitive price.

The rapid increase in shipments to the United States is also beginning to affect Congo’s trade relationship with China. The world’s second-largest economy remains by far the largest destination for Congolese copper, but its imports from Congo fell 4.3% during the first seven months of 2026 as increasing volumes were directed toward the United States and other markets.

Even with the decline, Congo’s share of China’s copper imports during the period increased by five percentage points to 44.7%, underscoring how important the African producer remains to China’s supply chain. In July, China imported 95,778 tons of copper from Congo, giving Congo a 39.4% share of Chinese imports. That was China’s lowest monthly share of Congolese copper since October last year, although Congo remained China’s largest supplier by a wide margin.

The figures point to an increasingly competitive market for Congolese copper. Rather than depending overwhelmingly on Chinese smelters and manufacturers, Congolese producers and traders now have an opportunity to redirect shipments toward markets where pricing is more attractive.

The timing of the U.S. import surge coincides with global tariff tension.

Traders rushed to move copper into the United States ahead of a potential tariff, creating an incentive to bring cargoes forward before any new trade restrictions could increase costs. That front-loading may partly explain the exceptional July import figure and could make U.S. imports more volatile in subsequent months if the tariff threat changes or inventories rise.

Nevertheless, the underlying price advantage of Congolese copper could persist even after the immediate rush fades.

The gap between COMEX and LME prices effectively created a two-tier market: exchange-deliverable copper commanded a significant premium, while non-COMEX material that could be delivered directly to industrial users was available at a discount.

For U.S. manufacturers, that creates a powerful incentive to broaden their supplier base.

Congo’s Growing Influence in Global Copper

Congo’s expanding role in the U.S. market comes as global copper demand is expected to remain structurally strong because of electrification, power-grid investment, renewable energy, and data-center construction.

Copper is essential for electrical wiring, transformers, motors, industrial equipment, and power infrastructure. The rapid expansion of AI data centers has added another source of demand because large computing facilities require substantial quantities of copper for power distribution and cooling systems.

The United States has traditionally relied heavily on copper from Latin America and other established suppliers. The emergence of Congo as a major source gives U.S. buyers another option at a time when concerns about supply security and trade restrictions are encouraging manufacturers to diversify.

But the shift offers Congo the possibility of capturing more value from rising global demand and reducing dependence on a single dominant customer. The country’s copper production growth is now changing not only the volume of metal available but also its bargaining position in international markets.

However, it is currently not clear if July’s record U.S. shipments represent a temporary response to tariff fears and the exceptional COMEX premium or the beginning of a more permanent reorientation of Congolese copper toward Western consumers. Analysts note that if the latter occurs, U.S. manufacturers could become a significantly larger outlet for Congo’s expanding production, while China may face greater competition for a resource that has become so important to the global energy and industrial transition.
Sterling Gains Against Dollar as Yen Rebound Overshadows UK Policy Speech

0

The pound edged higher against the dollar and held broadly steady against the euro on Monday, but fell sharply against the Japanese yen as markets weighed Britain’s economic policy outlook against a broader shift in global interest rates and risk sentiment.

Sterling rose 0.14% to $1.3573 and traded at 85.86 pence per euro, leaving it only marginally stronger against the common currency. Its biggest move was against the yen, where it fell 0.8% to 209.41 yen, its lowest level since February.

The moves came after British Finance Minister John Healey delivered his first major economic speech, outlining plans to give city regions greater powers to attract private investment as Prime Minister Andy Burnham’s government seeks to transfer more economic decision-making away from central government.

Healey also emphasized fiscal discipline, efforts to reduce business and household costs, and measures to boost economic growth.

For currency traders, however, the speech offered few new signals capable of materially changing expectations for Britain’s fiscal or monetary outlook. Much of Healey’s emphasis on growth, deregulation and the cost of living continued policies associated with his predecessor, Rachel Reeves.

Attention is therefore shifting toward the government’s October Budget, where investors will look for greater clarity on how Healey intends to finance the government’s economic priorities while maintaining control of public finances.

Barclays said the transition from the traditionally quieter August trading period to a more closely watched policy environment could increase pressure on sterling. Higher global bond yields have also complicated the outlook for the currency.

“The August lull is giving way to a period of increased scrutiny on UK policies and fundamentals, shifting the risk-reward modestly to the downside for the pound,” Barclays analysts said.

Investors are especially focused on how the government will reconcile its growth agenda with spending demands in areas including housing, social care and defense. The more expensive the government’s commitments become, the greater the pressure on borrowing costs and the fiscal outlook could be.

The pound’s decline against the yen was considerably more pronounced as Japan’s currency strengthened against major currencies.

Sterling had reached a 19-year high against the yen in August, while the yen had also fallen to a 40-year low against the dollar. The subsequent reversal suggests that some of the extreme bearish positioning against the Japanese currency may be unwinding.

Possible repatriation of Japanese capital, the unwinding of carry trades and expectations that the Bank of Japan could accelerate interest-rate increases are providing support for the yen. Political pressure from Washington on Japan’s economic and currency policies could also influence expectations around the yen.

The yen’s recovery is significant for global markets because it can affect the carry trade, in which investors borrow in low-yielding currencies such as the yen to invest in higher-yielding assets elsewhere. A sustained rise in Japanese rates or the yen can make those positions less attractive and potentially trigger broader portfolio adjustments.

Meanwhile, global investors entered the week with a growing focus on inflation and interest rates as oil prices climbed amid the continuing U.S.-Iran conflict.

Brent crude rose 1.1% to $97.31 a barrel, while West Texas Intermediate gained 1.3% to $92.66, with both benchmarks reaching six-week highs.

The rise in energy prices is becoming a threat to the disinflation trend because higher fuel and transportation costs can feed into consumer prices while simultaneously reducing household purchasing power. That dynamic is of interest to central banks because higher inflation caused by an energy shock could limit their ability to cut interest rates or force policymakers to maintain restrictive settings for longer.

U.S. Treasury yields have already responded to those concerns. The benchmark 10-year Treasury yield last week reached its highest level since November 2023, while the two-year yield climbed to its highest level since January 2025.

“A run of central bank meetings over the coming weeks will test whether equity composure holds,” said Ed Yardeni, president of Yardeni Research. “Bond yields are also rising worldwide. The question is whether that reflects better-than-expected economic growth, higher-than-expected inflation, and/or looming fiscal debt crises.”

The Federal Reserve’s policy meeting next week will be a major test for markets. Traders were pricing a roughly 60% probability of a 25-basis-point rate increase, according to CME Group’s FedWatch tool.

Those expectations could shift rapidly with U.S. wholesale and consumer inflation data due later this week. Another sharp increase in crude prices could further complicate the Fed’s decision by raising inflation expectations while weakening economic activity.

U.S. equity futures also pointed to a cautious start to the week. Dow futures fell 308 points, or 0.6%, while S&P 500 futures declined 0.2%. Nasdaq-100 futures gained 0.1%. U.S. stock markets were closed Monday for the Labor Day holiday.

Geopolitical and trade risks added another layer of uncertainty.

Canada is due to impose retaliatory tariffs on about $20 billion of U.S. goods on Tuesday, escalating trade tensions with Washington. Trump also threatened Canadian aircraft manufacturer Bombardier with exclusion from the U.S. market unless the company begins manufacturing its products in the United States.

“NO MORE SELLING BOMBARDIER IN THE UNITED STATES!” Trump wrote on Truth Social.

The combination of higher oil prices, rising global bond yields, shifting central-bank expectations and renewed trade tensions leaves currency markets facing several competing forces.

Samsung, TSMC Commit to ASML High-NA EUV as AI Drives Chipmaking Complexity

0

Samsung Electronics and TSMC, the world’s two largest chipmakers, have committed to using ASML’s next-generation High-NA extreme ultraviolet lithography machines, strengthening the Dutch equipment maker’s position at the center of the global semiconductor industry’s race to produce advanced chips.

The commitments provide ASML with greater visibility into demand for its most sophisticated lithography technology at a time when chipmakers are investing heavily to keep pace with the rapidly increasing computational requirements of artificial intelligence.

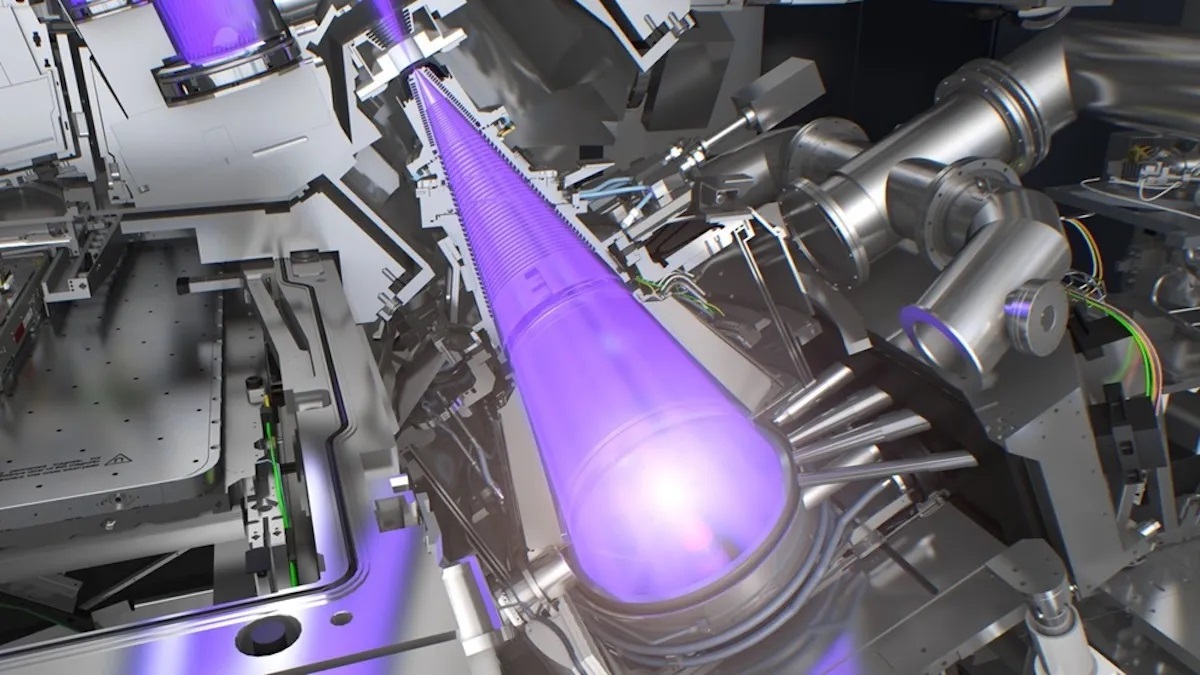
ASML’s EUV lithography systems are among the most critical and expensive machines in semiconductor manufacturing. They use extreme ultraviolet light to print extraordinarily fine circuit patterns onto silicon wafers, allowing chipmakers to build smaller and more sophisticated transistor structures.

High-NA EUV represents the next generation of the technology, using a higher numerical aperture to print smaller and more intricate patterns with greater precision. Each machine can cost around $400 million.

Samsung, one of the world’s largest memory-chip manufacturers, said it plans to use High-NA EUV machines for DRAM production from 2028.

The company said the technology would allow it to “extend the DRAM scaling roadmap” while improving manufacturing efficiency.

The move is seen as a game-changer for the memory industry, where manufacturers are under pressure to increase density and performance as demand for high-bandwidth memory and other advanced components rises alongside AI computing.

TSMC, the world’s largest contract chipmaker, said it would deploy High-NA EUV for advanced logic chips and expects its use of the technology to increase. The Taiwanese company said adoption would be driven “primarily by the increasingly complex transistor architectures required for AI applications.”

The commitments from Samsung and TSMC illustrate how the AI boom is affecting the semiconductor industry well beyond demand for processors.

Advanced AI systems require chips containing large numbers of transistors, while improvements in performance and energy efficiency depend on manufacturers continuing to shrink and refine those transistor structures.

That is making lithography one of the industry’s most important technological bottlenecks.

ASML is effectively the sole supplier of the world’s most advanced EUV lithography systems, giving it an unusually powerful position in the semiconductor equipment industry. The transition to High-NA EUV is therefore being closely watched by investors as a potential new growth cycle for the company.

Barclays said in a note Tuesday that the announcements “should provide more visibility on adoption which has been a key debate,” describing the developments as “a positive.”

ASML shares were flat to slightly lower in early Amsterdam trading on Tuesday, even as investors assess the implications of the commitments for future equipment demand.

The stock has risen about 120% over the past year, reflecting expectations that sustained investment in AI infrastructure will translate into greater spending on advanced semiconductor manufacturing equipment.

Samsung and TSMC join Intel

Samsung and TSMC now join Intel as customers for ASML’s High-NA machines. In July, ASML said Intel was already using High-NA EUV technology for advanced chip manufacturing, making the three leading semiconductor manufacturers early adopters of the technology.

The commitments are necessary because High-NA EUV machines are substantially more expensive and technically demanding than previous-generation EUV systems. Their commercial success therefore depends on whether the world’s leading chipmakers believe the additional manufacturing capability justifies the enormous investment.

ASML has not provided a recent forecast for the number of High-NA machines it expects to sell. However, the company has said it plans to increase its overall EUV capacity by about 30% in 2027.

Barclays analysts said the Samsung and TSMC announcements should improve ASML’s ability to plan future capacity.

“We see ASML with a significant decision ahead on whether to further expand EUV capacity than the recently expanded targets it has already given. Demand is clearly strong,” the analysts said.

That creates an important strategic decision for ASML. Expanding production too aggressively could leave the company with excess capacity if High-NA adoption takes longer than expected. Moving too slowly, however, could constrain sales at a time when AI-related semiconductor investment is accelerating.

The latest commitments tilt the balance toward stronger demand visibility.

Samsung and TSMC are also joining ASML in an industry initiative aimed at advancing next-generation 12-inch photomask technology, replacing the current 6-inch format. Photomasks function essentially as stencils in semiconductor manufacturing. They contain the patterns that are transferred onto silicon wafers during lithography and are therefore a critical part of the chip production process.

ASML said larger photomasks could improve productivity and reduce chipmaking costs.

The development highlights another aspect of the industry’s transition to more advanced manufacturing: progress is not limited to the lithography machine itself. Chipmakers and equipment suppliers are also redesigning surrounding processes to make complex production economically viable.

For Samsung and TSMC, the ability to manufacture more advanced chips efficiently will become more important as the cost of leading-edge fabrication rises. The adoption of High-NA EUV by Samsung, TSMC and Intel provides an early indication that the technology is moving beyond the experimental stage toward broader commercial deployment.

The timetable is still gradual. Samsung’s planned DRAM adoption from 2028 and TSMC’s expectation of increasing use suggest that High-NA EUV will become a progressively larger part of advanced chip manufacturing rather than replacing existing EUV systems overnight.

That transition could nevertheless create a substantial new equipment market for ASML.

The economics are compelling for chipmakers if High-NA technology allows them to produce more sophisticated transistor structures with fewer processing steps, higher yields, or better performance. The $400 million price tag for an individual machine becomes easier to justify if it reduces other manufacturing costs or enables chips that cannot be produced economically with older technology.

Therefore, the announcements represent more than customer commitments. They provide ASML with evidence that the world’s leading chipmakers are preparing to spend heavily on the next generation of lithography as AI pushes semiconductor designs toward greater complexity.

Banana Bot Copy Trade vs Fomo’s Social Feed: Who Exits First When the Whale Sells

0

Your phone buzzes. A trader you follow on Fomo just closed a big position.

You have seconds to decide what your own screen is telling you to do, and the answer is not the same on every platform.

A copy means something different on each platform

On Fomo, a self-custodial social trading app live on Solana and Robinhood Chain, following a trader gives you a feed: notifications on every buy or sell, plus the app’s own promise of “ONE CLICK TO BUY.”

Banana Gun’s Copy Trade works from the other direction. It mirrors a wallet address from a wallet you control, and filters like Buy Fixed, Buy Only Once and Min/Max Market Cap get set before the trade happens, not after.

One system hands you information and waits for a decision. The other executes a decision you already made. Read how wallet mirroring works across chains in Banana Gun’s copy trading guide before you pick a wallet to follow.

What happens on Fomo when the wallet you follow sells

You get a notification. What you do after it is on you.

Fomo’s own guides build the whole process around that alert. Every step after the buzz is a step you take yourself.

What happens in Banana Gun’s Copy Trade when the wallet sells

Nothing waits for you to notice. A Trailing Stop Loss you set earlier closes the position once price reverses.

A limit order placed in advance fills if price reaches your level. Both of them watch price alone, with no view of the whale’s wallet.

The docs also list a Copy Sell option. Confirm inside the bot what it does on your chain before you rely on it.

Who exits first

The copied wallet exits first, always, in both systems. Whether you’re on Fomo or running Banana Gun’s Copy Trade, the trade you’re mirroring closes before your own position does.

Your exit follows the wallet’s in both systems.

What changes is what fills the gap between the wallet’s sell and yours. On Fomo, a person fills it: you, reading a notification, weighing it, then acting on your own judgment about where price stands.

In Banana Gun’s Copy Trade, an order fills that gap instead, and it already existed before the wallet sold anything. A Trailing Stop Loss or a limit order sits in the bot waiting on a price level rather than on a wallet address.

It has no idea why price moved, and it does not need to. It only knows the number you gave it earlier.

Banana Gun exits on the terms you set, whenever price crosses them, whether the copied wallet has sold yet or not.

What Fomo’s own guides say about exits

Fomo tells its own users to prepare for this moment themselves.

Fomo’s own copy-trading guide (1 February 2026) and risk guide (25 December 2025) describe exits as notifications plus levels you hold in your head; neither describes a take profit or stop loss order attached to a copied position.

What the 95.2 percent stat says about exits on a social feed

Unfolded’s read of Dune data found 95.2 percent of 375,740 Fomo users on Robinhood Chain lost money or made under 100 dollars.

BigGo’s reporting on the same data attributes much of that skew to copied exits. A feed that tells you a wallet sold is a different thing from a position that closes on its own. Of those 375,740 users, 229 made more than 10,000 dollars, per the same analysis.

Two things that break on Fomo’s side

Fomo’s own risk guide says it plainly: with memecoins, “most traders not using hard stop losses/take profits,” and the same guide tells readers to have mental levels in place.

Fomo’s guide lists enabling notifications as its own step. A follower who skips it is waiting on an alert they never switched on.

Two things that break on Banana Gun’s side too

A Trailing Stop Loss set too tight closes you out on a single wick, before any real reversal takes shape in the chart.

A limit sell placed at a fixed price never fills if the token gaps straight through that level on the way down. Both are settings you chose, so both are yours to widen or move.

What no exit option promises

An order you configured is only as good as the level you gave it, on either side of a trade.

Any copied exit, whatever the option is called, lands after the wallet’s own sell, the same way a Trailing Stop Loss lands after price reverses. Nothing in either system removes that gap entirely.

Setting the exit before you need it

The order has to exist before the wallet sells. Set a Trailing Stop Loss or a limit order the moment you open a copy, before the first notification would even arrive.

That is the entire difference this comparison comes down to: a human acting on an alert, or an order that was already waiting on price.

Pick the wallet, then pick your exit

Wallet selection still decides most of the outcome, on either platform. A bad wallet loses money no matter how fast you react to it, and no exit rule fixes that on its own.

Open Banana Gun’s Telegram bot and set a Trailing Stop Loss or a limit order before you copy your first trade.

The Hidden Easter Egg in Nvidia’s $12.9303 Billion Hugging Face Deal

0

When Nvidia announced its agreement to acquire artificial-intelligence platform Hugging Face for $12.9303 billion, the unusually precise figure immediately stood out. Most billion-dollar acquisitions are presented in rounded numbers, but this one carried six extra digits that appeared almost deliberately engineered.

As it turns out, they were. Hugging Face co-founder Thomas Wolf hinted that the acquisition price contained references to both Hugging Face and Nvidia, challenging observers to decode the number.

The first clue was relatively easy for technically minded audiences to spot: 129,303 is the decimal representation of Unicode code point U+1F917, the official Unicode character for the ? “Hugging Face” emoji.

That is more than a clever coincidence. The emoji is central to Hugging Face’s identity.

The company, founded in 2016 by Clément Delangue, Julien Chaumond and Thomas Wolf, took its name from the familiar digital symbol and eventually transformed from a chatbot project into one of the world’s most important platforms for open AI models, datasets and developer tools.

The second half of the puzzle was more difficult. Some observers initially interpreted 12-93-03 as a collection of Nvidia references: $12, the company’s initial public offering price; 1993, the year Nvidia was founded; and three, representing its three founders.

It was an ingenious theory—but it was not the intended answer. Hugging Face CEO Clément Delangue ultimately pointed toward the real Nvidia connection: 129303 is also a hexadecimal color code, #129303, corresponding to a vivid green remarkably close to Nvidia’s iconic brand color.

Suddenly, the acquisition price becomes a piece of corporate wordplay. The number simultaneously points toward the identity of Hugging Face and the visual identity of Nvidia. What initially looks like an unusually precise financial valuation is effectively a digital handshake between two technology companies.

The joke also reveals something about the character of the transaction. Nvidia is paying roughly $12.9 billion for a company whose value is not simply measured by conventional revenue multiples.

Hugging Face has become a major gathering place for AI developers, researchers and organizations. Nvidia said more than 18 million developers, researchers and creators use the platform, alongside more than 200,000 companies. The platform hosts millions of models, datasets and applications.

That makes the acquisition strategically important beyond the headline price. Nvidia is not merely purchasing software. It is gaining deeper access to the open-model ecosystem and a huge community of developers building the next generation of AI applications.

Crucially, Nvidia says Hugging Face will remain an open platform. Developers will continue to choose their preferred models, frameworks, cloud providers and computing platforms, rather than being forced to use Nvidia hardware.

The Easter egg therefore works on two levels. It is playful enough to reward developers who understand Unicode and hexadecimal notation, but meaningful enough to symbolize the relationship Nvidia is buying into.

In an industry dominated by enormous valuations and serious strategic battles, the $12.9303 billion figure is a reminder that technology companies are sometimes built by people who enjoy the same technical details as their communities.

Hidden inside one of the biggest AI acquisitions is a simple message: Hugging Face meets Nvidia—right down to the code.