DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 3

AI’s Criminal Arms Race Is Becoming a Governance Problem

0

Artificial intelligence is becoming one of the most useful tools in finance—and one of the most efficient tools for criminals.

According to TRM Labs, criminal use of AI rose 40% over the past year, reflecting how quickly scammers are incorporating the technology into increasingly sophisticated attacks.

The development points to a broader transformation in digital crime: the problem is no longer simply that criminals have better tools, but that those tools can operate at scale.

For years, online scams depended heavily on human effort. A fraudster might manually contact potential victims, construct convincing messages, impersonate a company executive or search for information that could make a scam more believable.

Generative AI changes the economics of that process. It can produce personalized messages, imitate communication styles, translate languages and automate repetitive interactions, allowing relatively small operations to target far more people.

Crypto markets are particularly exposed because transactions can move rapidly across borders and, once completed, can be difficult to reverse. A convincing phishing message or fabricated investment opportunity can therefore become a financial event within minutes.

AI does not necessarily create entirely new forms of fraud; instead, it can make existing techniques cheaper, faster and more convincing.

That creates an uncomfortable symmetry for cryptocurrency exchanges. The same technology being used to attack financial infrastructure is increasingly being deployed to defend it.

Exchanges can use AI and machine-learning systems to identify unusual transaction patterns, flag suspicious accounts, detect coordinated activity and prioritize investigations.

But this introduces another layer of risk. When an exchange relies on automated systems to identify potentially criminal behavior, the quality of those systems becomes part of the security architecture.

A model can produce false positives, miss sophisticated attacks or react incorrectly to unusual but legitimate behavior. In a financial environment, an error is not merely technical. It can mean a delayed withdrawal, a frozen account or a legitimate transaction being treated as suspicious.

This is where governance becomes as important as detection. KuCoin’s acquisition of ISO/IEC 42001:2023 certification for its AI management system illustrates the emerging focus on that problem.

The international standard addresses how organizations establish governance around artificial intelligence, including responsibilities, processes and oversight. Its significance is therefore different from a claim that an AI system will always make the correct decision.

An AI management certification cannot guarantee that an automated fraud-detection model will never make a mistake. What it can provide is a framework for asking whether an organization has established procedures for managing those risks.

Who is responsible when an AI system produces an erroneous result? How are models reviewed? How are failures documented? Can decisions be challenged? And how does an organization respond when criminals adapt to the system?

These questions will become increasingly important as AI becomes embedded in financial infrastructure. The next phase of crypto security may therefore involve an arms race between automated offense and automated defense.

Criminal groups can use AI to increase the volume and sophistication of attacks, while exchanges can use AI to process enormous quantities of transactions and identify anomalies that humans could not efficiently detect.

The decisive issue may not be whether AI is used, but whether its use is governed responsibly. As artificial intelligence becomes part of the machinery protecting billions of dollars in digital assets, transparency, accountability and human oversight are becoming security controls in their own right.

The technology can detect threats, but governance determines what happens when the technology itself becomes wrong.
Wall Street’s Earnings Test Meets the AI Agent Monetization Question

0

As another earnings season approaches, Wall Street is entering a familiar but increasingly complicated phase: investors must decide whether lofty expectations for corporate growth are actually supported by earnings.

While simultaneously trying to understand where the next generation of artificial intelligence businesses will generate durable revenue. Morgan Stanley has highlighted more than a dozen stocks it is watching closely heading into earnings season.

Reflecting a market where expectations have become almost as important as the reported numbers themselves. For investors, the question is no longer simply whether companies can beat quarterly estimates.

It is whether management teams can demonstrate that current valuations are supported by sustainable demand, improving margins and credible growth.

That distinction matters particularly for technology companies. The artificial-intelligence boom has already produced enormous gains for chipmakers, cloud providers and software companies supplying the infrastructure behind increasingly sophisticated models.

But earnings season can expose the difference between capital expenditure and actual economic returns. Companies may be spending heavily on AI because they fear falling behind competitors.

Yet investors need evidence that these investments can translate into higher productivity, stronger pricing power, new customers or entirely new revenue streams.

That leads directly to another question highlighted by Goldman Sachs: How will AI agents actually make money? AI agents represent a potential shift from today’s chatbot economy.

Instead of simply answering questions, agents are designed to perform tasks: conducting research, managing workflows, writing software, arranging transactions or interacting with other digital systems.

If that vision becomes commercially viable, the economic model could move beyond subscriptions and toward transaction-based or outcome-based payments. An agent that completes a business process could potentially be paid according to the value or volume of the work it performs.

A sales agent might generate revenue through completed transactions. A coding agent could be priced according to software development output. A financial agent might eventually execute permitted services and receive fees associated with those activities.

But monetization remains unresolved. The challenge is that AI agents could also place enormous pressure on existing software businesses. If one agent can replace several software interfaces, customers may become less interested in paying for dozens of separate applications.

Instead, they could pay for an intelligent system capable of completing the underlying task. That would fundamentally change the economics of software. For public markets, earnings season therefore becomes a test of two related narratives.

The first concerns whether today’s AI spending is producing measurable financial returns. The second concerns whether tomorrow’s AI products can establish business models capable of capturing those returns.

Morgan Stanley’s stock watchlist and Goldman’s focus on agent monetization point toward the same underlying issue: AI enthusiasm eventually has to become an income statement reality. Investors will be watching revenue growth, margins, capital expenditure, guidance and customer demand for clues.

Meanwhile, the AI industry is still experimenting with how autonomous systems should be priced and what customers will actually pay for. The market may have already priced in much of the technological promise.

The harder task now is identifying the economic architecture that converts that promise into recurring cash flow. This earnings season, therefore, is not merely about who beats estimates. It is increasingly about whether the companies building the AI economy can prove that intelligence itself can become a scalable business.

What Crypto to Buy Now? BlockDAG’s $0.03 USDT Buyback Opens as Zcash Holds $1,506 and Hyperliquid Crosses $97

0

Two things are on every serious crypto buyer’s radar on September 23, 2026: where the market is moving and where the next clean entry is. Zcash is holding above $1,506 after a 21Shares ETP launched on Euronext Amsterdam and Paris, adding regulated European access to a token already backed by a Grayscale ETF with over $233 million in inflows. Hyperliquid crossed $97.46 on $429 million in year-to-date on-chain protocol revenue and a new Layer 2 testnet going live.

And BlockDAG just handed holders a calculation they can run in seconds: a $0.03 USDT Buyback Price, 1.5 times the previous rate of $0.02, live for 7 days only, with direct BDAG available at $0.00000017 and both Legacy and New BDAG purchases counting toward your eligible Buyback Allocation. For anyone deciding what crypto to buy now, the dashboard has the number. The window has a deadline.

BlockDAG (BDAG): The USDT Figure on Your Dashboard Is Not the Finish Line. It Is the Starting Point.

Most presale projects measure success by what they raise. BlockDAG is measuring something different right now: whether holders can see exactly what they own, in dollar terms, before they decide what to do next.

BlockDAG has finalized a new structure that allows the USDT Buyback to move forward under updated requirements. The previous buyback price was $0.02. For the next 7 days, that price has been raised to $0.03, and every eligible BDAG purchase made during this window builds toward that buyback rate. The path is: buy direct BDAG at $0.00000017, accumulate eligible Legacy BDAG and New BDAG, and let the dashboard calculate your USDT Buyback Balance automatically. Eligible BDAG goes through compression to a final eligible Buyback Allocation, priced at $0.03. One balance. Everything in one place.

At $500 invested at the current direct price of $0.00000017, a buyer receives approximately 294 billion BDAG. The dashboard then shows what that allocation is worth in USDT Buyback terms at $0.03. The math is not hidden. It is the first thing visible when you open the dashboard.

The previous eligible Buyback amount is already back in every verified holder’s USDT Buyback Balance. Legacy BDAG and New BDAG are consolidated under a single figure, no separate calculations, no split positions. USDT Buyback settlements will be processed in batches under the updated regulatory and compliance structure, with additional processing time required as each batch is completed.

The best crypto to buy today is rarely the one with the most complex pitch. Here, the path is four steps on your screen: buy BDAG, build allocation, get $0.03 buyback price, check balance. The 7-day window decides how much time you have to take it.

Zcash (ZEC): European ETP and ETF Split Expand Institutional Access

Zcash is holding above $1,506 as of September 22–23, 2026, up 3.1% in 24 hours, per CoinMarketCap data. The token’s institutional infrastructure expanded on two fronts this week. 21Shares launched a physically backed Zcash Exchange Traded Product on Euronext Amsterdam and Paris, opening regulated access to ZEC for European investors through standard brokerage accounts.

Separately, Grayscale announced a 3-for-1 forward split on its Zcash Trust ETF, effective September 30, following inflows exceeding $233 million, the split lowers the share price to improve retail accessibility without changing the underlying fund value.

Analyst targets for ZEC sit in the $1,770–$1,884 range, with the Cypherpunk Technologies board appointment of mining veteran Amanda Fabiano adding an infrastructure signal to the narrative. ZEC’s combination of ETF inflows, a new European ETP, and a quantum-proof protocol upgrade scheduled for November 2026 keeps it in the what crypto to buy now conversation for investors focused on privacy assets with institutional backing.

Hyperliquid (HYPE): $429M in Protocol Revenue and a New Layer 2 in Testing

Hyperliquid reached $97.46 on September 22–23, 2026, up 3.37% in 24 hours, per CoinMarketCap data, with social dominance hitting its highest point of 2026. The number that underpins the price is $429 million, on-chain protocol revenue generated through mid-September, outpacing every other crypto protocol by a measurable margin. That is recorded output, not a projection.

The new development this week is the Kinetiq Elysium testnet launch, a Layer 2 built on Hyperliquid targeting 300 million gas per second, with HYPE as the native gas token. HYPE-specific ETFs attracted $2.82 million in net inflows, primarily into the 21Shares THYP fund. A protocol generating $429 million in revenue while simultaneously launching Layer 2 infrastructure and pulling ETF inflows is doing three things at once that most tokens never manage individually.

Last Say

Zcash is stacking institutional access on two continents, a European ETP, a Grayscale ETF split, a quantum upgrade in November, and holding $1,506 while it does it. Hyperliquid has $429 million in real protocol revenue, a Layer 2 in testing, and $97 as the current floor.

BlockDAG is doing something neither of them is: raising its USDT Buyback Price from $0.02 to $0.03 for a 7-day window, with direct BDAG at $0.00000017 and a unified balance that covers Legacy and New BDAG automatically on your dashboard. What crypto to buy now is a question with strong answers across all three this week. The one with a 1.5x buyback uplift and a 7-day countdown is the one that requires a decision before the others do.


Presale: https://purchase.blockdag.network

Website: https://blockdag.network

Telegram: https://t.me/blockDAGnetworkOfficial

Discord: https://discord.gg/Q7BxghMVyu

Vintage Family Photo Prompts for a Natural Film Look

0

A convincing vintage family portrait begins with how the people relate to one another. The faded colors can come later. For an imagined family scene, an AI image generator lets you describe a shared glance, familiar clothing, and the light across a porch or living room. Those choices give the picture its character before you add a film-like finish.

Natural Expressions Start With a Shared Moment

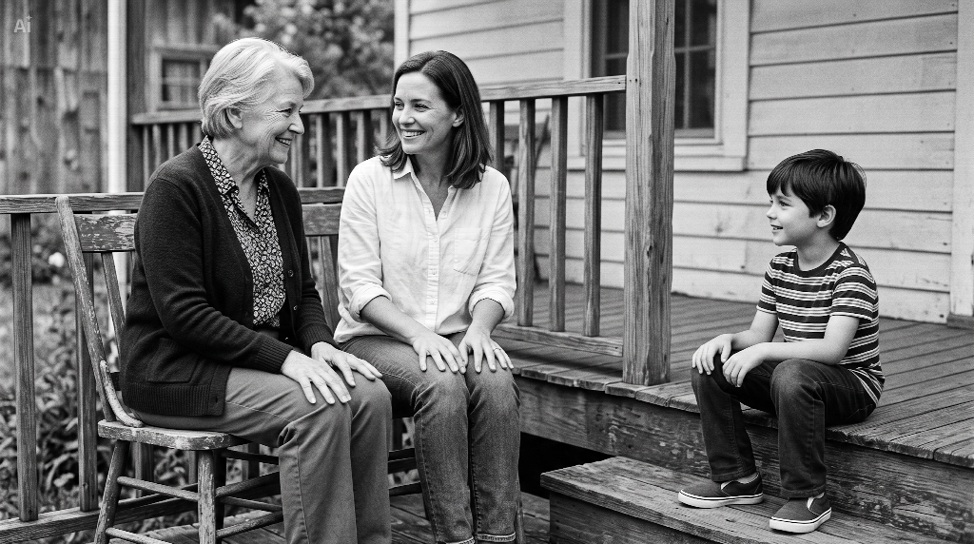
In the porch portrait, the adults exchange a smile while the child looks toward them. Their different lines of sight make the group feel connected without requiring everyone to face the camera. The setting is modest enough to remain part of the moment rather than competing with it.

Write the relationship into the action. “A grandmother and her adult daughter share a quiet smile as a child listens” is more useful than “a happy family.” It establishes who is responding to whom. You can also choose a more reserved moment, such as siblings sitting close together and looking toward someone outside the frame.

Specify the number of people and where each sits or stands. With three subjects, placing the child slightly lower can create a readable arrangement of faces. Keep the hands in simple positions on laps or knees, especially when several bodies overlap. Avoid giving every person a separate activity that needs its own set of props.

A Few Period Details Are Enough

Choose a broad period before describing clothing and surroundings. For an understated 1980s-inspired portrait, plain cotton shirts, a knit cardigan, and a weathered porch can establish the direction without turning the family into costume characters. Use differences in fabric and tone to distinguish people while keeping their outfits plausible together.

The background should agree with that choice. A modern phone in someone’s hand can interrupt the intended period more quickly than subtle grain can establish it. Ask for a simple setting with only the details you need. You do not have to fill the frame with recognizable vintage objects.

Be equally selective about aging effects. Heavy scratches, torn borders, and strong yellowing describe the condition of a damaged print. If the goal is a natural family photograph, begin with an intact image and restrained texture. The expressions should remain easier to see than the effect applied over them.

One Prompt for a Relaxed Porch Portrait

Open CapCut’s AI image generator and use a complete scene description rather than entering only “vintage family photo.” CapCut supports creating images from text, so an invented group is a straightforward starting point. Describe the people first, then their arrangement and the photographic treatment.

Create a horizontal, photorealistic black-and-white family portrait with a subtle 1980s film-photo feeling. Show exactly three fictional people on a covered wooden porch: a silver-haired grandmother in a dark cardigan, her adult daughter in a light cotton blouse, and a young boy in a striped shirt seated on a lower step. The adults exchange a relaxed smile while the boy looks toward them. Keep all faces visible, with natural age differences and hands resting separately on their own knees. Include weathered boards and plain house siding. Use soft open-shade daylight, gentle highlights, clear midtones, and fine grain. Keep skin texture natural. No additional people, pets, modern devices, lettering, scratches, or decorative border.

The clothing contrast has a practical role in this monochrome version. A light blouse separates the daughter from the darker cardigan beside her. If two people blend together, change one garment’s tone before asking for stronger contrast across the entire picture.

Warm Color Changes the Feeling of the Room

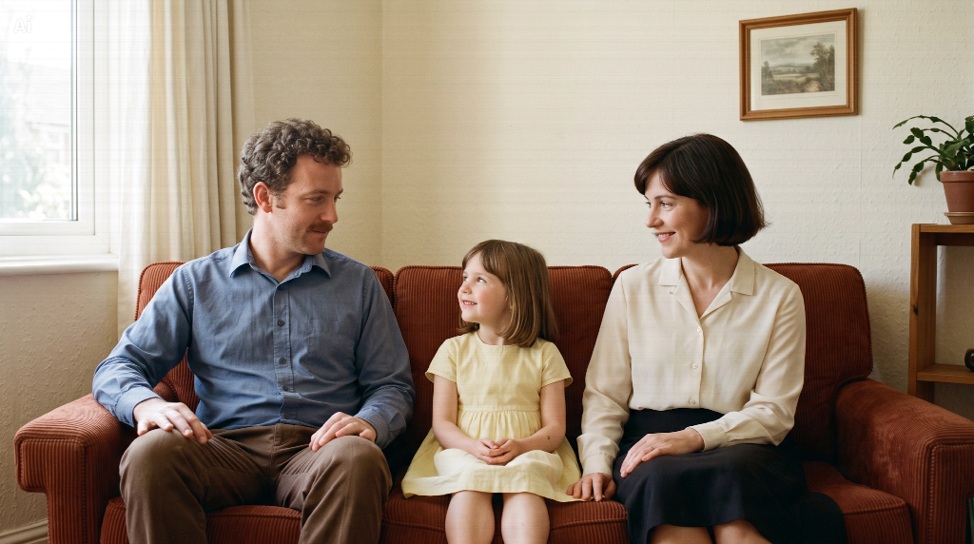
A muted color version can draw attention to the home as well as the faces. A rust-colored sofa and softly colored clothes give the room warmth, while a side window keeps the lighting connected to a visible part of the setting. The family still needs a shared moment; color alone cannot supply that interaction.

To explore this direction, replace the porch description with a simple living room and choose a quiet exchange on the sofa. Ask for warm, restrained colors with believable skin tones. Keep the shadows neutral enough that dark hair and clothing remain distinct. Avoid requesting an orange cast over the whole image.

Use this adaptation for the tone and setting: “An early-1980s-inspired living room with a rust-colored fabric sofa. Two parents sit with their child between them, exchanging relaxed glances. Soft daylight enters from a side window. Use muted warm colors, gentle contrast, and fine film-like grain, with clear facial features and no distressed-print effects.”

This is a separate imagined family scene, so you can change the people and their arrangement along with the room. If you instead want to work from your own family photograph, use a reference you have permission to upload and specify which expressions and relationships you want to retain.

A Shared Laugh Can Replace a Formal Pose

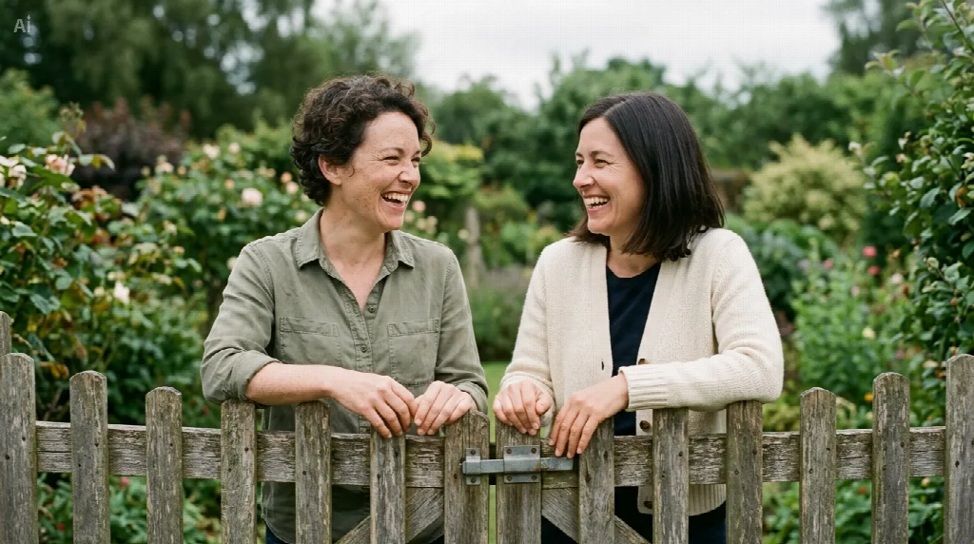
A portrait of adult siblings can feel familiar without including a whole household. Here, two imagined sisters lean on a garden gate and laugh toward each other. Their faces, shoulders, and resting hands belong to the same small exchange. The fence gives their arms a natural place to settle, while the softened foliage keeps attention on the expressions.

This is a different kind of moment from the quieter porch and sofa scenes. Describe the instant during the laugh, not a sequence of talking, turning, and laughing. Let the two expressions differ slightly; matching smiles and identical head angles can make an otherwise informal arrangement feel posed.

To try a late-1970s-inspired outdoor variation, specify two adult siblings beside a weathered gate, simple cotton and knit clothing, and soft overcast light. Ask for restrained color and faint grain rather than a yellowed finish. Keep their hands below their faces so the eyes and mouths remain unobstructed. You can suggest closeness through inward-facing shoulders and shared attention without adding an embrace or extra objects.

Film Grain Should Not Hide Facial Details

When reviewing a result from an AI photo generator, first look at the group from normal reading distance. Can you follow who is looking at whom? Are the ages, seated heights, and body positions believable? Then enlarge the faces and hands. Texture should not hide those details.

For a focused adjustment in CapCut, describe the change in relation to the image: “Reduce the grain over the faces while keeping the soft monochrome tones,” or “Keep the warm sofa, but make the skin tones less orange.” Inspect the revised result before changing anything else. Download the version whose expressions still feel natural when the image is viewed small.

Summary

Vintage family portraits feel personal when the interaction is clear and the period details stay understated. Start an imagined scene with CapCut’s AI image generator, then choose soft monochrome or restrained warm color. Keep the film texture subtle enough for the family to remain the focus.

China Leans on Banks To Shield Vanke From Default As Property Crisis Deepens

0
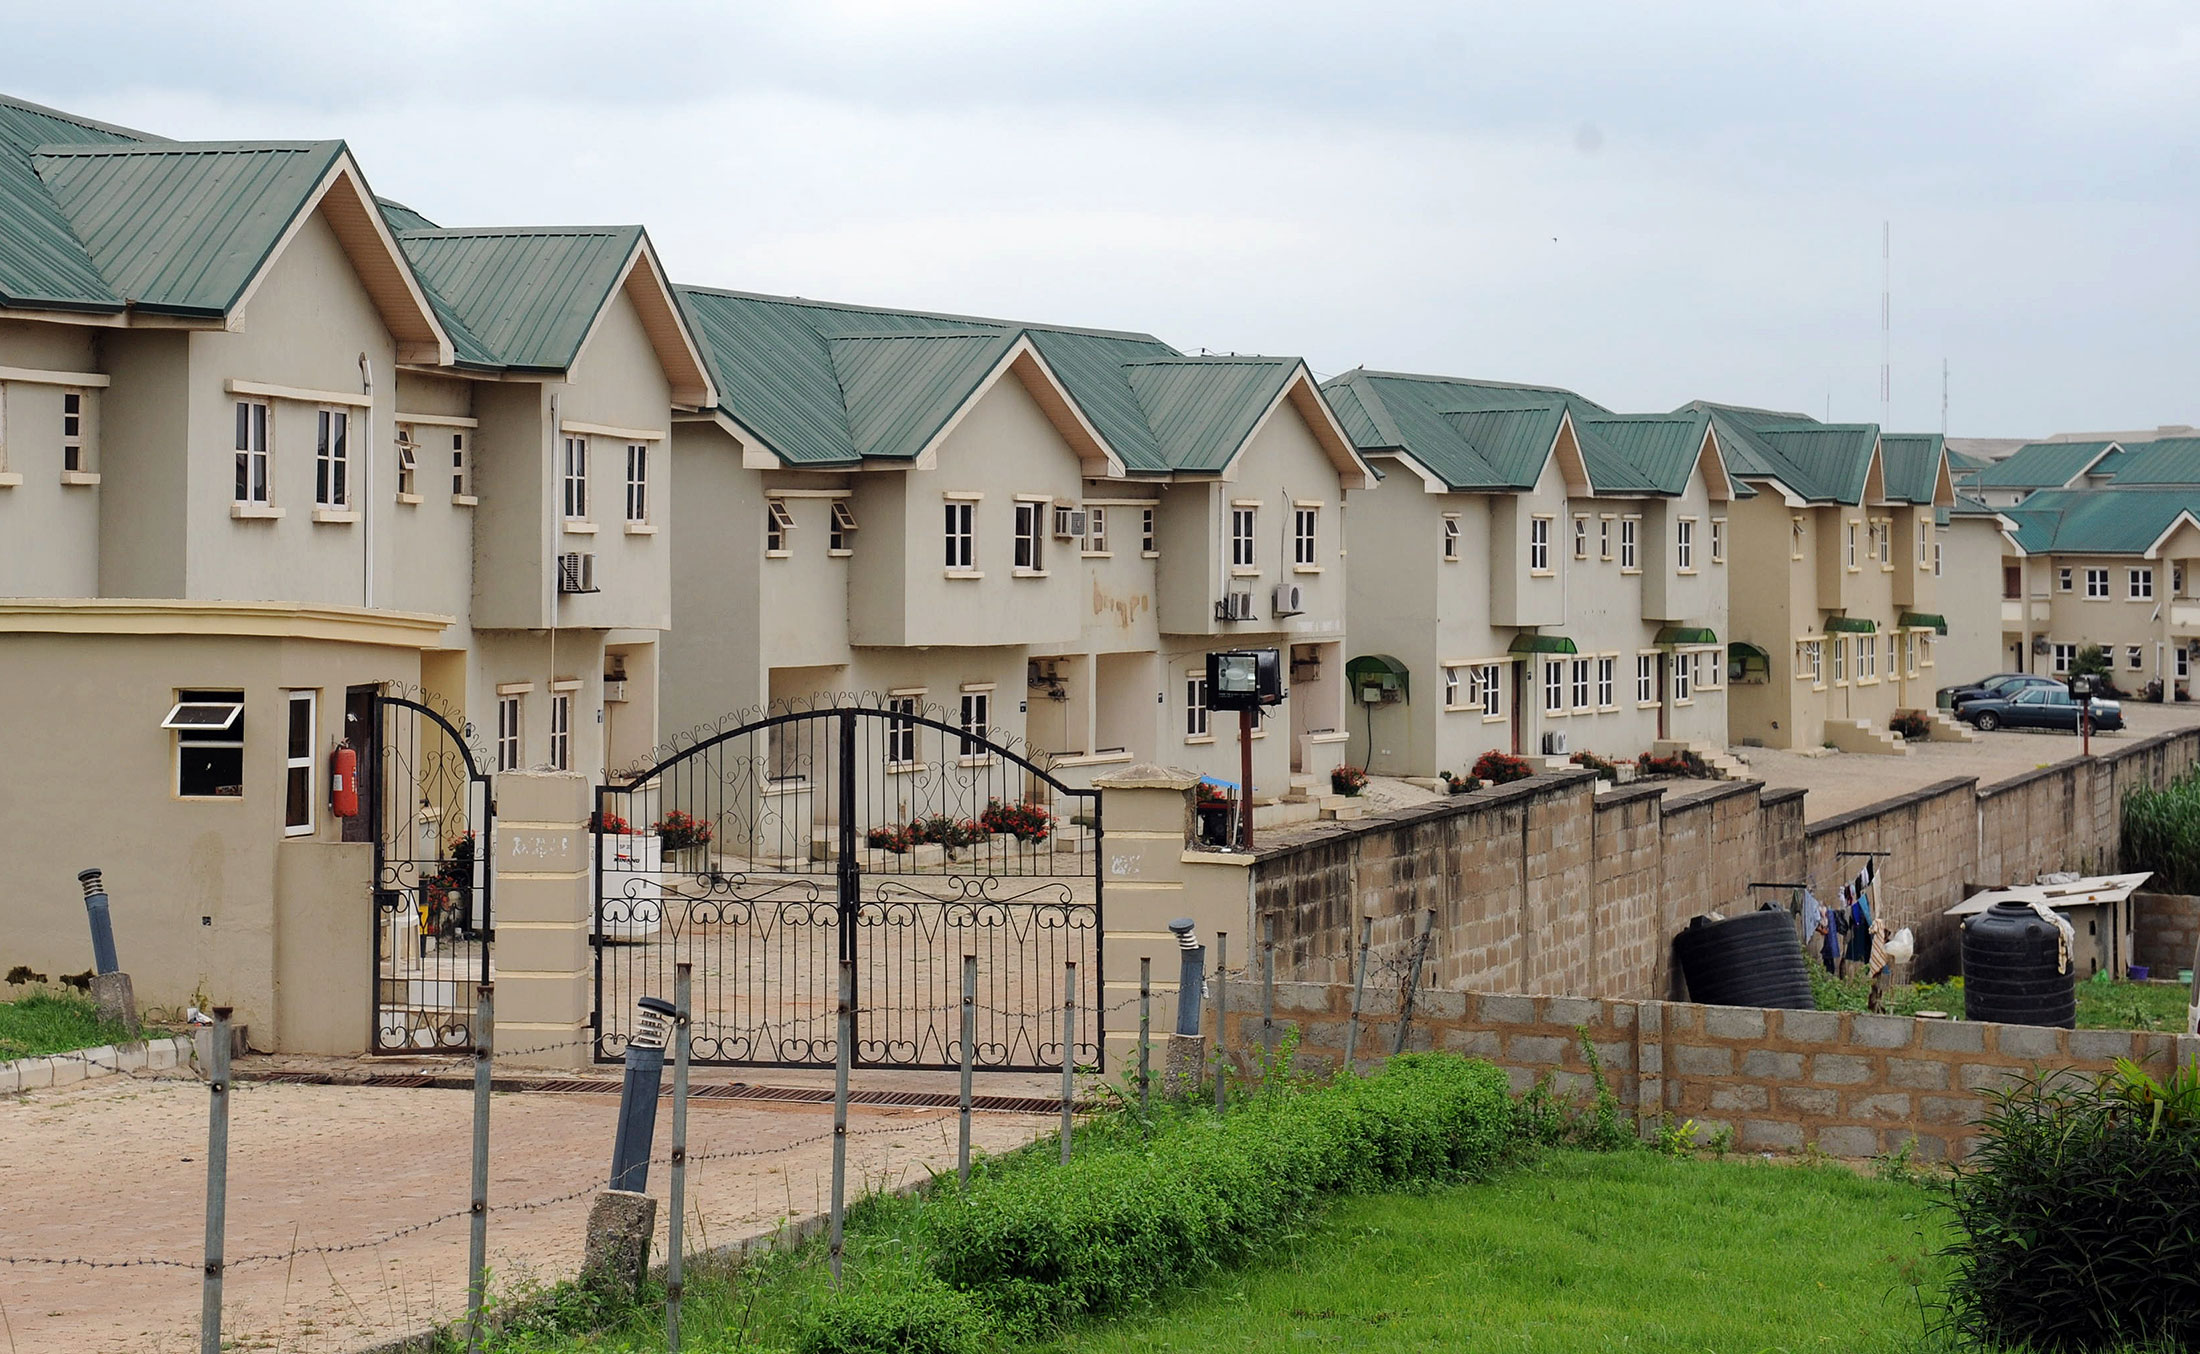
A detached three-bedroom apartments are pictured at Haggai Estate, Redeption Camp on Lagos Ibadan highway in Ogun State, southwest Nigeria on August, 30, 2012. The high cost of living and the massive urbanization of Lagos, the largest city and the economic capital of Nigeria, has engineered a migration of residents mostly middle class and the poor to neighbouring towns in Ogun State, both in southwest part of the country in search of cheap accommodations. Estate developers are quick in exploiting the high cost and scarcity of accommodation leading to emerging new towns, modern estates to accommodate the spillover in Lagos. AFP PHOTO/PIUS UTOMI EKPEI (Photo credit should read PIUS UTOMI EKPEI/AFP/GettyImages)

Chinese financial regulators have asked some banks not to classify overdue loans to China Vanke as non-performing and to extend repayment deadlines for the state-backed developer, in one of Beijing’s strongest interventions yet to prevent a default that could further unsettle the country’s financial system.

People familiar with the matter told Reuters that regulators had issued informal “window guidance” to lenders, urging them to support Vanke and avoid actions that could intensify its cash squeeze. Some banks were also asked to defer collecting interest payments owed by the developer, although the sources did not specify the size of the waivers.

The guidance was directed mainly at larger banks, many of which are state-owned, according to the people who spoke on condition of anonymity because of the sensitivity of the discussions.

The regulators have not set a fixed period for how long Vanke’s overdue loans can remain outside the non-performing category. One source said the treatment would depend on conditions in China’s property market and further discussions with Vanke.

The intervention underscores the extent to which authorities are trying to prevent Vanke from becoming another major casualty of China’s prolonged property downturn. Rather than allowing missed payments to immediately translate into formal loan defaults and potentially force banks to recognize losses, the guidance gives lenders room to extend maturities and delay some collections while Vanke works through its liquidity problems.

The approach is considered necessary especially after Evergrande’s liquidation.

The approach also highlights the importance authorities attach to Vanke’s links to the state. The developer has total assets of close to 1 trillion yuan ($149.31 billion) and is one of the few major distressed developers to have avoided an official default throughout the property crisis.

Vanke has received financing support from Shenzhen Metro, its state-owned major shareholder, and has extended some yuan bond payments to avoid defaults. Banks had also agreed earlier this year to defer interest payments owed by the developer.

Record Losses Expose Vanke’s Worsening Finances

The pressure on Vanke has intensified as weak property sales continue to erode its ability to generate cash. The developer reported a record 88.6 billion yuan loss for 2025, reflecting the severity of the downturn in its core business. Its financial position deteriorated further in the first half of this year, when net loss widened to 14.95 billion yuan.

Revenue fell 33% from a year earlier to 70.2 billion yuan during the first six months, adding pressure to a balance sheet already carrying substantial debt.

At the end of June, Vanke reported total debt of 351 billion yuan. Bank loans accounted for 72% of that amount, while bonds represented 7%. The remaining 21% consisted of other borrowings, including loans from Shenzhen Metro, according to Vanke’s interim report released in August.

Shenzhen Metro provided Vanke with a 22 billion yuan credit facility last year and extended additional loans this year, giving the developer another source of liquidity as commercial financing conditions remain difficult.

The latest regulatory guidance effectively gives banks an incentive to keep working with Vanke rather than aggressively pursuing repayment at a time when the developer’s ability to raise cash is constrained.

For the banks, however, postponing recognition of non-performing loans does not eliminate the underlying credit risk. It instead gives Vanke more time to stabilize its finances and potentially benefit from an improvement in property-market conditions.

The approach is considered necessary because the guidance leaves the duration of the loan treatment open. If property sales fail to recover and Vanke remains unable to meet its obligations, banks could eventually face the same losses they are currently being asked to defer recognizing.

Vanke Becomes A Test of Beijing’s Property Rescue Efforts

China’s property sector has been under pressure for more than five years after a government campaign to curb excessive borrowing by developers triggered a broader liquidity crisis.

The sector was once one of the country’s most important engines of economic growth, supporting construction, employment, household wealth and demand across a wide range of industries. But home prices continue to fall, property investment remains weak, and efforts to establish a sustained recovery have so far struggled to gain traction.

Beijing has recently sought to curb presales of unfinished homes in an effort to restore confidence among buyers. Those measures have yet to produce a meaningful turnaround in home prices, leaving developers dependent on increasingly extensive financial and policy support.

Vanke is at the center of the issue because it has remained closely tied to the state while avoiding the formal defaults that have defined much of the property crisis. A disorderly failure by the developer could therefore carry implications beyond its own creditors, particularly if it weakened confidence in other developers, banks or state-linked companies.

That helps explain why regulators are focusing on preventing a “risk event” at Vanke, according to one source.

The immediate objective is not necessarily to erase Vanke’s liabilities but to prevent its liquidity problems from turning into a destabilizing event. By asking banks to extend loans, delay interest collection and postpone non-performing classifications, authorities are effectively buying time for the developer and the wider property market.

The longer-term question is whether that time can translate into a genuine recovery.

Vanke’s worsening losses, declining revenue and 351 billion yuan debt burden show that the company’s problem is not simply a temporary mismatch between payments and cash flow. Its underlying business remains exposed to a property market where sales and investment have yet to recover.

Therefore, the regulatory intervention offers Vanke another financial lifeline, but it also illustrates the increasingly difficult balance Beijing faces: preventing a major developer from defaulting without allowing temporary relief to substitute indefinitely for a recovery in the property market.