DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 10

Citrini Says Humanoid Robots Could Become AI’s Next Big Investment Trade As China Gains Ground

0

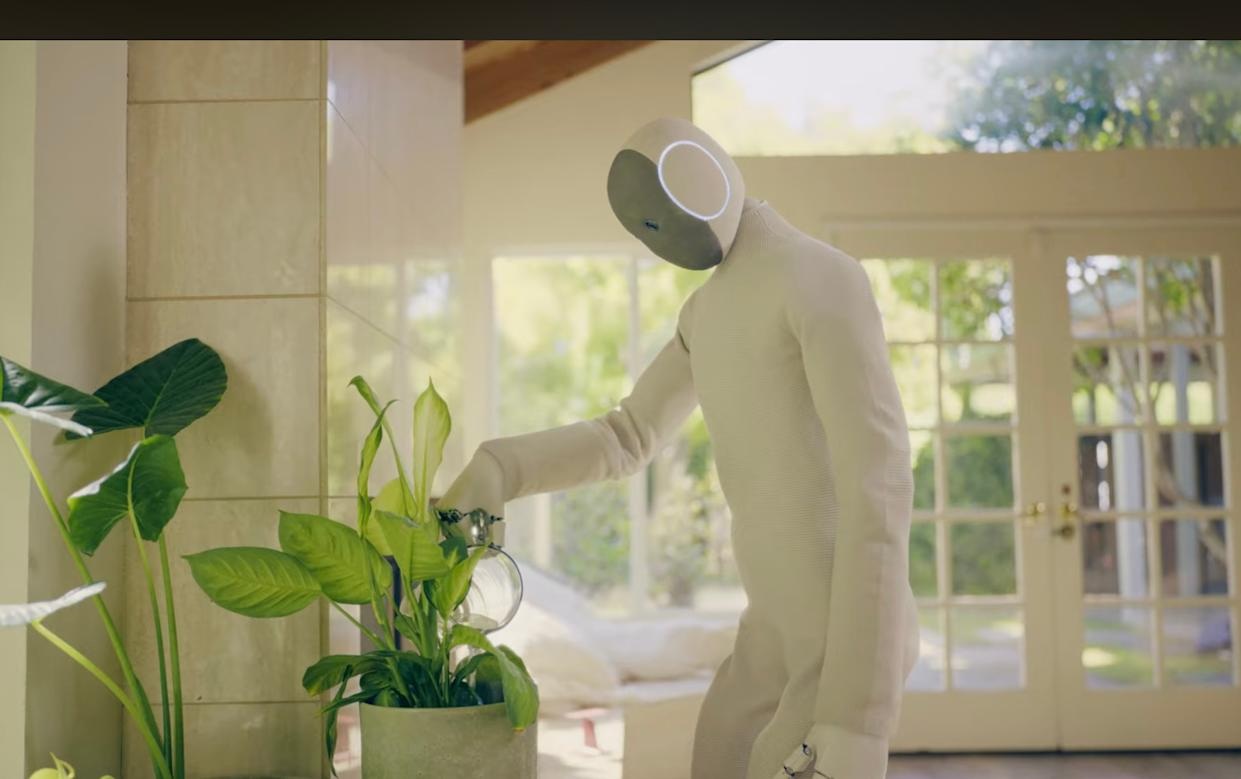
Citrini Research says AI-enabled robotics is emerging as a major investment trend that could extend the artificial intelligence boom beyond software and data centers, with China’s rapid progress in humanoid robots raising the prospect of a new technology race with the United States.

The research firm, which gained widespread attention for publishing a hypothetical AI-driven economic doomsday scenario, has developed a more bullish thesis around robotics, arguing that physical machines capable of using sophisticated AI systems could become the next growth phase of the AI trade.

Citrini pointed to the World Humanoid Robot Games, held in Beijing in August, as evidence of how quickly the technology is progressing and how China is using public competition to accelerate development.

“Humanoid Olympics may seem like an exercise in the absurd, but really are a top-down strategic effort to push the limits of hardware in a competitive, visible and verifiable setting,” Citrini wrote. “Sending a humanoid at full sprint into a crash wall is literally ‘moving fast and breaking things.’ Scoff at your own risk.”

The event is exposing another shift in the development of artificial intelligence. The first phase of the AI investment cycle was dominated by chips, cloud computing and large language models. The emerging phase is focused on putting those systems into machines that can operate in factories, warehouses, homes, and other physical environments.

The concept, described as “physical AI,” is already attracting technology companies and investors. Atom, the physical automation startup founded by Uber co-founder Travis Kalanick, is expanding rapidly, while UBS strategist Ulrike Hoffmann-Burchardi has highlighted robotics stocks as an area that could benefit from the continued expansion of the AI trade.

Citrini’s argument, however, goes beyond the size of the potential robotics market. The firm says US investors may be underestimating China’s position in the emerging industry.

The report acknowledged that the US could retain an advantage in software and AI decision-making systems, but argued that China has important strengths on the hardware side. Those strengths include a large manufacturing base and established supply chains that could become important if humanoid robots move from experimental prototypes to mass-market products.

That possibility has led Citrini to compare the emerging robotics industry with the electric vehicle market.

“It’s running the EV playbook, with the literal same players,” the firm wrote. “Tesla popularized the modern EV and Chinese companies like XPeng replicated.”

The comparison strengthened the message because the EV industry demonstrated how technological leadership and manufacturing dominance can evolve differently. Tesla helped popularize modern electric vehicles, but Chinese manufacturers subsequently expanded aggressively, competing on cost and production scale.

BYD has become one of the world’s largest electric vehicle manufacturers, while Chinese automakers have been challenging established global brands on pricing and production. The companies are now carrying that industrial competition into robotics.

In June 2026, BYD’s CEO disclosed plans to begin incorporating robots into every showroom to assist with car sales. XPeng has also expanded beyond electric vehicles with XPeng Iron, its own humanoid robot designed to compete with Tesla’s Optimus.

For Citrini, XPeng provides an example of how an established Chinese EV company could potentially use its existing manufacturing capabilities to participate in a future robotics market.

“XPeng is another EV company with a nascent arm but ~100x cheaper,” the author wrote. “I would bet Optimus is in a better position than Iron today, but just look at history. Xpeng’s EV business is rapidly expanding in part by taking share from Tesla.”

The firm is therefore not arguing that XPeng currently has a technological advantage over Tesla in humanoid robotics. Instead, its thesis is that today’s lead may not determine tomorrow’s market structure if robotics follows the same development pattern as electric vehicles.

That stance is of the essence because humanoid robotics is fundamentally a hardware business as well as an AI business. A company needs capable AI models, but it also needs motors, sensors, batteries, actuators, semiconductors, manufacturing capacity, and reliable supply chains. The ability to produce robots at scale and at a commercially viable cost could become as important as the intelligence of the systems controlling them.

Therefore, China’s existing industrial infrastructure is expected to become a significant factor if demand for humanoid robots accelerates.

But there are still substantial hurdles before the technology reaches that stage. Demonstrations and competitions can show that robots are becoming more capable, but commercial adoption will depend on whether machines can perform useful tasks reliably, safely, and at a cost that makes economic sense for businesses and consumers.

That has created a market with both significant potential and considerable uncertainty for investors. The current AI boom has been driven largely by spending on computing infrastructure and software. A successful transition into physical AI could create another layer of demand across robotics, industrial automation, semiconductors, batteries, and related manufacturing industries.

Citrini’s broader warning is that the beneficiaries may not be the same companies that dominate the current AI software race. If robotics becomes the next major application of artificial intelligence, the competitive advantage could shift toward companies that can combine advanced AI with low-cost, high-volume hardware production.

The EV industry provides a precedent for that shift. Tesla demonstrated the commercial potential of a new vehicle technology, while Chinese manufacturers later built substantial scale and competed aggressively on cost.

Citrini’s thesis is that humanoid robotics could follow a similar trajectory, making the emerging contest between US AI capabilities and China’s hardware and manufacturing base one of the important questions for the next stage of the AI economy.
EU Seeks Voluntary Chinese Curbs on Hybrid Car Exports to Avoid Trade War

0

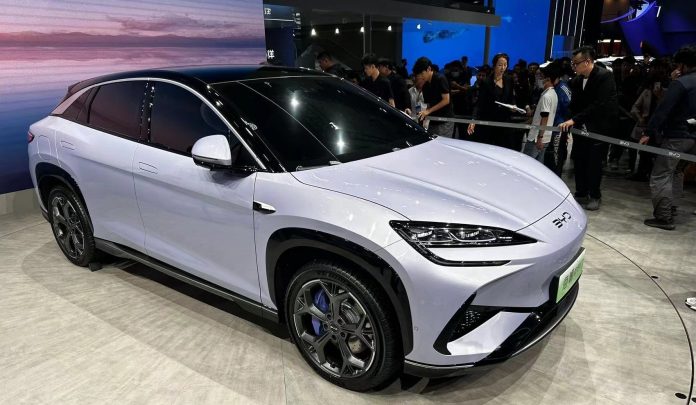
The European Union has asked China to voluntarily restrict exports of hybrid vehicles to the bloc as Brussels seeks to contain a widening trade imbalance with Beijing without triggering a broader trade war, the Financial Times reported on Thursday.

Under the proposal, China would limit sales of Chinese-made hybrid vehicles to roughly 15% of the European Union market, according to people familiar with the discussions cited by the newspaper.

The request marks a significant shift toward negotiated trade management as the EU confronts a surge in Chinese exports across several industrial sectors. Brussels is becoming more concerned that China’s manufacturing capacity is allowing Chinese companies to expand rapidly in European markets at a time when European manufacturers are struggling with weak demand, high costs and the transition to cleaner technologies.

“If they will not limit their exports to our market then we will,” the FT quoted an EU official as saying. “This is about stopping deindustrialisation. We have to act. It’s about managed trade.”

The proposal reportedly extends beyond automobiles. The EU has also asked China to consider limiting exports of other products, including chemicals, while seeking greater Chinese purchases of European goods as part of efforts to narrow the trade imbalance.

The approach would effectively seek to manage the two-way flow of goods rather than relying exclusively on tariffs or other unilateral trade restrictions.

Brussels Confronts a New “China Shock”

European Commission President Ursula von der Leyen sharpened the bloc’s criticism of China on Wednesday, telling the European Parliament that the EU would use every available tool to address what she described as an “unsustainable” trade deficit with Beijing.

The EU’s goods trade deficit with China reached €360.6 billion ($413.4 billion) last year, according to von der Leyen, and widened by 9% during the first six months of this year.

She described the deterioration as a tipping point and warned that Europe was experiencing a second “China shock” through deindustrialisation.

The language captures the central economic concern behind Brussels’ growing aggressive trade posture. European officials are not simply worried about individual Chinese products gaining market share. They are concerned that sustained import growth in sectors such as electric vehicles, batteries and chemicals could weaken domestic manufacturing capacity, investment and employment in industries considered important to Europe’s industrial base.

The hybrid-car proposal also highlights how quickly the trade dispute is expanding beyond electric vehicles.

China has become a major force in global electric and electrified vehicle manufacturing, supported by a large domestic market, extensive battery production and a dense industrial supply chain. European automakers have been competing with Chinese manufacturers while simultaneously investing heavily in the transition away from conventional internal-combustion vehicles.

The challenge for Brussels is to protect European industrial capacity without making European consumers bear the full cost through higher prices or provoking retaliatory measures from Beijing. That helps explain the attraction of a negotiated export ceiling. A voluntary limit could give European manufacturers more room in their domestic market while allowing China to avoid the escalation associated with unilateral EU restrictions.

But such an arrangement would also signal a departure from the EU’s traditional emphasis on open competition and market access. Managing import volumes through negotiated quotas risks creating a more controlled trading relationship in which governments, rather than market forces alone, determine how much foreign production can enter key industries.

China Rejects Overcapacity Accusations

European officials say the surge in Chinese exports of vehicles, batteries, chemicals and other manufactured products is being driven in part by excess industrial capacity in China.

Beijing rejects that characterization, saying that Western concerns over Chinese overcapacity and economic imbalances are protectionist measures designed to restrict China’s industrial development.

That disagreement is at the heart of the broader EU-China trade dispute.

From China’s perspective, companies that have invested heavily in manufacturing and developed competitive supply chains should be able to sell those products abroad. From the European perspective, the rapid expansion of Chinese exports can become destabilizing when production capacity grows faster than domestic demand and the resulting surplus is directed toward foreign markets.

The dispute has become complicated because Europe’s trade deficit with China is not limited to consumer goods. Chinese companies increasingly compete in industrial technologies that Europe has historically regarded as areas of manufacturing strength.

The EU is therefore seeking a combination of measures. Alongside proposed export restraints, Brussels wants China to purchase more European products, potentially providing European companies with greater access to the Chinese market and helping reduce the imbalance from both sides of the trade equation.

European Trade Commissioner Maros Sefcovic is leading talks with China and has said he wants tangible results by October. He is expected to visit China by early next month. The timetable adds urgency to the negotiations. If talks fail to produce concessions, the EU could move toward more aggressive trade measures, increasing the risk of retaliation from Beijing.

That possibility is sensitive for European companies with substantial exposure to China. A confrontation could affect not only automakers but also industrial machinery, luxury goods, chemicals and other exporters that depend on the Chinese market.

For China, accepting voluntary limits could reduce the immediate threat of additional European restrictions, but it could also establish a precedent for other trading partners seeking similar concessions.

The proposal therefore sits at the intersection of two competing objectives. Brussels wants to prevent the loss of European industrial capacity while avoiding a damaging trade war. Beijing wants to preserve access to overseas markets without accepting the premise that its manufacturing strength is the result of unfair overcapacity.

The outcome could determine whether the EU-China relationship moves toward negotiated trade management or a more confrontational cycle of tariffs, quotas and retaliation.

Coinbase One Raises USDC Rewards to 3.75% APY as the New Battle for Stablecoin Capital Intensify 

0

Coinbase’s decision to lift the USDC rewards available to Coinbase One members to 3.75% APY is more than a modest adjustment to a savings-like product. It is another signal that the competition for stablecoin capital is moving beyond transaction fees and trading features and toward the economics of simply holding digital dollars.

At first glance, 3.75% may appear unremarkable in an environment where investors can find higher yields across parts of the crypto market. But USDC is not marketed as a speculative token.

Its appeal is its dollar denomination and its role as settlement infrastructure across exchanges, payments, decentralized finance and increasingly institutional markets. Offering a yield on that liquidity therefore changes the proposition.

Users can potentially earn a return while retaining exposure to a dollar-denominated digital asset. The significance becomes clearer when viewed through Coinbase’s broader business model. Coinbase has increasingly positioned itself as financial infrastructure rather than merely a place to buy and sell cryptocurrencies.

Its exchange, custody operations, institutional services and stablecoin ecosystem all depend on keeping users and capital inside its network. USDC is particularly important because Coinbase is a major participant in its ecosystem and has an economic relationship with its issuer, Circle.

Rewards can strengthen that relationship by giving users another reason to maintain balances on the platform. A customer who might otherwise move idle dollars elsewhere now has an incentive to keep USDC within Coinbase. At scale, relatively small changes in yield can influence substantial pools of liquidity.

The move illustrates the changing role of stablecoins in crypto. They were initially viewed primarily as trading instruments—digital representations of dollars used to move quickly between exchanges and blockchain applications. Their function is expanding.

Stablecoins are increasingly being treated as programmable cash, capable of moving across borders, settling transactions continuously and connecting traditional financial assets with blockchain-based markets.

That evolution creates a competitive question: who captures the economic value generated by stablecoin liquidity? Exchanges, issuers, fintech companies, payment providers and decentralized protocols are all competing for the same pool of dollar-denominated capital.

Rewards are one mechanism for attracting it. The more stablecoins become embedded in payments and financial markets, the more valuable persistent liquidity becomes. There is, however, an important distinction between a stablecoin reward and a traditional bank savings account.

The 3.75% APY should not automatically be interpreted as equivalent to a federally insured deposit rate. Users should examine eligibility requirements, subscription costs, applicable limits, geographic availability and the precise terms governing rewards. The underlying USDC also remains a crypto asset rather than a bank deposit.

For consumers, the calculation is therefore not simply about the headline percentage. The relevant question is the net economic benefit after membership costs and other conditions, alongside the risks associated with holding stablecoins on a crypto platform.

Coinbase’s higher USDC reward reflects a larger transformation underway in digital finance. Stablecoins are becoming increasingly important pools of liquidity, and platforms are discovering that controlling those balances can be as strategically important as controlling trading volume.

The 3.75% figure matters not merely because it offers another yield opportunity, but because it demonstrates how the competition for digital dollars is becoming a central battleground in the next phase of crypto infrastructure.

Salesforce Dreamforce 2026: AI Agents, AIforce and the Future of Enterprise Software

Salesforce’s Dreamforce 2026 has turned San Francisco into a focal point for the enterprise technology industry, with the company using its annual conference to demonstrate how artificial intelligence is reshaping customer relationship management, business software and corporate workflows.

Running from September 15 to 17 at the Moscone Center, the event brings together customers, developers, investors and technology partners around Salesforce’s vision of the “Agentic Enterprise.”

The significance of Dreamforce extends beyond product launches.

Salesforce has increasingly positioned artificial intelligence as the next major growth engine for its software business, and investors are watching the conference for evidence that its AI strategy can translate into adoption, recurring revenue and stronger customer engagement.

One of the major announcements is AIforce, a new interface layer designed to allow people and AI agents to access Salesforce data, workflows, business logic, permissions and governance from different AI interfaces.

Rather than requiring users to remain inside a traditional Salesforce interface, the company says AIforce can bring Salesforce capabilities to wherever work is taking place. That strategy reflects a broader change taking place across enterprise software.

Traditional applications were designed around humans clicking through dashboards and menus. Agentic AI introduces a different model, in which software agents can reason, execute tasks and interact with multiple systems.

Salesforce is therefore attempting to ensure that its platform remains relevant even as the interface between workers and software changes.

Agentforce remains central to that strategy. Salesforce has expanded the platform with AI agents designed for high-value business functions, including sales, service, commerce and workforce operations.

The company says these agents are being developed to handle increasingly complex work, pursue objectives over longer periods and collaborate with other agents. Partnerships are another important theme at Dreamforce.

Salesforce and Google Cloud announced an expanded strategic relationship intended to connect their respective AI and data ecosystems. Salesforce workloads can run on Google Cloud infrastructure through Hyperforce.

While agents across Salesforce and Google Cloud can reason over shared data without requiring traditional custom integrations. For the broader technology sector, this illustrates the emerging competition to establish the infrastructure layer for enterprise AI.

Salesforce is competing not only with conventional CRM providers but also with cloud platforms, foundation-model companies and specialized AI startups. Its ability to integrate these technologies while maintaining security, governance and enterprise data controls could become an important differentiator.

The financial dimension is equally important. Salesforce specifically scheduled an investor and analyst session during Dreamforce to discuss its latest innovations and financial framework, signaling that product announcements are being viewed alongside questions about long-term growth and monetization.

Yet the conference has highlighted the practical risks of operating increasingly critical enterprise infrastructure. On September 16, Salesforce experienced a widespread service disruption affecting customers during the conference, underscoring how dependent businesses have become on cloud software availability.

Dreamforce 2026 therefore represents more than another technology conference. It is a real-time demonstration of Salesforce’s attempt to redefine CRM around autonomous and collaborative AI agents.

The announcements emerging from San Francisco will be closely watched because they offer investors and enterprise customers a clearer view of how Salesforce intends to compete as AI transforms the architecture of corporate software.

WLFI Governance Rewards and STANDARD Token Surpasses $40M Market Cap on Robinhood

0

The latest developments around World Liberty Financial and The Standard Reserve point to two different experiments in how crypto protocols can turn participation and capital allocation into core components of token economics.

One is focused on governance, seeking to reward holders who actively lock tokens and vote. The other is building an on-chain reserve system whose token has quickly attracted market attention following its launch on Robinhood Chain.

World Liberty Financial has published a governance proposal for a $WLFI Governance Engagement Incentive Program, with a proposed launch date of October 1, 2026.

Under the plan, holders of unlocked WLFI could lock their tokens for at least 180 days through a non-custodial on-chain protocol and become eligible for rewards if they directly participate in governance. Holders would need to vote on at least one ecosystem proposal during every 90-day period in which their tokens remain locked.

The structure is notable because it separates passive ownership from active governance participation. Simply holding or staking WLFI would not qualify a participant for promotional allocations. Instead, rewards would depend on verified voting activity.

The amount of WLFI participating in the program, the available rewards pool and other protocol parameters. Delegated votes would also not satisfy the direct-voting requirement.

WLFI says the rewards pool could receive funding from ecosystem sources, potentially including treasury resources and fees from World Liberty Markets, with additional allocations and bi-weekly top-ups.

The proposed system would make the funding and distributions publicly observable through an on-chain rewards address. That transparency could allow participants to monitor how much capital enters the program and how rewards are distributed.

The proposal therefore treats governance as an economic activity rather than simply an administrative function. Locking tokens reduces their immediate liquidity while voting creates a recurring participation requirement.

In theory, this gives the protocol a mechanism for encouraging longer-term engagement while creating a measurable connection between governance activity and incentives.

At the same time, The Standard Reserve has emerged with a different approach to crypto-native finance. The project describes itself as an on-chain reserve system, with its monetary mechanics linked to net capital flows in its ETH/STANDARD market.

Earlier research described a model in which positive ETH flows can expand issuance, while negative flows can reduce issuance and direct the system toward STANDARD buybacks and burns.

Following its launch on Robinhood Chain, STANDARD quickly moved above a $40 million market capitalization. GeckoTerminal data showed the token around $40.6 million in market capitalization, with approximately 6,100 holders and roughly $5.4 million in liquidity at the time of reporting.

The same data also showed the market was only hours old, underscoring how quickly the token’s valuation had formed after launch.  The architecture is built around more than the token itself.

The Standard Reserve incorporates Genesis Charters and branches into its economic design, with the broader mechanism attempting to connect issuance, reserve accumulation, participation and exit dynamics. Its stated objective is to make capital flows part of monetary policy rather than relying solely on fixed emissions.

WLFI and STANDARD illustrate a broader evolution in decentralized finance: tokens are increasingly being designed not merely as tradable assets, but as mechanisms coordinating governance, liquidity, incentives and participation.

The critical question for both systems is whether these mechanisms can sustain genuine economic activity after the initial attention surrounding their launches fades. For WLFI, that means converting token holders into consistent voters.

For STANDARD, it means demonstrating that its reserve and issuance model can withstand real buying, selling and withdrawals over time.

Anthropic, AI Safety and the Geopolitics of the Global Artificial Intelligence Race

0

The debate over artificial intelligence is entering a more consequential phase. What began as a contest over computing power, model performance and venture capital is increasingly becoming a struggle over regulation, national security and technological sovereignty.

Anthropic’s warnings about the risks posed by increasingly capable AI systems have intensified that debate, but a new analysis raises an important caution.

Genuine concerns about AI safety should not become a justification for entrenching America’s leading laboratories or deepening technological confrontation with China.

The distinction matters because AI safety is both a technical problem and a geopolitical one. If governments respond to frontier-model risks by concentrating access to advanced chips, computing infrastructure, talent and research within a small group of US companies.

They could reduce certain risks while simultaneously creating a more concentrated technological order. Such concentration may give established laboratories greater influence over the rules governing an industry that is becoming critical to economies and governments worldwide.

Anthropic has been among the companies publicly warning that frontier AI could eventually generate risks that existing institutions are poorly equipped to manage. Those warnings deserve serious consideration.

Particularly as AI systems become capable of operating with greater autonomy, using tools and interacting with complex digital environments. But the policy response must distinguish between legitimate safety measures and policies that primarily protect incumbents from competition.

This is where Sebastian Mallaby’s discussion of AI regulation becomes significant. The author of The Infinity Machine has examined how technological revolutions can reshape economic power, financial markets and institutions.

The emerging AI transition presents a similar challenge: regulation must become strong enough to manage systemic risks without becoming so restrictive that it suppresses experimentation, competition and technological diffusion.

For Europe, the question is particularly difficult. The continent does not possess the same concentration of frontier AI laboratories or hyperscale computing capacity as the United States.

Nor does it occupy China’s position as a major state-backed technological competitor. Yet Europe holds other cards: regulatory influence, industrial expertise, large consumer markets, research institutions and the ability to establish standards that companies must follow if they want access to European customers.

The European Union’s AI regulatory framework demonstrates how that influence can operate. Rather than attempting to dominate the frontier-model race purely through scale, Europe can shape the conditions under which AI is deployed.

Requirements surrounding transparency, risk management, accountability and data governance could become commercially important if global companies design products around European standards.

But regulation alone will not secure Europe’s technological position. Excessive compliance costs could discourage startups and push investment elsewhere, while insufficient investment in computing infrastructure could leave European researchers dependent on foreign platforms.

Europe therefore faces a dual challenge: regulate powerful AI systems while simultaneously building enough domestic capability to remain strategically relevant.

The same tension applies to the US-China relationship. Treating AI exclusively as a national-security competition risks transforming safety policy into another mechanism of technological decoupling.

Yet ignoring geopolitical competition would also be unrealistic. Advanced AI has implications for economic productivity, cybersecurity, military capabilities and scientific research. The central challenge is therefore institutional rather than merely technological.

Governments need mechanisms capable of monitoring frontier systems, responding to demonstrable risks and coordinating internationally without allowing safety concerns to become a blanket argument for market concentration.

AI regulation will be judged not only by how effectively it prevents dangerous outcomes, but also by whether it preserves competition, innovation and international cooperation. The future of AI should not be determined solely by whichever laboratories build the most powerful models first.

It will also depend on whether governments can construct rules that make technological power accountable without turning legitimate safety concerns into instruments of geopolitical escalation.

How Geopolitics, Bond Markets, AI and Infrastructure Are Reshaping Business

The global economy is not simply experiencing another cycle of uncertainty. It is undergoing a repricing of what businesses consider valuable.

For decades, globalization rewarded companies that could produce more cheaply, borrow more cheaply and operate with remarkably lean supply chains.

That model is being challenged by war, volatile capital markets, energy insecurity and the rapid construction of artificial-intelligence infrastructure. The emerging economic argument is distinctive: resilience is becoming an economic asset, not merely a defensive expense.

Geopolitical conflict has exposed the hidden cost of efficiency. A supply chain designed around the cheapest supplier can become extraordinarily expensive when shipping lanes are disrupted, sanctions are imposed or critical components become unavailable.

Companies are consequently accepting higher short-term costs to gain greater control over production and sourcing. Factories are being diversified, suppliers are being duplicated and strategic inventories are being reconsidered.

This represents a fundamental change in corporate economics. Redundancy was once treated largely as waste. Increasingly, it is being treated as insurance. A second supplier, a domestic production facility or a larger inventory may reduce margins in normal conditions while protecting revenues during a crisis.

The question facing executives is therefore changing from “How cheaply can we operate?” to “What level of disruption can our business absorb?” Energy illustrates the same transformation.

Oil-price volatility and geopolitical tensions have made energy security an increasingly important component of industrial strategy.

Companies cannot easily separate production costs from global political developments when fuel, electricity and transportation are exposed to international shocks.

This is helping strengthen the economic case for alternative energy sources, efficient infrastructure and long-term power agreements. Bond markets are revealing another side of the adjustment.

Governments and corporations are operating in an environment where capital cannot be assumed to remain permanently cheap. Elevated borrowing needs, inflation uncertainty and changing expectations about monetary policy can push long-term yields higher even when economic growth remains subdued.

That creates a more demanding environment for investment: projects must generate convincing returns rather than depending on inexpensive financing to make the numbers work.

Artificial intelligence complicates the picture because it is simultaneously a technology revolution and an infrastructure boom. The enormous investment required for data centers, chips, electricity generation and networks represents a bet that future productivity will justify today’s capital expenditure.

The crucial economic question is therefore not whether AI is transformative, but whether its productivity gains will become large and widespread enough to support the valuation of the infrastructure being built around it. This distinction matters.

An economy can experience an investment boom without immediately experiencing a productivity boom. If AI substantially increases output per worker, it could support faster growth while easing some cost pressures.

If adoption remains concentrated in a limited number of highly profitable companies, the benefits may be less broadly distributed. Infrastructure itself is consequently becoming a strategic economic variable.

Electricity grids, semiconductor capacity, ports, telecommunications and digital networks are increasingly viewed not simply as background utilities but as productive assets that determine how quickly economies can respond to technological and geopolitical change.

Meanwhile, consumers remain the test. Higher financing costs and persistent price pressures can eventually weaken household demand, forcing companies to confront slower revenue growth alongside higher operating and capital costs.

The defining economic story, then, is not merely disruption. It is repricing. The world is placing a higher value on security, flexibility, reliable energy, technological capacity and strong balance sheets.

Companies that once competed primarily through efficiency are increasingly competing through their ability to remain operational when efficiency alone is no longer enough.

The next phase of globalization may therefore be less about minimizing every cost and more about determining which costs are worth paying to preserve economic control.