DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 3

Nigeria’s Rate Reset Tests Whether Foreign Capital Can Stay as the Carry Cushion Narrows.

0

by EBC Financial Group?? 

Heavy demand for one-year Treasury bills at the first post-cut auction suggests appetite for longer-dated naira assets remains strong, but lower Nigerian yields and higher US rates are narrowing the cushion available to investors.

LAGOS, 29 September – Nigeria’s first Treasury-bill auction following the Central Bank of Nigeria’s 350 basis point reset of its Monetary Policy Rate from 26.5% to 23% has shifted the market debate beyond the size of the cut. The question is whether foreign and domestic demand for naira assets can remain resilient as returns on short-dated government securities narrow both domestically and relative to dollar assets. The CBN set the Monetary Policy Rate at 23%, at its 21 to 22 September meeting. It also recalibrated the Standing Facilities Corridor to +50/-300 basis points around the MPR. The CBN framed the move as a reset intended to improve the transmission of monetary policy and bring the benchmark closer to prevailing market rates.

The first auction after the decision offered an early indication of how investors were responding. The 91-day stop rate fell to 15.50% from 16.30% at the previous auction, while the 182-day rate declined to 15.80% from 16.50%. The 364-day bill cleared at 15.89%, down from 16.62%, a fall of 73 basis points.  Demand was not evenly distributed. The 91-day bill received N54.93 billion in subscriptions against N100 billion offered, while the 182-day bill attracted N82.23 billion against N100 billion offered. By contrast, investors submitted approximately N4.09 trillion for the 364-day bill against N400 billion offered, accounting for around 97% of total subscriptions across the auction. That concentration matters. Heavy demand for one-year paper may indicate continued appetite for Nigerian fixed income, but it can also reflect investors attempting to lock in current yields before further rate reductions. The auction results do not distinguish foreign demand from domestic participation, while abundant banking system liquidity provides another source of demand.

David Precious, Senior Market Analyst at EBC Financial Group, said, “The key issue is no longer whether high yields can attract money into Nigeria. They already have. The next test is whether demand remains resilient as the yield advantage narrows, because that would help show whether investors are responding increasingly to stronger external buffers and macroeconomic stability, or whether carry is still doing most of the work.”

Nigeria’s Carry Cushion Is Narrowing from Both Sides

Domestic repricing is only half the equation for international investors. On 16 September, the US Federal Reserve raised its policy rate by 25 basis points to a target range of 3.75% to 4.00%, its first increase since 2023. That raises returns the on-dollar assets even as Nigerian short-term yields decline. The result is a narrower relative cushion for investors willing to take naira currency risk. For a foreign portfolio investor, the nominal return on a Nigerian security is only one part of the calculation. Exchange-rate movements, inflation, liquidity and the ability to exit or reinvest all affect the realised return. A lower Nigerian yield therefore does not automatically lead to capital outflows, but it does leave a smaller cushion if other risks deteriorate.

Precious added, “The gap matters because investors do not assess Nigerian yields in isolation. If returns on lower-risk dollar assets rise while naira yields fall, currency stability and confidence in Nigeria’s external position become more important parts of the decision. The market therefore needs to distinguish demand driven by improving fundamentals from demand that is still primarily about locking in yield.”

From Attracting Capital to Retaining It

This extends a tension EBC highlighted in its July analysis of Nigeria’s foreign-exchange reserves: stronger reserves improve the country’s external buffer, but some incoming portfolio capital can still leave quickly if the risk-return balance changes. That issue is becoming more relevant now that easing has moved from gradual cuts to a 350-basis-point reset. The first phase of Nigeria’s adjustment involved restoring confidence, improving FX market functioning and offering sufficiently high local returns to attract capital. The next phase is harder to assess. It is about whether confidence can remain durable when investors are paid less to hold naira assets. Recent OMO activity offers another useful signal, but not a definitive answer. At the 24 September OMO auction, the CBN offered N1 trillion across three maturities and received approximately N6.1 trillion in subscriptions, with N2.3 trillion allotted. The 152-day bill cleared at 17.29%, while the 180-day bill cleared at 16.99%. However, this demand also needs context. Banking-system liquidity stood at about N5.98 trillion in the week ended 25 September, and a further N2.43 trillion of OMO maturities is expected to return to the system this week. High liquidity may support demand for fixed-income assets independently of foreign portfolio flows.

Why the Naira Becomes More Important as Yields Fall

As the carry cushion narrows, currency performance matters more. The naira closed Friday at N1,329.51 per dollar in the official market, only slightly weaker than the previous session. That relative stability is important because currency depreciation can quickly offset the return earned on a local-currency asset. A smaller yield advantage therefore places more weight on the durability of Nigeria’s external position. If inflation continues to moderate, FX liquidity remains functional and external buffers stay strong, investors may tolerate lower nominal returns. If those conditions weaken, the reduced carry cushion becomes more significant. This is why the policy reset should not be judged solely by the 350-basis-point headline.

What the Market Should Watch Next

The next test is not one auction. Future Treasury-bill and OMO operations will show whether demand remains concentrated at the long end and whether investors continue accepting lower yields. Portfolio-flow composition will be equally important, because current auction data do not identify how much demand is foreign. Liquidity conditions also deserve close attention. With large OMO maturities returning cash to the banking system, strong subscriptions may partly reflect domestic money seeking short-duration assets rather than a fresh wave of foreign capital. The question is whether Nigeria can gradually move from attracting capital through exceptional yields to retaining confidence through stronger fundamentals.

For more information, visit www.ebc.com.

Disclaimer: This material is for information only and does not constitute a recommendation or advice from EBC Financial Group and all its entities (“EBC”). Trading Forex and Contracts for Difference (CFDs) on margin carries a high level of risk and may not be suitable for all investors. Losses can exceed your deposits. Before trading, you should carefully consider your trading objectives, level of experience, and risk appetite, and consult an independent financial advisor if necessary. Statistics or past investment performance are not a guarantee of future performance. EBC is not liable for any damages arising from reliance on this information.

About EBC Financial Group?? 

EBC Financial Group, headquartered in London, UK, is a comprehensive financial services group licensed and operating in multiple key jurisdictions worldwide. The group offers over 200 Contracts for Difference (CFDs) products, including foreign exchange, precious metals, energy, stock indices, US stocks, ETFs, and cryptocurrencies. With branches in major global financial centres such as Tokyo, Sydney, Singapore, and Hong Kong, its service network covers over 100 countries and regions.

Regulation is the cornerstone of trust in the financial industry. EBC ‘s various operating entities hold financial regulatory licenses issued by the UK’s Financial Conduct Authority (FCA), Australia’s Securities and Investments Commission (ASIC), the Cayman Islands Monetary Authority (CIMA), and South Africa’s Financial Sector Conduct Authority (FSCA), strictly adhering to local regulatory rules in their operations.

Leveraging its FCA-regulated liquidity access, EBC has established long-term and stable partnerships with over 50 leading banks and non-bank liquidity providers globally. By integrating clearing-grade liquidity quotes, EBC provides clients with direct access to the primary liquidity market, delivering highly competitive institutional-grade liquidity depth and bank-level spreads, allowing clients to easily enjoy extremely low transaction costs. All clients within the group can enjoy top-tier liquidity access through its FCA license; even for offshore accounts, quotes and orders are ultimately processed by a UK company. Combining big data and AI algorithms to optimize order matching mechanisms, EBC achieves over 87.6% of its orders executed at more favourable prices. For high-frequency and high-volume traders, EBC offers the customized EBC Private Room, a dedicated segregated trading channel that conceals trading orders and avoids market order manipulation. EBC is also one of the few licensed brokers in the industry capable of providing qualified professional investors with FCA liquidity clearing accounts with leverage up to 100x.

The Group’s core management team has over 30 years of experience working in large global financial institutions, having gone through multiple complete financial cycles. They have held core management positions in institutions regulated by the FCA, SEC, and CFTC, and their expertise covers key areas such as brokerage business, operations management, compliance and governance, and corporate risk management.

EBC has been named World Finance’s “Best Broker in the World” for four consecutive years, earning the trust of over 5 million registered users worldwide. Upholding a long-term perspective, the Group actively fulfils its social responsibilities: as an official partner of FC Barcelona, it collaborates with the University of Oxford’s Department of Economics to promote financial education, supports the UN Foundation’s “United to Beat Malaria” project, and partners with the World Association of Girl Guides and Girl Scouts (WAGGGS) to advance women’s empowerment and social equity.

EBC firmly believes that everyone who trades seriously deserves to be treated seriously.
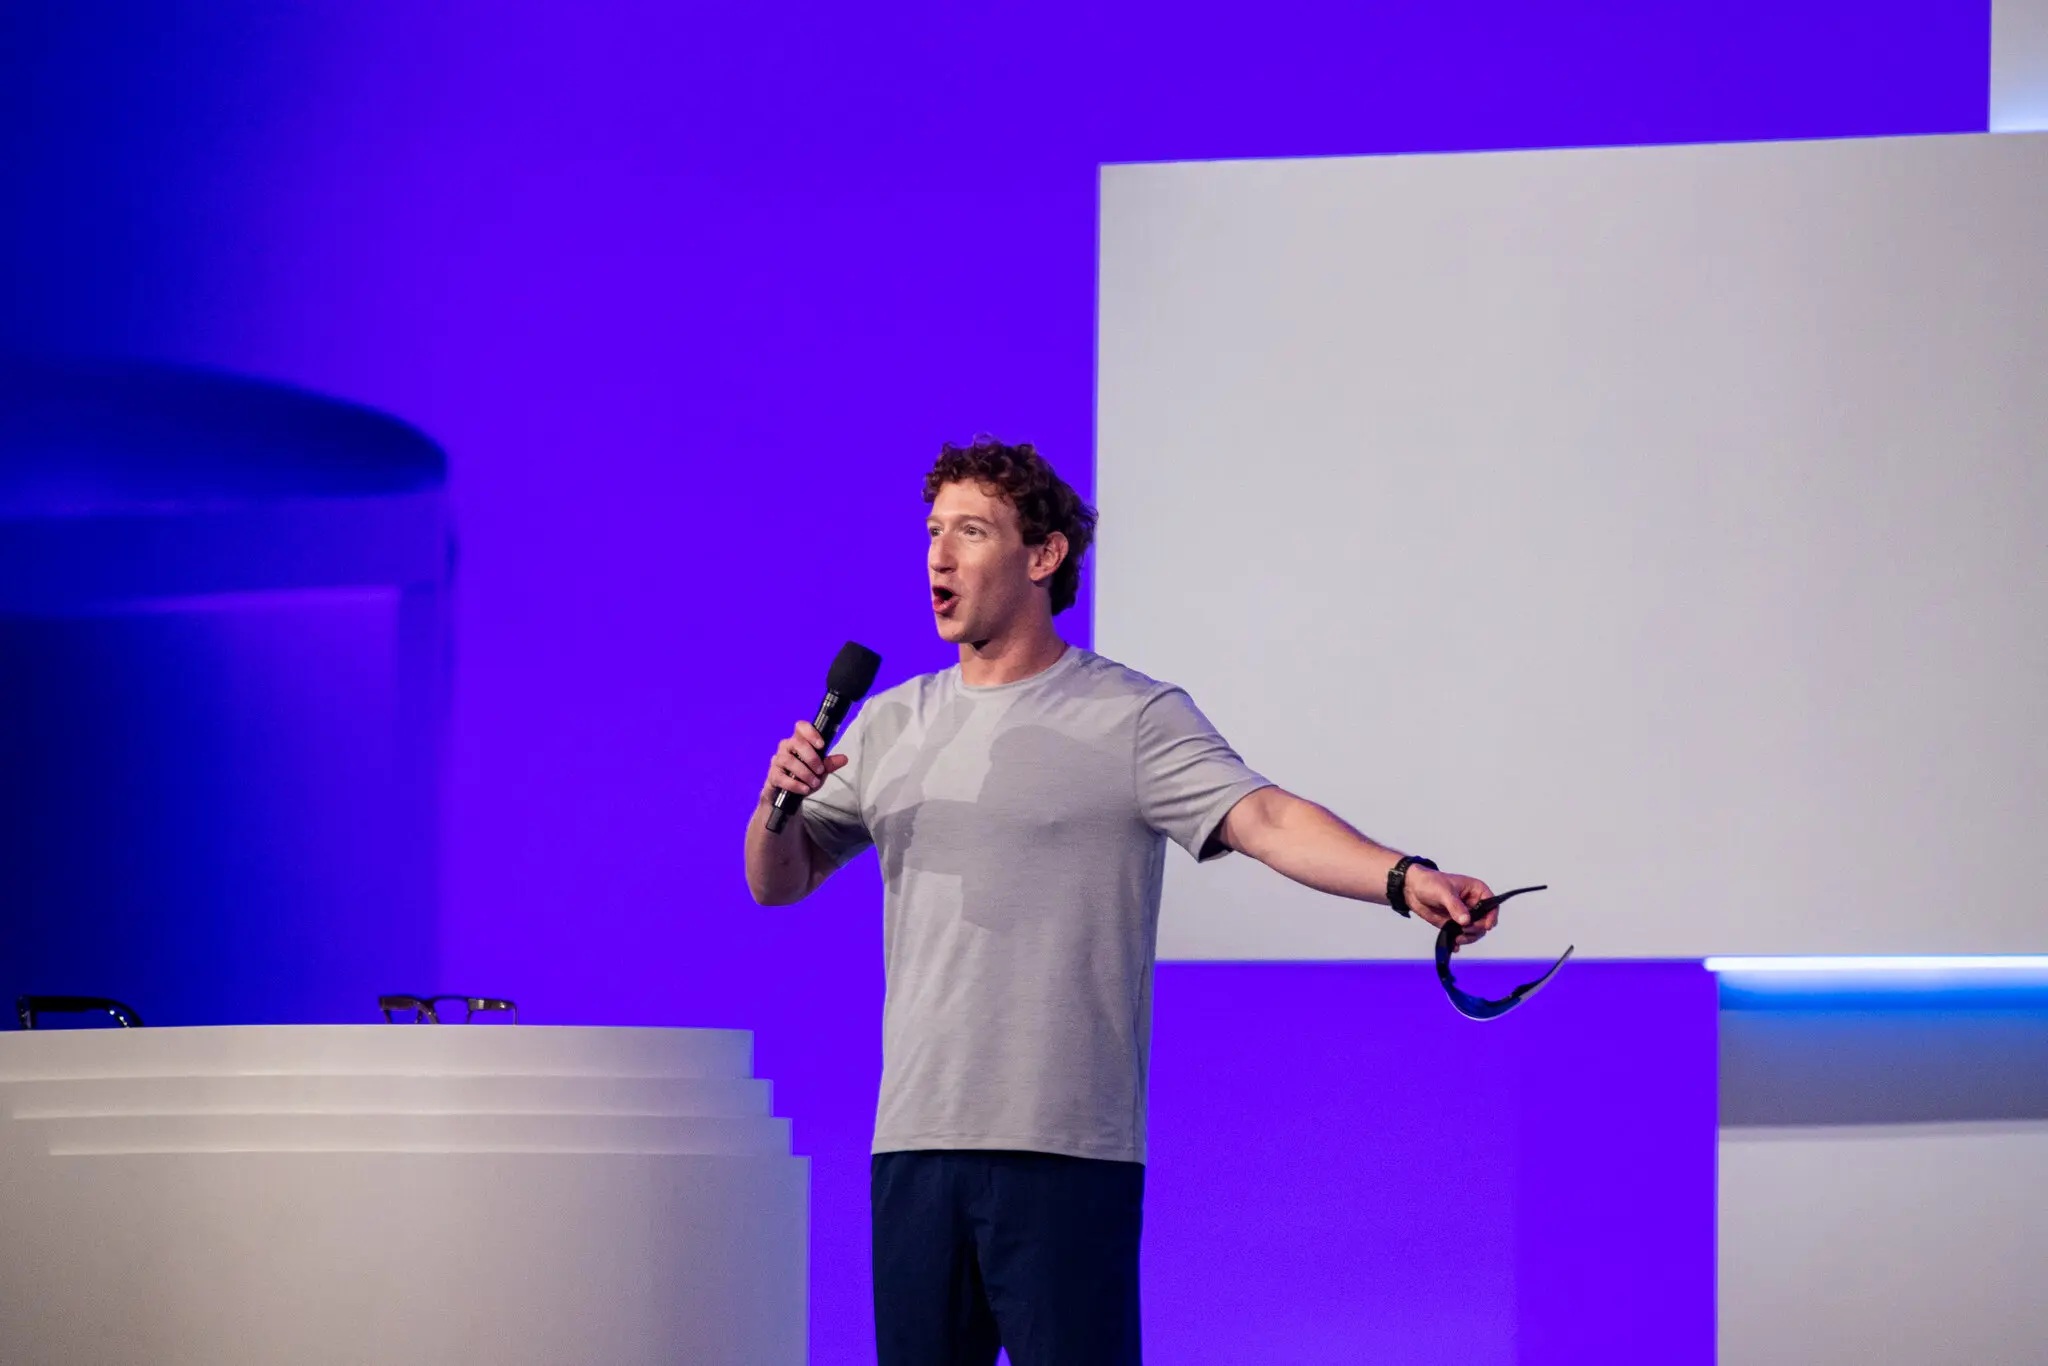
 

Meta Poaches MongoDB CEO to Lead Enterprise AI Push as Zuckerberg Takes Aim at Corporate Market

0

Meta Platforms is hiring MongoDB CEO Chirantan “CJ” Desai to lead a newly created business aimed at bringing the company’s artificial intelligence models, agents and software tools to corporate customers, in a move that signals a broader attempt to turn Meta’s rapidly expanding consumer AI business into an enterprise platform.

MongoDB shares have fallen about 28% on Monday after the database software company disclosed Desai’s departure, less than a year after he became chief executive. MongoDB has appointed its former CEO, Dev Ittycheria, as interim chief executive while it searches for a permanent replacement.

The reaction underpins the importance investors placed on Desai’s leadership as MongoDB seeks to compete in an increasingly crowded market for databases, cloud infrastructure and AI-enabled enterprise software.

“While the departure is disappointing, we believe MongoDB remains well-positioned strategically and view the share-price reaction as overdone,” Piper Sandler said in a note.

For Meta, however, the hire represents a significant escalation of its enterprise ambitions.

Desai will report directly to Meta CEO Mark Zuckerberg as chief enterprise platform officer, a newly created position. His mandate will be to turn Meta’s AI technology stack into products and services that businesses can deploy inside their own operations.

That puts an executive with extensive enterprise software experience at the center of Meta’s effort to move beyond its traditional advertising-driven business and establish AI as a platform used directly by companies.

Meta Takes Its AI Stack into The Enterprise

Meta said Monday that its new Meta Enterprise Platform will bring together its AI models, agents and tools for corporate customers. The offering will include Muse, Meta Business Agent and coding tools, giving businesses access to several parts of Meta’s AI portfolio through an enterprise-focused platform.

The move represents a different commercial proposition from Meta’s consumer AI strategy.

Muse was launched earlier this month as a personal AI agent designed to perform tasks for consumers, including shopping, booking travel, sending emails, and making payments. Its rapid rise in Apple’s App Store and Google Play rankings has drawn attention from analysts, who have described it as potentially the biggest U.S. app launch since OpenAI’s ChatGPT helped ignite the current AI boom in November 2022.

Meta now appears to be attempting to take some of that momentum into the corporate market.

The enterprise opportunity is considerably different from consumer AI. Companies need AI systems that can work with proprietary data, connect to existing software, meet security and compliance requirements, and operate reliably across large organizations. They also need clear controls over what an AI agent is allowed to do.

That makes Desai’s background especially relevant.

Before joining MongoDB, he led product and engineering at Cloudflare and spent almost eight years at ServiceNow, where he ultimately became president and chief operating officer. Both companies operate deeply within enterprise technology, giving Desai experience with the software infrastructure and purchasing processes that determine whether businesses adopt new technologies at scale.

His MongoDB experience adds another layer. MongoDB provides databases and related tools used by companies to build and operate applications, manage data, conduct searches and analytics, and support AI workloads.

Meta is therefore bringing in an executive whose career has largely centered on the infrastructure layer that enterprises need before they can deploy AI at scale.

Zuckerberg’s Enterprise Bet

The decision to have Desai report directly to Zuckerberg also signals the importance Meta is attaching to the new business.

Meta has spent heavily on AI infrastructure and model development, while its consumer products give it an enormous distribution network. The unresolved commercial question has been how much of that investment can be converted into direct enterprise revenue.

Advertising remains the economic foundation of Meta’s business, but selling AI products directly to companies could create another revenue stream and give the company a more diversified role in the technology stack.

The enterprise market is already crowded.

Microsoft has embedded AI across its productivity and cloud products, Google offers Gemini across its enterprise ecosystem, Amazon is integrating AI into AWS, and a large group of startups is competing to provide specialized agents and AI infrastructure.

Meta enters that market with a different set of assets. Its open model strategy has given developers access to the Llama family, while its consumer products provide a huge user base, and its growing collection of AI agents gives the company experience deploying AI at large scale.

The challenge is turning those assets into something corporations are willing to integrate deeply into their operations. That is where the Meta Enterprise Platform could become important. Rather than selling a single chatbot, Meta is positioning its AI offering as a collection of models, agents, and developer tools that businesses can use for different functions. The inclusion of coding tools and Meta Business Agent suggests the company wants to participate in both software development and business workflows.

Muse could eventually become another component of that broader platform rather than remaining primarily a consumer application.

MongoDB Faces an Unexpected Leadership Test

For MongoDB, Desai’s departure creates an immediate leadership transition at a time when the database industry is being reshaped by AI. MongoDB has built its position around helping developers manage application data, while AI is increasing demand for databases capable of handling unstructured information, vector search, and real-time workloads.

Ittycheria’s return as interim CEO provides continuity because he previously led MongoDB for almost a decade. But the board now has to find a permanent successor while investors assess whether the leadership change affects the company’s product and AI strategy.

The sharp decline in MongoDB shares shows that investors viewed the departure as material, even though Piper Sandler argued that the market reaction was excessive.

For Meta, meanwhile, the appointment is effectively an acknowledgement that building frontier AI models is only one part of the commercial battle. The next contest is over distribution, integration, and trust inside businesses.

AI companies have spent the past several years competing over model benchmarks and consumer adoption. The enterprise market requires something different: convincing companies to allow AI systems into sensitive workflows and giving those systems enough access to act on corporate data and software.

Desai’s mandate suggests Meta wants to compete directly on that layer.

If Meta can connect its models and agents to the systems businesses already use, the company could turn its AI investment into an enterprise software business rather than relying primarily on consumer engagement and advertising.

The hire also illustrates how the AI race is reshaping the broader technology industry. Following its $15 billion acqui-hire strategy that resulted in the recruitment of Scale AI CEO Alexandr Wang last year, Meta is no longer simply recruiting AI researchers and engineers. It is now recruiting executives who understand how large companies buy, deploy, and manage software.

That may ultimately prove as important as model performance as the industry moves from AI assistants that answer questions to agents that perform work.

Tata Trusts Propose Merger to Help Tata Sons Avoid RBI Listing Requirement

0

Tata Trusts have proposed merging two operating companies with Tata Sons in an attempt to change the conglomerate’s regulatory status and potentially avoid a stock-market listing that the Reserve Bank of India has pushed the group toward.

The proposal, announced Monday, would combine Tata Electronics Systems and Tata Consulting Engineers with Tata Sons, transforming the parent company from an entity primarily holding investments into one with substantial operating businesses and revenue.

Tata Trusts, which owns a 66% stake in Tata Sons, submitted the proposal to the Tata Sons board. Any restructuring would require board approval before it could be presented to the RBI.

The move comes amid a growing dispute between Tata Trusts and the Tata Sons board over the direction of the group’s parent company. The Trusts have opposed the reappointment of Tata Sons Chairman N Chandrasekaran and the board’s decision to pursue a public listing.

At the center of the dispute is Tata Sons’ regulatory classification.

Tata Sons was designated by the RBI in 2022 as a core investment company, or an “upper-layer” non-banking financial company. That classification brought the holding company under tighter regulatory requirements, including an obligation to list its shares.

Earlier this month, the RBI rejected Tata Sons’ application to be deregistered as a non-bank financial company, leaving the conglomerate facing increased pressure to proceed with a listing. The Trusts’ proposed restructuring seeks to change the underlying composition of Tata Sons rather than directly challenge the listing requirement.

Under the proposal, the merged company would have operating revenue of 1.05 trillion rupees ($10.94 billion), according to the Trusts. They said this would be substantially higher than income from financial assets, which stood at 400.72 billion rupees and represented 64.3% of the combined entity’s total income.

“This will also be in line with the previous classification (after 2004) by RBI of TSPL as a ‘non-banking, non-financial company’,” the Trusts said.

Tata Sons’ status as a financial holding entity is central to the RBI’s requirement that it remain subject to the regulatory framework governing upper-layer NBFCs. By bringing significant operating businesses directly into Tata Sons, the Trusts are seeking to establish a different business profile for the parent company. Whether that would be sufficient to change its regulatory classification, however, would ultimately depend on the RBI.

Therefore, the proposal puts the Tata Sons board in a difficult position. The Trusts cannot implement the restructuring on their own, despite their controlling 66% ownership stake, because the proposed merger requires board approval.

It also adds a new dimension to the dispute over the group’s future. Tata Sons has been moving toward a potential listing that could create a public market valuation for the holding company, while the Trusts have opposed that direction.

The listing question has significance beyond regulatory compliance for Tata Sons. The company sits at the center of a sprawling conglomerate whose businesses include Tata Consultancy Services, Tata Motors, Tata Electronics and other major operating companies. A listing would give public-market investors direct exposure to the parent company and could alter the way capital is allocated across the group.

But the proposed merger offers a different route to Tata Trusts. Instead of taking Tata Sons to the market, the structure would seek to make the company more clearly an operating enterprise, potentially reducing the rationale for its classification as a financial holding company.

The proposal also comes at a sensitive point for Tata Group governance. Tata Trusts’ 66% ownership gives the charitable entities decisive economic control of Tata Sons, while the company’s board is responsible for running the holding company and overseeing the interests of the wider group.

The disagreement over Chandrasekaran’s reappointment and the listing has therefore exposed a broader question about how the country’s largest business groups should balance concentrated ownership, professional management and regulatory requirements.

The immediate test lies in Tata Sons’ board’s willingness to accept the merger proposal. If it does, the RBI would then have to assess whether the resulting company qualifies for a different regulatory treatment.

Telegram Wallet Rebrands as Walt, Expanding Into Crypto Trading and Investing

0

Telegram’s Wallet is entering a new phase as Walt, signaling a broader ambition for crypto inside one of the world’s largest messaging ecosystems. What began primarily as a convenient way for Telegram users to store and move digital assets is being repositioned as an all-in-one platform for trading, investing and managing crypto.

The rebrand therefore represents more than a change of name; it reflects an attempt to expand the role of embedded crypto infrastructure within everyday digital communication. The timing is particularly significant because Telegram is also preparing to introduce Gram, its native self-custodial wallet.

According to the announcement, Gram and Walt will coexist rather than compete directly. Their separation points toward a deliberate two-layer strategy for cryptocurrency access across Telegram.

Gram is expected to focus on everyday activity throughout the Telegram ecosystem. Its role could resemble an accessible financial layer integrated into ordinary interactions, allowing users to manage digital assets without necessarily seeking out a dedicated crypto application.

Walt now supports 300+ assets, 100+ tokenized stocks, ETFs and metals, and 70+ perpetual markets, with crypto cards and AI-powered trading also on the roadmap. The platform is also expanding into crypto cards and AI-powered trading, with upcoming tools designed to help users analyze markets, assess portfolio risk, discover trades and execute perpetuals through conversational interfaces.

Walt, by contrast, is positioned toward users who want more advanced exposure to cryptocurrency, including trading, investing and broader asset-management capabilities. That distinction could become important as Telegram attempts to make crypto less dependent on standalone exchanges and wallets.

Instead of requiring users to move between messaging applications, centralized exchanges, decentralized applications and separate wallet interfaces, Telegram can potentially bring several of those functions into a single environment.

The evolution from Wallet to Walt also reflects a wider transformation taking place across the crypto industry. Wallets are increasingly becoming financial interfaces rather than simple storage tools.

Modern crypto wallets can provide access to swaps, decentralized finance, tokenized assets, trading markets and investment products. The wallet is gradually becoming the gateway through which users interact with an entire financial ecosystem.

For Telegram, the opportunity is especially large because the messaging platform already provides a massive social distribution network. Crypto applications embedded within Telegram can potentially benefit from existing communities, channels, bots and mini-applications.

This creates an environment where financial products can be discovered and used without requiring users to leave the platform. However, the expansion also introduces important challenges.

A platform that combines messaging, payments, trading and investment must address security, custody, fraud, regulatory requirements and user protection. Self-custody can give individuals greater control over their assets, but it also places greater responsibility on users to protect private keys and recovery credentials.

Meanwhile, trading and investment functionality introduces risks that do not exist when a wallet is used simply for transfers. The coexistence of Gram and Walt therefore creates an interesting architecture for Telegram’s crypto strategy.

Gram can serve as the simpler, ecosystem-oriented wallet, while Walt can target users seeking deeper participation in digital-asset markets. Ultimately, the Walt rebrand suggests that Telegram sees crypto as more than an additional feature.

It is becoming part of the platform’s broader financial infrastructure. If Telegram can successfully connect everyday messaging with self-custody, trading and investment, the distinction between a social application and a crypto-financial platform could become increasingly difficult to maintain.

Next Tekedia Capital Cycle Begins Oct 5

0

On October 5, the next Tekedia Capital investment cycle begins. We plan to present approximately 20 innovative companies spanning nuclear energy, satellite systems, artificial intelligence, semiconductors, space technology, software, insurance and more.

Join us and invest in companies shaping the future. Begin here.