DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 30

BlockDAG Activates Live USDT Buybacks, While Cardano Crypto & Zcash Rally

0

Crypto market participants increasingly look beyond short-term price fluctuations when identifying strategic allocations. The Cardano crypto ecosystem is gathering momentum, with ADA appreciating 2.90% against the backdrop of the TOKEN2049 conference. Concurrently, the Zcash price continues to hold above $1,600 following the rollout of a European ETP by 21Shares.

However, BlockDAG (BDAG) has formally launched its live USDT Buyback mechanism covering both New BDAG and Legacy BDAG holdings. Market entrants also have a final opportunity to acquire BDAG directly at $0.000000005 and subsequently execute a repurchase at the stated $0.05 buyback price. For investors analyzing what crypto to buy now, BlockDAG’s structured buyback framework creates a compelling case relative to established market alternatives. 

Cardano Crypto Price Surges 2.9%
The Cardano crypto valuation recently registered a 2.90% upward movement, advancing to approximately $0.2522. Underpinning this price action is expanding network usage, marked by derivatives trading volume approaching $1 billion and open interest nearing $600 million. From a technical standpoint, ADA is holding above both its 50-day moving average of $0.2142 and its 200-day moving average of $0.2050. On-balance volume stands at 45.95 billion, signaling consistent accumulation from market participants.

Despite these positive technical indicators, ADA faces substantial overhead resistance near the $0.2545 level. Furthermore, elevated leverage in derivatives markets introduces heightened volatility risks, where a breakdown below key support zones could trigger rapid price corrections.

Zcash Price Rallies as Institutional Adoption Soars

The Zcash price has demonstrated notable momentum, rising over 70% across a 30-day period to trade above $1,600. Expanding institutional integration, evidenced by new European ETP listings and dedicated ETF capital inflows, has provided structural support for this upward trend. Momentum indicators reflect sustained buying strength, with technical targets pointing toward the $1,800 threshold.

Notwithstanding this rapid advance, ZEC encounters a tight resistance range between $1,560 and $1,615. High open interest in futures markets increases systemic leverage, leaving the asset vulnerable to swift pullbacks if broader market momentum decelerates.

BlockDAG: Live USDT Buybacks Offer Guaranteed $0.05 Value

Investors frequently evaluate long-term mechanics beyond immediate token pricing when determining capital placement. BlockDAG’s USDT Buyback program introduces a structured model to address this consideration. Both New BDAG and Legacy BDAG qualify for participation when eligible direct-coin acquisitions take place at the $0.000000005 price.

Rather than maintaining separate accounting for the two token versions, BlockDAG aggregates eligible holdings into a single, unified USDT Buyback Balance accessible via the central user dashboard.

This framework provides participants with a clear operational metric. Following the completion of the eligibility phase with a few days left, BlockDAG calculates the net post-compression balance. Participants can then liquidate that final balance under the specified $0.05 USDT Buyback Price.

The user dashboard displays real-time personal USDT tracking, offering clear visibility into overall buyback positioning. With distributions scheduled to start in November through batched releases, the model provides a defined mechanism that operates independently of open-market price fluctuations.

For the BDAG community, the integration of both token variants into one system, combined with a $0.000000005 entry baseline and a $0.05 USDT repurchase valuation, establishes a transparent ROI framework. For market participants assessing what crypto to buy now, BlockDAG’s buyback program presents a distinct structural approach.
Key Takeaways!

While the recent price appreciation in Cardano crypto and sustained strength in the Zcash price indicate positive market activity, BlockDAG introduces a different value proposition through its operational USDT Buyback program. By allowing both New BDAG and Legacy BDAG to qualify, the protocol establishes a single unified structure for all participants.

New buyers retain a narrow window with a few days left to secure BDAG at $0.000000005 before redeeming at the fixed $0.05 buyback rate. When evaluating what crypto to buy now, BlockDAG offers a distinct model driven by its active buyback program, growing network infrastructure, and time-sensitive entry pricing.

Presale: https://purchase.blockdag.network

Website: https://blockdag.network

Telegram: https://t.me/blockDAGnetworkOfficial

Discord: https://discord.gg/Q7BxghMVyu


AMD’s $1 Trillion Moment Shows How AI Is Repricing the Chip Industry

0

Advanced Micro Devices briefly entered the exclusive $1 trillion market-capitalization club in September, marking another dramatic milestone in the financial transformation of the semiconductor industry.

The move was not isolated to AMD. Intel and Arm also surged sharply, showing how investors are increasingly treating the entire chip ecosystem as a major beneficiary of the artificial-intelligence investment cycle.

AMD shares jumped nearly 10% during the September 21 session, reaching a record high around $616 and pushing the company’s market value above $1 trillion.

Reuters reported that the move reflected investor expectations that AMD can expand its role in AI computing. The significance extends beyond a round number. AMD has spent years positioning itself as a challenger in processors and accelerators.

Competing for a greater share of the computing infrastructure required to train and run increasingly sophisticated AI systems. Its arrival at the trillion-dollar level demonstrates how dramatically financial markets have repriced companies connected to that infrastructure.

The rally also spread rapidly across the semiconductor sector. Intel gained more than 12% during the same period, while Arm shares climbed by double digits. The Philadelphia Semiconductor Index rose more than 4%, illustrating the breadth of the move.

Part of the enthusiasm came from expectations that AI demand is becoming broader than the market’s earlier focus on high-end GPUs. Modern AI infrastructure requires CPUs, networking, memory, accelerators and increasingly specialized components. That creates opportunities for companies across the semiconductor supply chain.

AMD is particularly exposed to this transition because its business spans CPUs and data-center accelerators. As hyperscalers and enterprises continue investing in AI infrastructure, investors are attempting to determine which companies can capture a meaningful portion of that spending.

The market’s reaction reflects a larger change in how AI is being commercialized. The expansion of AI assistants and agentic applications could require substantially more computing capacity.

Recent enthusiasm surrounding Meta’s Muse AI assistant helped reinforce expectations that AI applications are moving from experimental products toward mass-market services. Meta itself surged more than 11% during the semiconductor rally.

Yet a trillion-dollar valuation also raises a fundamental question: how much future growth is already embedded in semiconductor prices? A company’s market capitalization represents investors’ expectations about future earnings and cash flows, not simply today’s revenue.

When an industry becomes the center of a powerful investment narrative, valuations can rise much faster than underlying financial results. That creates opportunities when growth expectations are fulfilled, but it can also increase sensitivity to disappointing earnings, weaker capital expenditure or delays in AI deployment.

AMD’s brief crossing of $1 trillion therefore represents more than another technology-stock milestone. It is evidence of the enormous economic expectations surrounding AI infrastructure.

Nvidia, Broadcom and Micron have already demonstrated how semiconductor companies can become trillion-dollar businesses when their technologies become central to a structural shift in computing. AMD’s arrival adds another major player to that group.

The broader message for markets is clear: AI is no longer being valued solely through software companies and model developers. The physical infrastructure underneath the technology — processors, memory, networking equipment and data centers — is becoming an investment theme in its own right.

AMD’s trillion-dollar moment may ultimately prove temporary or become a lasting valuation milestone. Either way, it captures a defining feature of the current market: capital continues to flow toward the companies expected to build the computing infrastructure required for the next generation of artificial intelligence.

Trump, Xi Extend Trade Truce as Taiwan, AI and Strategic Rivalry Dominate White House Talks

0

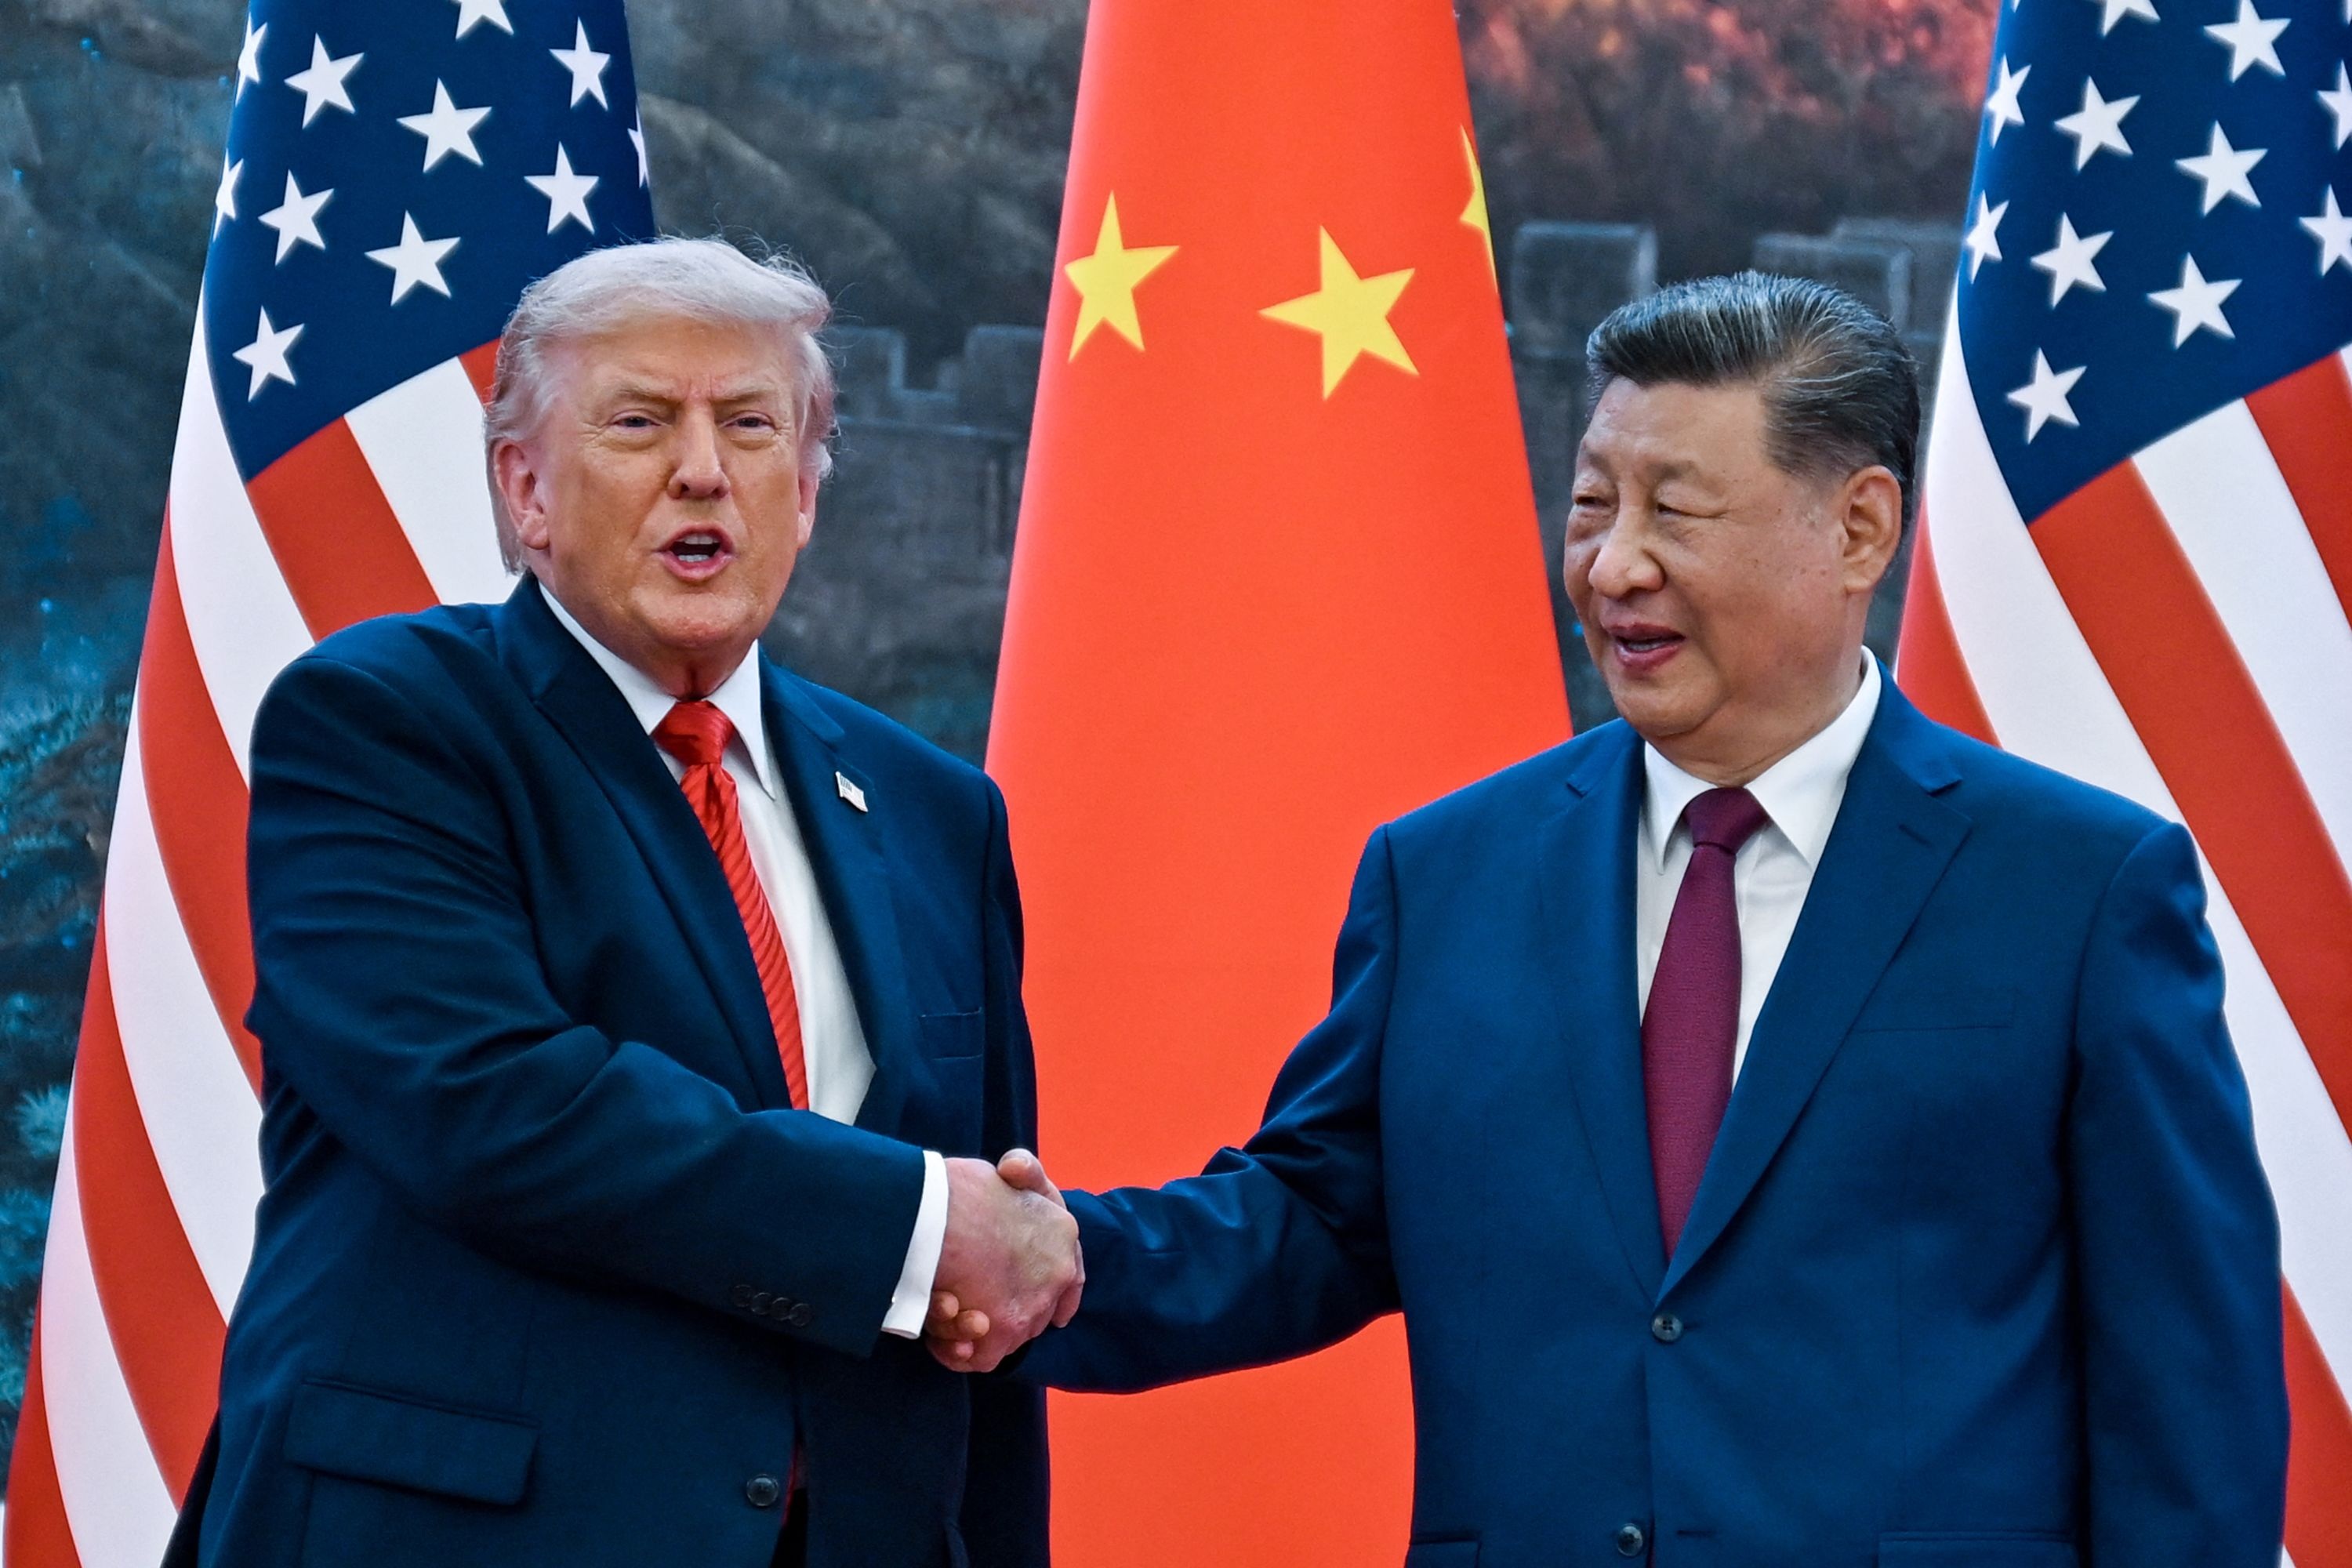
US President Donald Trump welcomed Chinese President Xi Jinping to the White House on Thursday for high-level talks spanning trade, artificial intelligence, Taiwan and the broader strategic rivalry between the world’s two largest economies.

The meeting produced an extension of the existing trade truce, but left many of the most difficult economic disputes unresolved. At the same time, the leaders offered sharply different visions for how artificial intelligence should be governed and used, while Taiwan and the risk of a wider US-China confrontation remained central to the relationship.

For financial markets and multinational companies, the immediate outcome offers some additional breathing room on trade but does little to remove uncertainty around tariffs, technology restrictions, critical minerals and China’s commitments to buy US goods.

Trade Truce Extended, But Key Disputes Remain

The United States and China agreed to extend their trade agreement by two months, according to Treasury Secretary Scott Bessent, giving both sides additional time to negotiate after the existing arrangement was due to expire in November.

Bessent said the extension would give Washington and Beijing “more time to see what we can do on the economic front.”

The extension avoids an immediate escalation in tariffs, but it is not a comprehensive settlement. Issues including tariff levels, Chinese purchases of US agricultural products, rare-earth supplies and restrictions on advanced technology remain subject to negotiation.

The gap between commitments and actual trade flows is already creating friction.

Bessent said on Wednesday that China was meeting its commitment under the previous agreement to purchase 25 million tons of US soybeans, but remained behind on a separate pledge to buy $17 billion in other agricultural goods.

US officials have also said Chinese deliveries of rare earths are falling short of expectations, keeping one of the most important pressure points in the relationship alive. China dominates the processing of many rare-earth materials used in electronics, defense equipment and advanced manufacturing, giving Beijing significant leverage in negotiations over technology and trade.

For businesses, the extension provides a temporary reprieve rather than a definitive change in the operating environment. Lower tariffs can support cross-border trade and investment, but companies still have to make supply-chain and capital-allocation decisions without knowing whether the current arrangements will eventually become permanent.

That uncertainty has become a defining feature of the US-China economic relationship, with periods of tariff escalation followed by temporary agreements that postpone rather than resolve the underlying disputes.

Taiwan Remains A Major Fault Line

Xi also raised Taiwan during his meeting with Trump, according to China’s official Xinhua news agency, calling on Washington to “handle the Taiwan question with prudence” and urging the United States to oppose Taiwanese independence.

That formulation goes further than Washington’s longstanding position that it does not support Taiwan independence.

There was no immediate White House readout of the exchange, and the Trump administration has not indicated that it intends to alter its established language on Taiwan.

The wording matters because even a subtle change in Washington’s position could affect perceptions of US deterrence and the political debate in Congress. Taiwan remains one of the most sensitive issues in the bilateral relationship, particularly because Beijing regards the island as part of China and has not ruled out the use of force to bring it under its control.

For markets, Taiwan also carries an economic dimension. The island is central to the global semiconductor industry, meaning a serious deterioration in US-China relations over Taiwan would extend far beyond defense and diplomacy into technology supply chains, electronics manufacturing and the broader AI industry.

Xi’s reference to the “Thucydides Trap” added another layer to the discussion. The concept describes the risk that rivalry between an established power and a rising power can produce conflict. Xi said the risk could be overcome, while arguing that the two countries should cooperate where their interests overlap.

He called for regular military dialogue and stronger mechanisms for preventing crises from escalating.

Trump likewise emphasized areas where Washington and Beijing have shared interests, invoking the countries’ cooperation during the Second World War against Japan as an example of what the two powers could accomplish when they work together.

The contrasting messages illustrate the broader challenge confronting the relationship. Both governments have incentives to prevent competition from becoming uncontrolled confrontation, while continuing to disagree over trade, technology, Taiwan and the balance of power in the Asia-Pacific.

AI Exposes A Sharper Policy Divide

Artificial intelligence emerged as another important point of difference.

Trump has argued for allowing the US AI industry to develop with limited additional regulation. In a social media post, he said AI should remain “exactly where it is” and suggested relying on the Justice Department rather than imposing new guardrails. He also said China held the same position.

Xi offered a markedly different formulation.

China and the United States, as leading AI powers, have both the capability and responsibility to manage the technology’s development, he said.

“We have both the capability and responsibility to develop and manage AI for good, and ensure that the development of AI is always under human control and serves the well-being of the people,” Xi said.

Washington has imposed restrictions on China’s access to some advanced semiconductor technologies and AI computing capabilities, while Beijing has accelerated efforts to develop domestic alternatives. At the same time, both countries are confronting questions about the security risks posed by increasingly capable AI systems.

The presence of leading US technology executives at the White House state dinner underscored the economic importance of the technology relationship. Alphabet CEO Sundar Pichai, OpenAI CEO Sam Altman and Nvidia CEO Jensen Huang were among the prominent AI figures expected to attend.

Their presence also highlights an important feature of the current US-China rivalry: AI is simultaneously an area of commercial cooperation, technological competition and national-security concern. The companies developing frontier models and the semiconductor infrastructure required to run them are increasingly operating in an environment shaped by government decisions over exports, investment and security.

The meeting therefore produced no comprehensive reset in the relationship. Instead, it established a temporary extension of the trade truce while leaving the core economic and geopolitical disputes in place.

The two-month trade extension may buy negotiators time. It does not, by itself, settle the larger contest that brought Trump and Xi back to the negotiating table.

Strategy Resumes Bitcoin Buying as Corporate Treasury Bet Deepens and BTC Rebounds

0

Strategy has resumed its aggressive Bitcoin accumulation, ending a temporary buying pause with the purchase of 950 BTC for approximately $76 million.

The latest acquisition brings the company’s reported Bitcoin holdings to 846,000 BTC, reinforcing its position as one of the most significant corporate holders of the cryptocurrency.

The purchase is notable not simply because of its size, but because of what it signals about Strategy’s long-term treasury strategy.

After stepping back from acquisitions for a period, the company has returned to the market at a time when Bitcoin remains highly sensitive to monetary policy, institutional flows and broader risk sentiment.

The decision suggests that the pause was not necessarily a change in direction, but part of a more tactical approach to capital deployment. At an average price of roughly $80,000 per Bitcoin, the latest purchase represents a substantial corporate commitment.

Strategy is no longer treating Bitcoin as a small alternative asset on its balance sheet. Instead, the cryptocurrency has become central to the company’s financial identity and capital strategy.

The scale of the holdings also changes the way investors view Strategy. The company effectively operates with two intertwined stories: its underlying software business and its exposure to Bitcoin.

As the Bitcoin treasury expands, movements in the cryptocurrency can have a significant influence on the company’s market valuation, investor sentiment and financing strategy.

That structure has helped Strategy become one of the most visible examples of corporate Bitcoin adoption. Rather than simply holding cash or traditional securities, the company has repeatedly chosen to convert capital into an asset with a fixed maximum supply.

Supporters of the strategy argue that Bitcoin can serve as a long-duration treasury asset and provide exposure to potential appreciation. Critics point to volatility, financing risks and the possibility that falling Bitcoin prices could pressure the value of the company’s holdings.

The latest purchase comes against a complicated backdrop for Bitcoin. The cryptocurrency has recently experienced sharp price movements as markets digest changes in monetary policy, regulatory developments and institutional demand.

Spot Bitcoin exchange-traded funds have also become an increasingly important source of market liquidity, creating another channel through which traditional capital can enter or leave the asset.

Strategy’s buying therefore carries significance beyond the company’s own balance sheet. Every large acquisition demonstrates how corporate treasuries can increasingly influence Bitcoin’s market structure.

The company is effectively competing for a scarce digital asset alongside ETFs, funds, governments, miners and individual investors. There is also a broader question about how sustainable the strategy becomes as the holdings grow.

Purchasing hundreds or thousands of Bitcoin requires substantial capital, and Strategy has historically used various financing mechanisms to support its accumulation. That creates a relationship between Bitcoin’s market performance, the company’s access to capital and investor appetite for its securities.

With 846,000 BTC now reportedly held, Strategy’s strategy has entered a different phase. The question is no longer whether a public company can experiment with Bitcoin as a treasury asset. It is whether an increasingly large corporate balance sheet can continue accumulating Bitcoin through different market cycles.

The return to buying provides a clear answer about Strategy’s current direction: the pause did not end the accumulation strategy. It resumed with another $76 million commitment, further cementing Bitcoin as the centerpiece of the company’s treasury model.

Bitcoin Rebounds Above $85,000 as ETF Demand Overpowers Policy Headwinds

Bitcoin has delivered a striking rebound, climbing back above $85,000 after a period when investors had plenty of reasons to remain cautious. The cryptocurrency gained roughly 13% from its mid-September level, briefly pushing above $87,000 as institutional demand returned through U.S. spot Bitcoin exchange-traded funds.

The most important figure behind the move was not Bitcoin’s price itself, but the scale of capital flowing into regulated investment products.

On September 21, U.S. spot Bitcoin ETFs recorded approximately $998.95 million in net inflows, their largest single-day inflow since October 2025.

BlackRock’s IBIT accounted for $381.4 million, while ARK 21Shares and Fidelity attracted $289.1 million and $238.8 million respectively. That buying arrived at an unusual moment Just days earlier, the U.S. Senate had failed to advance the CLARITY Act, legislation intended to establish a clearer regulatory framework for digital assets.

At the same time, the Federal Reserve had raised its policy rate by 25 basis points, bringing the target range to 3.75%-4%. Both developments could have weighed on an asset class that remains sensitive to liquidity, regulation and investor risk appetite.

Instead, Bitcoin absorbed the shocks. The market response suggests that investors were increasingly focused on direct demand for Bitcoin rather than waiting for every regulatory or monetary-policy question to be resolved.

The ETF structure has become particularly important because it allows traditional investors and institutions to obtain Bitcoin exposure through familiar financial products. Nearly $1 billion entering these funds in a single session therefore represents more than a headline number.

It demonstrates that significant pools of conventional capital can move into the asset even when the broader policy environment remains unsettled. Short covering may have amplified the move.

Analysts cited by The Block pointed to a combination of renewed risk appetite, strong spot ETF demand and short covering after Bitcoin moved through important technical levels.

Once Bitcoin broke above $85,000, traders who had positioned for another decline were potentially forced to buy back positions, adding further upward pressure. The recovery also carried technical significance.

Bitcoin moved above its 50-week moving average, a level that had remained important during the preceding downturn. Such moves can change market psychology because traders begin reassessing whether a decline is continuing or whether the market has entered a broader recovery phase.

Yet the rebound does not eliminate the risks. The Federal Reserve’s rate decision demonstrates that monetary policy can still challenge speculative assets. Treasury yields have also remained an important variable, with Bitcoin subsequently retreating as the 10-year Treasury yield moved above 5%.

The CLARITY Act’s failure likewise leaves regulatory uncertainty unresolved. Institutional participation may continue growing, but investors still have to navigate questions surrounding market structure, securities regulation and the future division of authority between U.S. regulators.

For Bitcoin, the immediate message from the market is clear: demand has returned with considerable force. The nearly $1 billion ETF inflow transformed a difficult policy week into one of the cryptocurrency’s strongest rebounds of the year.

The next question is whether that institutional demand can persist after the initial surge. A single extraordinary inflow can move a market, but sustained capital allocation is what determines whether a rebound becomes a durable trend.

US Senators Delay Vote on Permanent Chinese Vehicle Ban

0

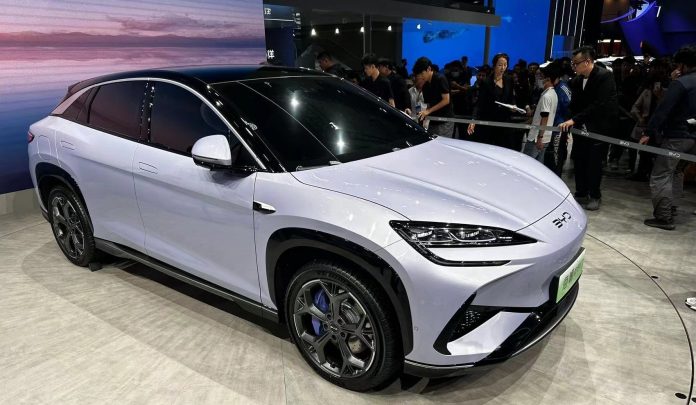
A bipartisan effort to permanently bar Chinese vehicles from the US market has been delayed until next week as its sponsors seek to win over a Republican senator whose opposition could block the legislation, adding another complication to Washington’s increasingly contested policy toward Chinese automakers.

Republican Senator Bernie Moreno and Democratic Senator Elissa Slotkin had planned to use a fast-track procedure requiring unanimous Senate consent to advance the bill on Thursday. Instead, they agreed to postpone the move while they negotiate with Republican Senator Rand Paul, who has raised concerns about the legislation, congressional aides said. Reuters reported that Paul intends to continue discussing those concerns over the weekend and into next week.

The delay came on the same day President Donald Trump met Chinese President Xi Jinping in Washington, placing the proposed vehicle ban directly against the backdrop of broader US-China negotiations over trade, technology and supply chains.

Moreno said he remained hopeful that the bill would clear the Senate next week and that the House of Representatives would pass identical legislation when it returns in November.

The legislation already has significant support in the Senate. Slotkin said earlier that she understood the support to stand at 99 senators to one, although the requirement for unanimous consent means a single senator can prevent the fast-track procedure from moving forward.

The bill also has more than 100 co-sponsors in the House, while the United Auto Workers, Teamsters, International Association of Machinists, United Steelworkers and the Vehicle Suppliers Association have backed it.

The immediate dispute with Paul matters because the sponsors are seeking to convert restrictions that currently rely substantially on executive and regulatory action into a permanent statutory prohibition. The legislation would restrict Chinese-origin vehicles and connected vehicle technologies from the US market and limit the ability of future administrations to waive the restrictions.

A Collision Between Congress and Trump’s Approach to China

The legislative push has gained momentum as Trump has signaled a willingness to consider a different approach to Chinese auto manufacturing.

Earlier this month, Trump said he would be comfortable with Chinese automakers building vehicles in the United States, provided they employ American workers.

“If China wanted to come in and open a plant to build their cars here, I’d be okay with that,” Trump said in a Fox News interview.

He also said he did not want Chinese companies building cars in Mexico and exporting them into the United States.

That position has created a significant policy question for the legislation.

The Senate bill is designed to restrict Chinese vehicles and connected technologies across the production and sales chain. Its sponsors argue that allowing Chinese automakers to establish US manufacturing operations could still create national-security and economic risks if Chinese companies retain control of the vehicles, software, or data systems.

The bill was introduced by Moreno and Slotkin in April as the Connected Vehicle Security Act of 2026. It would prohibit the import, sale, and operation of vehicles manufactured in China or other countries of concern and restrict Chinese-developed connected-vehicle technologies, including software and data systems, on US roads.

The sponsors have framed the issue around two separate concerns: the security implications of connected vehicles and the competitive pressure Chinese automakers could place on US manufacturers.

Moreno has noted that China produces almost four times as many cars as the United States and that Congress must prevent American auto jobs from being placed at risk by Chinese companies.

Slotkin has been similarly direct about her position.

“I think if President Trump allows in these Chinese companies, it is beginning of the end of the auto industry in the United States,” she said.

Those are political arguments made by the bill’s sponsors, rather than established outcomes. The legislation itself is based on concerns about vehicle data, connected technologies and the competitive position of US automakers.

The auto industry’s position is clearer. Six major automotive trade groups representing automakers and suppliers recently urged Trump to maintain restrictions preventing Chinese automakers from selling, importing or manufacturing vehicles in the United States. The groups cited concerns over American jobs, national security, and the competitive advantages available to Chinese manufacturers.

The disagreement therefore goes beyond whether Chinese vehicles should be imported. It is more about whether Chinese companies should be allowed to establish manufacturing capacity inside the United States.

The Mercedes Problem

One of the most complicated elements of the proposed legislation involves ownership.

Senator Ted Cruz said earlier that the bill would prohibit companies with more than 15% ownership by Chinese entities from selling vehicles in the United States. That threshold could potentially affect Mercedes-Benz, given the nearly 20% stake held by Chinese investors.

Moreno has said Mercedes would have until 2030 to comply and could receive waivers where necessary. Slotkin said discussions over how Mercedes could comply were continuing.

The issue shows that drafted restrictions on Chinese ownership are broadly extending beyond Chinese-branded automakers.

Mercedes is a German company, but its ownership structure includes significant Chinese investment. A rule based on ownership rather than brand origin or manufacturing location could therefore affect multinational automakers with Chinese shareholders even if the vehicles themselves are designed, manufactured, and sold through established Western operations.

That could become an important issue as Congress considers how to define a “Chinese” vehicle or company in an industry where global ownership and supply chains are deeply interconnected.

From Tariffs to A Permanent Prohibition

The proposed legislation would build on restrictions already imposed by Washington.

The Biden administration introduced regulations in early 2025 that effectively barred Chinese automakers from selling or building passenger vehicles in the US based on concerns that connected-vehicle technologies could transmit sensitive data to China. The United States also maintains tariffs of more than 100% on Chinese electric vehicles.

Those measures have already made direct entry by Chinese EV manufacturers extremely difficult. The congressional legislation would make the restrictions more durable by placing them in statute and preventing the White House from simply reversing them or granting waivers to Chinese manufacturers.

The move has become necessary because executive policy can change with a new administration. A law passed by Congress would establish a much more durable barrier to Chinese automakers entering the American market.

The bill’s supporters are therefore attempting to settle the issue legislatively before the administration has the opportunity to negotiate a different arrangement with Beijing.

That urgency helps explain the timing of Thursday’s attempted fast-track vote. The effort was initially scheduled to coincide with Trump’s meeting with Xi, when the future of US-China trade policy was already under intense scrutiny. The decision to delay the vote means the legislation will now move into a week of negotiations with Paul while the outcome of the broader US-China discussions remains relevant to the political debate.

The Bigger Issue is Control of The US Auto Market

China’s emergence as the world’s largest vehicle manufacturing base has transformed the competitive landscape. Chinese manufacturers have expanded rapidly outside their home market, particularly in electric vehicles, batteries, and other automotive technologies.

US policymakers now face a question that is broader than conventional import competition: should Chinese companies be allowed to establish a direct manufacturing presence in the American market and compete from inside the country?

That question has become more complicated because modern vehicles are software-defined and connected. Cars can collect location, usage, and other information, communicate with external systems, and receive software updates remotely. Washington’s restrictions are thus partly rooted in the treatment of vehicles as connected technology platforms rather than simply manufactured goods.

The proposed legislation takes that concern further by targeting not only finished vehicles but also connected hardware and software associated with Chinese companies.