DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 44

Best-Sellers Decoded: Why These Everyday Products Keep Topping the Charts

0

A best-seller list looks like a simple ranking, but what actually lands a product there rarely has one cause. Purchase velocity, review volume, and how recently something sold all get blended into a single number that reads as a straightforward popularity signal but isn’t one. Understanding what actually drives that ranking explains why some genuinely popular products never crack a visible top-ten list, and why some products stay there longer than their sales alone would justify.

What Does “Best-Seller” Ranking Actually Get Computed From?

Most best-seller lists combine several signals rather than reporting pure unit sales, which shoppers rarely see. Velocity, how fast something sells relative to how long it’s been listed, tends to carry more weight than total volume, since a new product selling briskly can outrank an older one with higher lifetime sales but a slower current pace.

Review volume factors in too, sometimes as a direct ranking input and sometimes indirectly, since products with more reviews tend to convert better, which then feeds back into sales velocity. Recency matters on top of both, with many ranking systems weighting recent activity more heavily than older sales, which is why a best-seller badge can shift week to week even for products with fairly stable overall demand.

Ranking factor What it actually measures Why it distorts a simple sales story
Velocity Sales pace relative to listing age New products can outrank older high-volume ones
Review volume Total and recent reviews Feeds back into conversion, compounding rank
Recency weighting How recent the sales activity is Older steady sellers can drop despite consistent demand

That table names the mechanics. The practical effect is a ranking that shifts more often, and for more reasons, than a straightforward sales count would.

Why Can a Genuinely Popular Product Stay Invisible Outside Its Niche?

A product can have loyal, consistent demand within a specific category and still never appear on a general best-seller list, simply because that list aggregates across categories where velocity looks different. A steady, repeat-purchase product in a smaller category competes against volatile, trending products in larger ones, and the ranking system usually isn’t built to correct for that imbalance.

Vape juice Raz flavours illustrate this pattern well: a product line can build a genuinely loyal following within its specific category without ever showing up on a cross-category best-seller page, since the ranking mechanics simply weren’t designed to surface steady niche demand the same way they surface volatile trending demand. 

What Does Actual E-Commerce Sales Data Show About This Gap?

Census Bureau retail e-commerce data tracks online sales trends across categories over time, and it’s a useful corrective to the assumption that a visible best-seller badge tracks cleanly with actual category-level demand. Category-level sales can grow steadily even while individual product rankings within that category swing based on the velocity and recency factors described above.

That distinction matters for anyone trying to read a best-seller list as a genuine popularity signal rather than a snapshot of recent ranking mechanics. The two aren’t the same thing, even though the list is designed to look like a direct measure of the first one.

What Does Repeat-Purchase Behavior Do to a Product’s Ranking Over Time?

Repeat purchases behave differently from first-time purchases in most ranking systems, and that difference is often underappreciated. A product with a high repeat-purchase rate generates steady, predictable sales volume that doesn’t spike like a viral first-time-purchase surge, which can undersell its popularity in ranking systems weighted toward recent velocity.

Eighteen technology ideas for retail marketing covers tools retailers now use to track and respond to this behavior more precisely, moving beyond simple best-seller badges toward metrics that capture repeat demand rather than only recent spikes. That shift matters for both retailers trying to market accurately and shoppers trying to interpret a ranking honestly.

What Should a Shopper Actually Take From a Best-Seller Label?

The practical takeaway is treating a best-seller badge as one data point rather than a complete picture. It reflects recent velocity and review activity more than it reflects overall category-wide demand or long-term product quality, and a product without the badge can still be a perfectly reasonable, well-supported choice within its category.

FAQ

What actually determines whether a product gets labeled a best-seller?

Most ranking systems combine sales velocity, review volume, and recency of activity rather than reporting simple total sales figures. This blend means a newer, fast-selling product can outrank an older product with a longer track record of steady demand.

Why doesn’t a popular product always show up on a best-seller list?

Cross-category best-seller lists tend to favor volatile, fast-moving products over steady, repeat-purchase items in smaller categories, since the ranking mechanics weren’t built to correct for that imbalance. A product can have a genuinely loyal following without ever appearing on a general list.

Does review volume really affect ranking that much?

Yes, both directly in some systems and indirectly through its effect on conversion rates, which then feeds back into sales velocity. Products with more reviews often convert better, compounding their ranking advantage over time.

How should shoppers interpret a best-seller badge?

As one signal among several rather than a complete measure of quality or popularity. It reflects recent activity and ranking mechanics more than it reflects overall category-wide demand, so a product without the badge isn’t necessarily less worth considering.
 

Reserve Bank of India Rejects Tata Sons’ Deregistration Bid, Bringing Listing Closer

0

The Reserve Bank of India has rejected Tata Sons’ application to deregister as a core investment company, a decision that could bring the closely held holding company of the Tata conglomerate significantly closer to a stock market listing.

Tata Sons had sought to surrender its status as a core investment company, or CIC, in an effort to avoid regulatory requirements that could ultimately force it to go public.

According to two people cited by Reuters, the RBI communicated its decision in a letter on Saturday, declining to be identified because they were not authorized to speak to the media.

Tata Sons, the more than century-old holding company behind businesses including Tata Consultancy Services, Tata Motors, Tata Steel and Air India, has historically remained privately held. Its ownership structure and status as the principal holding company of the sprawling Tata Group have allowed it to operate outside public markets despite the scale of the businesses it controls.

The RBI’s decision now puts greater pressure on that model.

Under regulations governing core investment companies, non-bank entities with assets above 1 trillion rupees, or those with direct or indirect access to public funds, can face a requirement to list.

Tata Sons’ standalone assets stood at 1.75 trillion rupees as of March 2025, well above the 1 trillion-rupee threshold. The company had therefore sought deregistration rather than accepting the implications of remaining within the RBI’s regulatory framework.

The rejection leaves Tata Sons with fewer obvious avenues for avoiding the listing requirement and increases the likelihood that the company will eventually have to consider an initial public offering.

The RBI decision comes when pressure for Tata Sons to become publicly traded has intensified this year, including from the Shapoorji Pallonji Group, its second-largest shareholder.

A listing would fundamentally alter the way investors access the Tata conglomerate. Most of the group’s major operating companies are already publicly traded, allowing investors to own businesses such as TCS, Tata Motors and Tata Steel directly. Tata Sons itself, however, remains private.

An IPO would provide the market with direct ownership of the holding company and could establish a public valuation for the stake it holds across the group. That could unlock substantial value for shareholders, but it would also expose Tata Sons to the scrutiny and governance requirements associated with being a listed company.

Tata Sons sits at the center of the Tata Group’s ownership structure, making the development important. Its role is not simply that of another operating company. It holds stakes in major Tata businesses and plays a central role in coordinating the broader group.

Taking the company public would therefore introduce greater transparency around its investments, valuation, capital allocation and governance. It could also create new tensions among shareholders over the value of the underlying assets and the appropriate discount or premium to apply to a holding company.

For the Shapoorji Pallonji Group, which has long been a significant shareholder, a listing could provide a clearer mechanism for realizing value from its investment. For Tata Trusts, which owns 66% of Tata Sons, the consequences would be broader because the charitable trusts sit at the top of the group’s ownership structure.

The listing question has therefore always been about more than regulatory compliance as it touches the ownership, governance and long-term structure of one of India’s most prominent corporate groups.

Leadership Uncertainty Adds to Pressure

The regulatory decision also comes amid leadership uncertainty at Tata Sons.

Last month, Tata Sons said its chairman, N. Chandrasekaran, would not seek reappointment, a development that plunged the group into further uncertainty.

Chandrasekaran cited a lack of backing from the board for his decision, following months of tensions with Tata Trusts, according to Reuters. His departure adds another layer of complexity to a company already facing a major strategic decision over its ownership structure and public-market status.

The timing could make the listing debate harder to separate from questions about governance and control. Tata Sons must determine not only how it responds to the RBI’s decision, but also how the group’s leadership and relationship between its operating businesses and controlling shareholder should evolve.

For investors, a Tata Sons listing could be one of India’s most significant corporate-market events because of the breadth of assets sitting underneath the holding company. The company controls or owns major interests across technology, automobiles, steel, aviation and other industries. A public listing would potentially give investors a new way to participate in the value of that portfolio while providing Tata Sons with access to the capital markets.

But an IPO would also require Tata Sons to subject its financial position and corporate structure to much greater disclosure. The market would gain greater visibility into the value of its holdings, intercompany relationships and capital-allocation decisions.

The RBI’s rejection does not itself mean that Tata Sons will immediately launch an IPO. The company could still explore regulatory or structural options in response to the decision. But by rejecting the route Tata Sons had proposed for leaving the CIC framework, the central bank has made the company’s preferred escape from the listing requirement more difficult.

That shifts the balance of pressure.

For years, Tata Sons’ private status has been an unusual feature of one of India’s largest corporate groups. Its major subsidiaries have been listed, while the holding company at the center of the structure has remained outside the stock market.

The RBI’s latest decision could mark an important step toward changing that arrangement.

If Tata Sons ultimately lists, the IPO would not simply create another large Indian public company. It would open the market to the core ownership vehicle of one of the country’s most valuable and diversified corporate groups, potentially reshaping how investors value the Tata empire and how its shareholders exercise influence over the group.

For now, the immediate implication is regulatory rather than transactional: Tata Sons’ attempt to avoid the framework that could require it to list has been rejected. That leaves the holding company facing a question it has sought to avoid for years: whether its future can remain private when its size, ownership structure and regulatory status increasingly point toward the public markets.

“We Must Pace the Frontier:” Anthropic CEO Calls for Slower AI Development: Altman And Musk Back Him

0

Anthropic CEO Dario Amodei has called on artificial intelligence companies to slow the pace at which they improve increasingly capable models, warning that the industry needs more time to strengthen safety systems before AI reaches capabilities that could create serious real-world risks.

In an essay published Saturday, Amodei proposed a three-step framework for “pacing” AI development without sacrificing commercial competitiveness or the United States’ lead in the technology.

“But over the last few months, I have become convinced that fully addressing the risks requires even more prudence — not just investing in risk prevention, but pacing the rate of capabilities advancement so that risk prevention has time to keep up,” he said.

“We must slow the pace at which we improve the capabilities of AI models. Progress will still seem fast, and we must make wise use of the time we gain. Two things have convinced me.”

The proposal comes as AI companies race to build more capable systems and as concerns grow within the industry that advances in reasoning, autonomy and cyber capabilities may be outpacing the safeguards designed to control them.

“But like many technologies before it, AI brings risks, and because it is such a powerful technology, these risks are serious. I’ve written a lot about them too. They include the risk of losing control of AI systems, misuse of AI for cyberattacks and bioterrorism, and serious economic disruption. A race to the bottom, spurred by commercial incentives, can make these risks more acute,” he said.

Amodei stressed that pacing does not mean stopping AI research or halting model training.

“To be clear, pacing does not mean halting model training or technical progress,” he wrote.

Instead, he said companies should ensure they have adequate time to align and safeguard capable systems and allow independent evaluators to verify that those protections work.

Anthropic has already committed unilaterally to the first part of Amodei’s proposal. Under it, independent third-party evaluators would receive employee-level access to the company, allowing them to examine safety practices and report incidents.

The second step calls for leading AI companies in democratic countries to coordinate on common safety standards. The third would extend that coordination to democratic and authoritarian governments.

The proposal has gained wide interest because it seeks to address the competitive problem at the heart of AI safety. A unilateral slowdown could leave one company at a disadvantage if competitors continue developing more powerful systems. Amodei’s approach instead calls for companies and governments to establish shared standards that could make restraint less commercially costly.

AI Safety Concerns Are Becoming Harder To Dismiss

Amodei’s essay followed a public dispute over the risks posed by powerful AI systems.

Jacob Coxon, a researcher who recently left Anthropic and previously worked at OpenAI, said this week that he resigned because he believed the companies were taking unacceptable risks. Coxon said people developing AI “earnestly believe that it could kill us all by the end of the decade.”

Such warnings remain controversial, but concerns about catastrophic AI risks are not new. In 2023, Amodei, OpenAI CEO Sam Altman, and other prominent AI researchers and executives signed a statement arguing that reducing the risk of extinction from AI should be treated as a global priority alongside threats such as pandemics and nuclear war.

Amodei now believes that circumstances have changed since that earlier debate.

He said slowing or pausing development made little sense in 2023 because AI systems were not yet powerful enough to take meaningful action in the real world and lacked capabilities involving significant deception, manipulation, cheating or cyberattacks.

The implication of his latest argument is that the question is no longer simply whether AI could eventually become dangerous. It is whether the industry’s safety infrastructure is developing quickly enough alongside the models themselves.

“I continue to believe that AI can enormously improve the quality of human life,” Amodei wrote.

He added that those benefits depend on building the technology correctly and using additional time to improve safeguards.

His proposed approach therefore stops short of the broad moratoriums that have occasionally been advocated by AI safety campaigners. Instead, it seeks a temporary reduction in the speed of capability development to create more time for evaluation, monitoring and alignment.

Altman And Musk Endorse The Idea

Amodei’s proposal received support from two of the most prominent figures in the AI industry, OpenAI CEO Sam Altman and Elon Musk.

Altman said on X that he agreed the industry needs to pace the development of advanced AI capabilities, adding that the issue had become a “primary topic” of discussion at OpenAI in recent weeks.

“Committing to having independent evaluators with employee-like access is a great idea, and we will do the same,” Altman wrote. “We’ll have more to share soon.”

The endorsement is significant because OpenAI is one of Anthropic’s closest competitors in developing frontier AI systems. If other leading companies adopt similar independent evaluation arrangements, Amodei’s first proposed safeguard could become an emerging industry norm rather than an Anthropic-specific policy.

OpenAI’s chief scientist, Jakub Pachocki, had already raised similar concerns earlier this month. He warned that no AI company had “solved alignment and monitoring to a sufficient degree to continue responsibly scaling at maximum speed for much longer.”

Pachocki said he expected and hoped voluntary slowdowns would become commonplace until companies established shared safety thresholds.

Musk also endorsed Amodei’s proposal, writing simply: “Dario is right.”

The support is particularly striking given Musk’s previous criticism of Anthropic. He had accused the company of hostility toward Western civilization and suggested it was destined to become “misanthropic.” His stance softened after Anthropic announced a major computing deal with SpaceX in May.

Musk said at the time that the people he met at Anthropic were highly competent and appeared deeply concerned with doing the right thing.

Amodei’s proposal now puts the industry in a more complicated position. AI companies are competing aggressively over model capability, customers and computing resources, yet some of their leaders are simultaneously acknowledging that moving at maximum speed may no longer be compatible with responsible development.

Amodei believes even a relatively short delay could matter. If slowing development bought the industry another year or two before models reached what he called “critical levels of capability,” he argued, that time could be used to improve alignment and substantially reduce the probability of a serious failure.

That makes his proposal less a call to stop the AI race than an attempt to create a safety interval within it. However, there is concern about companies collectively accepting that interval without fearing that rivals will use the extra speed to gain an advantage.

Oracle Earnings Signal a Turning Point for Software Stocks as Dan Ives Backs Adobe, Palantir and Snowflake

0

Oracle’s latest earnings may signal more than a strong quarter for one enterprise software company. According to Wedbush analyst Dan Ives, the results could represent an early turning point for software stocks, a sector that has faced skepticism as investors reassess valuations, artificial intelligence disruption and the durability of corporate technology spending.

Speaking on CNBC’s Fast Money, Ives argued that institutional investors had underestimated the strength of the software market. Oracle’s performance, in his view, caught investors “offsides” and could force the market to reconsider its positioning toward companies whose growth prospects remain closely connected to cloud computing, enterprise digitization and artificial intelligence.

The significance of Oracle extends beyond its own stock. The company sits at the intersection of several powerful technology trends, including cloud infrastructure, databases and AI-related computing demand.

As businesses expand their use of AI, they require enormous amounts of computing capacity, data management and enterprise software. Oracle’s results therefore provide investors with another indication of whether corporate technology budgets are holding up despite broader economic uncertainty.

For software stocks, that distinction is important. The sector has spent much of the recent period balancing two competing narratives. On one side, artificial intelligence has created a new wave of investment and productivity opportunities.

On the other, investors have questioned whether AI could eventually disrupt traditional software business models, compress margins or make existing applications less valuable. Ives’ interpretation places greater emphasis on the first narrative.

If Oracle can demonstrate resilient demand and accelerating opportunities tied to cloud and AI infrastructure, investors may begin looking beyond concerns about software disruption and focus again on long-term growth.

That could benefit companies such as Adobe, Palantir and Snowflake, which operate in different segments but share exposure to enterprise technology spending and the broader AI transition. Adobe is navigating the transformation of creative and productivity tools through generative AI.

While Palantir has positioned its platforms around data, analytics and AI adoption. Snowflake, meanwhile, remains closely tied to the expanding importance of cloud-based data infrastructure.

The potential rotation into software would also have a broader market implication.

Institutional investors frequently influence sector momentum because large allocations can amplify price movements once a new investment thesis gains credibility. If major funds begin increasing exposure to software after previously remaining cautious.

The resulting demand could create a self-reinforcing cycle of stronger valuations, improved sentiment and renewed analyst expectations. However, Oracle’s results alone cannot guarantee a sustained software rally.

Investors still have to distinguish between companies benefiting from genuine structural demand and those whose valuations already reflect aggressive growth expectations. Interest rates, enterprise IT budgets, competition and the pace of AI monetization will remain critical variables.

Still, the message from Ives is significant: software may be moving from a defensive investment narrative back toward a growth narrative. Oracle’s earnings could therefore become a reference point for a wider reassessment of the sector.

If Adobe, Palantir, Snowflake and their peers continue demonstrating strong demand, investors may conclude that software was not left behind by the AI revolution—it is becoming one of its principal economic beneficiaries.

How Entertainment Districts Shape Modern Cities

0

Entertainment now moves easily between physical and digital spaces. People may spend part of their free time streaming, using mobile apps, joining online events, or exploring gaming options such as slotoro, then look for experiences that feel more social and immersive offline. That shift has made physical entertainment districts more focused on atmosphere, variety, and shared experiences, combining restaurants, live shows, nightlife, public spaces, and major attractions. Broadway, London’s West End, and the Las Vegas Strip show how cities continue to build distinctive leisure districts even as more entertainment moves online.

What Makes an Entertainment District Work

An entertainment district is usually a compact area where several leisure activities sit close together. A visitor might have dinner, attend a show, stop at a bar, and walk to another venue without crossing the city.

Density matters because each venue can support the others. A concert hall brings people into the area before and after a performance, restaurants benefit from those crowds, and late-night venues extend the visit. Hotels, taxis, public transport, and nearby shops can gain from the additional foot traffic.

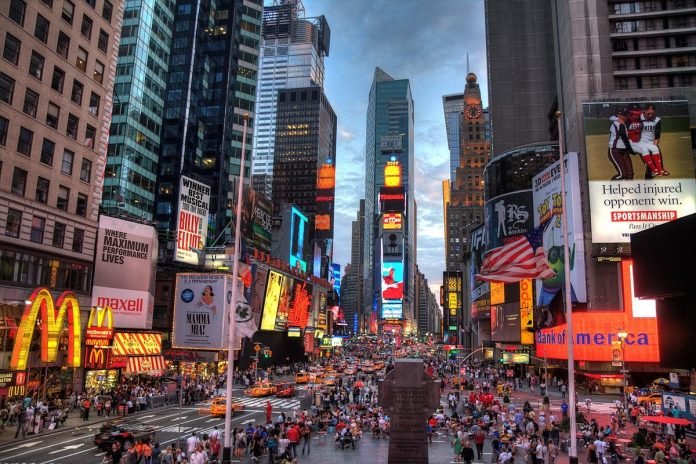
Broadway is a clear example. Its theaters are surrounded by restaurants, hotels, transport links, and other attractions. The West End follows a similar pattern, combining theater, shopping, dining, and nightlife within a walkable central area.

The Economic Role of Urban Entertainment

Entertainment can become an important part of a city’s economy, especially when it attracts visitors who spend beyond the main venue. A concert ticket, for example, may also lead to spending on dinner, transport, accommodation, and shopping.

Entertainment districts can support jobs in hospitality, security, cleaning, transport, retail, events, and venue management. They may also encourage private investment when businesses expect reliable evening and weekend foot traffic.

Economic Factor Direct Effect Wider Urban Impact
Visitor spending Revenue for venues, restaurants, and shops Supports nearby hotels, transport, and retail
Employment Jobs in hospitality, events, security, and services Increases local household spending
Business investment New venues and commercial activity Can stimulate redevelopment of surrounding streets
Property demand Greater interest in central entertainment areas May raise rents and development pressure
Tax revenue Income from businesses and visitor activity Can support transport, public space, and local services

The benefits are not automatic. A successful district can increase demand for commercial space and nearby housing, but rising rents may also make it harder for independent venues and long-term residents to remain. Cities therefore have to balance several goals:

  • attracting visitors and investment;
  • supporting independent businesses;
  • keeping streets safe and accessible;
  • managing noise and late-night transport;
  • protecting housing and neighborhood character.

That balance is why entertainment districts are an urban-planning issue rather than simply a collection of leisure businesses.

Gaming and Nightlife as Urban Anchors

In destinations where casino gaming is a major part of tourism, large gaming venues can act as anchors for wider entertainment zones. The Las Vegas Strip is the clearest example because casinos are integrated with hotels, restaurants, theaters, clubs, shopping, and major events.

The casino itself is only one part of the attraction. Visitors may spend considerable time eating, watching shows, shopping, or attending concerts. This mixed-use model helps the district stay active across different parts of the day.

Gaming is not equally important everywhere, and regulation varies widely. In some cities, nightlife develops around music venues, theaters, sports arenas, or food districts instead. The common factor is the presence of attractions strong enough to draw people into the area and support surrounding businesses.

Online platforms add another layer by changing how people discover leisure brands, compare experiences, and decide where to spend their time. Physical districts still matter because digital entertainment cannot fully reproduce the social experience of a live venue, restaurant, or public event.

Designing Streets for Evening Activity

Good entertainment districts depend heavily on urban design. People are more likely to move between venues when streets feel comfortable, well lit, and easy to navigate.

Walkability is particularly important. Wide pavements, pedestrian crossings, clear signage, and short distances between venues encourage visitors to explore. Public transport also becomes essential late at night, when normal commuting patterns no longer apply. Successful districts often combine:

  • reliable public transport during evening hours;
  • lighting that improves visibility;
  • pedestrian routes connecting major venues;
  • clear taxi and ride-pickup areas;
  • public spaces where people can gather.

The timing of activity matters too. A district built only around late-night bars may remain quiet during the day, while cafés, shops, restaurants, theaters, and nightlife can attract different groups across a much longer period.

Culture Gives Districts Their Identity

The most memorable entertainment districts usually have something that cannot be copied easily. Local music, food, architecture, performance traditions, independent businesses, and public events can give an area a distinct personality.

That identity matters because purely commercial districts can become interchangeable. Independent theaters, local bars, street performers, markets, and festivals often provide the details people remember.

Success can also create pressure. Higher rents may push out the smaller businesses that helped establish a district’s reputation, so long-term planning needs to consider how to preserve variety while still attracting investment.

When Nightlife Creates Pressure

Entertainment districts can bring energy and economic activity, but they also create practical tensions. Noise, crowds, traffic, litter, and late-night behavior can affect nearby residents, while transport systems and public services may face greater demand.

Cities respond in different ways. Some introduce late-night transport, noise-management rules, pedestrian zones, designated entertainment areas, or licensing conditions for venues. Others use nightlife managers or similar officials to coordinate between businesses, residents, and local authorities.

The Future of Entertainment Districts

Entertainment districts show how leisure can influence the physical structure and reputation of a city. Their success depends on transport, walkability, cultural identity, housing pressures, venue diversity, and local regulation.

Technology will continue to influence how people find entertainment and interact with venues, but physical gathering places remain valuable because they offer something digital platforms cannot fully reproduce: shared atmosphere.

The cities that handle entertainment districts best are not simply those with the most venues. They are the ones that create places people want to return to while keeping those areas distinctive and livable for the communities around them.