DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 44

CBN’s 350bp Rate Reset Reshapes Nigeria’s Monetary Policy With Mixed Expectations

0

The Central Bank of Nigeria has delivered its biggest interest-rate reduction in nearly two decades, cutting the Monetary Policy Rate by 350 basis points to 23% as easing inflation, stronger economic activity and improved macroeconomic stability give policymakers room to recalibrate monetary conditions.

The decision, announced Tuesday by CBN Governor Olayemi Cardoso after the Monetary Policy Committee’s 307th meeting in Abuja, reduced the benchmark rate from 26.5% and marked the second reduction this year. The new MPR is the lowest since February 2024, when it stood at 22.75%.

The scale of the move is significant by historical standards. The 350-basis-point reduction is the biggest cut since December 2006, when then-CBN Governor Charles Soludo reduced the benchmark rate by 400 basis points from 14% to 10%. The CBN subsequently implemented 200-basis-point reductions in 2007 and 2009.

The latest decision also comes after the CBN kept the MPR at 26.5% at its July meeting, making the size of the adjustment particularly notable.

Cardoso has sought to distinguish the decision from a conventional shift toward looser monetary policy. The CBN described the move as a “reset”, explaining that the recalibration is intended to make monetary policy more effective rather than signal an abandonment of its price-stability objective.

“The MPC emphasized that the recalibration of the corridor does not constitute a change in the current monetary policy stance, but rather an operational reset to enhance the effectiveness of monetary policy and support the transition to an inflation targeting framework,” Cardoso said.

The move is considered necessary because the central bank had increasingly faced a gap between its formal policy rate and the rates actually influencing financial markets.

“There is a clear disconnect between CBN’s Monetary Policy Rate (MPR) and effective market rates,” Cardoso said. “The MPR was 26.5% while the interbank rate stood around 22%, same as the standing deposit facility rate. Thus, the MPR became the de jure rate with the SDF rate as the de facto.”

The CBN said banks had increasingly used the Standing Deposit Facility rate in pricing financial transactions, weakening the transmission of monetary policy to the real economy. The latest reset therefore attempts to bring the official benchmark closer to the rates already prevailing in the financial system.

The immediate backdrop to the decision is the improvement in Nigeria’s inflation and growth indicators.

The MPC said headline inflation moderated for a third consecutive month to 15.39% in August 2026. Real GDP growth accelerated to 4.43% in the second quarter, while the composite Purchasing Managers’ Index reached 52.7%, providing further evidence of expanding economic activity.

The CBN said the moderation was occurring across major components of inflation rather than being driven by isolated temporary movements.

“The simultaneous moderation across major inflation components provides stronger evidence that underlying price pressures are easing rather than reflecting temporary movements in individual components,” the MPC said.

The committee also pointed to the combination of falling inflation and stronger output as evidence that the economy is entering a more balanced phase.

“Simultaneous strengthening of output and moderation in inflation is particularly significant,” the MPC said. “The coexistence of accelerating economic activity and broad-based disinflation suggests that recent macroeconomic adjustment is becoming more balanced, providing greater scope to recalibrate the monetary policy framework without abandoning the commitment to price stability.”

That is a major change in the policy environment from the period when the CBN relied on aggressive monetary tightening to contain inflation and stabilize the naira.

The MPC also cited sustained exchange-rate stability and improved inflation expectations as positive developments supporting the decision.

Rewane Warns of Pressure on The Naira

The biggest immediate concern surrounding the rate reset is its potential impact on the attractiveness of naira-denominated assets.

Bismarck Rewane, managing director of Financial Derivatives Company, described the move as a “jumbo cut” and warned that the size of the reduction could affect savings, investment flows and the exchange rate.

“So it’s a jumbo cut from 26.5% to 23%, 350 basis points is huge by any stretch of imagination. So that’s a big risk,” Rewane said in an interview with Channels Television.

The immediate foreign-exchange reaction was relatively muted. The naira traded around N1,387 to the dollar before briefly weakening to about N1,390 in the parallel market before returning toward N1,387.

The longer-term concern is that lower domestic interest rates could reduce the returns available to investors holding naira assets.

“Effect of a 1% rate cut, return on savings will fall by 0.12%. The stock market, potentially positive,” Rewane said.

He also said diaspora inflows could provide some compensation if foreign portfolio investment weakens.

“Diaspora flows will be a substitute for the foreign portfolio investments,” he said.

Rewane expects the naira could come under depreciation pressure, although he argued that the scale of any decline would depend on wider market conditions.

“…the Naira may depreciate, but not as much …, because the Naira fair value is about 1,150 Naira to a dollar,” he said.

The key issue is therefore not simply the nominal MPR, but the return investors receive after accounting for inflation and exchange-rate risk.

Rewane said the real rate of return had fallen from 11.1% to 7.61% following the rate reset.

“The real rate of return for investors here dropped from +11.1 to +7.61, it’s still very good for those who involve themselves in carry trade,” he said.

That still leaves Nigeria with a substantial positive real-rate differential, but the cushion is narrower than before.

Lower Rates Could Weaken Savings

The effect on domestic savings is another important part of the equation.

Nigeria needs higher domestic savings to deepen its financial system and provide a larger pool of capital for investment. Lower deposit and fixed-income returns could make saving less attractive if the decline in rates outpaces the improvement in household incomes and confidence.

Rewane warned that the country’s already-low level of national savings could come under additional pressure.

“Savings are a function of interest rates, very sensitive. You either save or you consume, but the amount, national savings is very low. So when you do this, it falls further,” he said.

He also warned that savers and investors could shift toward alternative assets if returns on naira instruments fall too far.

“The danger is that you may then begin to start to buy alternative assets. Which includes dollars, Bitcoin, we don’t know,” Rewane said.

This creates a policy balancing act for the CBN. Lower rates can support credit and investment, but excessively rapid declines in domestic yields could weaken the incentive to hold naira assets.

The fact that the CBN retained existing cash reserve requirements suggests that the rate reset is not an across-the-board removal of monetary restrictions. Commercial banks’ CRR remains at 45%, merchant banks at 16%, while the requirement on non-TSA public-sector deposits remains 75%.

Government Could Gain From Cheaper Borrowing

The fiscal implications may be among the most significant benefits of the rate reduction. Nigeria’s government has faced a substantial debt-service burden, and lower domestic interest rates could eventually reduce the cost of refinancing existing obligations and issuing new debt.

Rewane estimated that the Federal Government spends about N15.8 trillion on debt servicing.

“Government debt service, I think it’s important that we are spending about N15.8 trillion on debt service. By cutting this down sharply, the amount of money government is going to spend on debt service is actually going to reduce,” he said.

The benefit, however, will depend on how much of the CBN’s rate reduction is transmitted to government bond yields.

A lower MPR does not automatically mean that every government security will immediately become cheaper to issue. Investors will continue to assess inflation expectations, fiscal borrowing requirements, liquidity conditions, and the risk associated with Nigerian assets.

The rate reset nevertheless creates room for lower funding costs if the decline in the benchmark rate feeds through the yield curve.

Businesses Could See Funding Pressure Ease

The private sector is another major beneficiary if the reduction eventually translates into lower lending rates.

Jerry Igwilo, chief executive of Nisela Capital, linked the decision directly to the decline in inflation and the high cost of funding confronting Nigerian businesses.

“I think the inflation rate has consistently been dropping. So, that will allow them to give our people a little bit of relief. Now, that is actually the intention,” Igwilo said.

He connected lower interest rates to the government’s ambition of building a $1 trillion economy, arguing that companies need cheaper access to capital to expand.

“If you want to have a trillion-dollar economy, it also means that you have to do some certain things drastically to be able to support the economy… The only thing that central bank can do is to reduce interest rates. To say to businesses, we hear you. The cost of funding is very high. We hear you,” he said.

For companies carrying substantial naira debt, lower rates could reduce financing expenses and improve margins. Businesses could also find it easier to finance inventory, capital expenditure and expansion.

The transmission will not necessarily be immediate. Banks still have their own funding costs, liquidity requirements and credit-risk considerations, meaning the reduction in the MPR may not be passed through one-for-one to borrowers.

The effectiveness of the rate reset will likely depend heavily on whether commercial lending rates eventually move lower.

Equities Could Benefit

The stock market provides another transmission channel. Lower interest rates can make equities relatively more attractive compared with fixed-income instruments, while cheaper corporate borrowing can improve earnings for companies with significant debt.

Rewane said the relationship between interest rates and equity valuations could work in favor of stocks.

“If you are borrowing and you reduce that, then your margins will increase, and therefore your stock price will also increase, and that plays into the interest rates going to inverse relationship with equities,” he said.

The Nigerian stock market gained 0.18% following the announcement, according to the source material.

That initial market response is relatively small, but the broader effect could emerge over time as investors reassess the relative attractiveness of equities, government securities and bank deposits. For companies, the potential improvement in margins could be particularly relevant if the lower interest-rate environment coincides with continued economic expansion.

The rate reset also shifts some of the burden from monetary policy toward fiscal policy.

Rewane argued that monetary easing will have limited effectiveness unless government improves fiscal management and reduces leakages.

“I think the real issue is not coordination, it is to achieve fiscal consolidation, that is, you achieve price stability by blocking leakages. And so the fiscal authorities have their job cut out for them,” he said.

His argument is that lower interest rates cannot independently resolve Nigeria’s structural economic pressures. If government borrowing remains high, fiscal demand could offset some of the benefits of monetary easing. If fiscal pressures weaken confidence in the naira, the CBN could also find it more difficult to continue reducing rates.

Rewane noted that the CBN’s easing cycle had taken the MPR from 27.25% in September 2024 to 23%, a cumulative reduction of 4.25 percentage points, while inflation had fallen by about nine percentage points over the same period.

That divergence provides the central bank with a stronger case for recalibration, but it also raises the question of how much further rates can fall without changing investor behavior.

The Real Test Is Monetary-Policy Transmission

The significance of the 350-basis-point reset ultimately rests on whether the CBN can make monetary policy more effective. The central bank’s own explanation points to a problem that had developed during the tightening cycle: the formal MPR no longer adequately represented the rate conditions influencing financial markets.

With the MPR at 26.5% while the interbank and SDF rates were around 22%, the official benchmark had become increasingly detached from the rates at which banks and investors were operating.

The reset is intended to close that gap and support the CBN’s transition toward inflation targeting.

But the risks are equally clear.

A faster decline in yields could weaken the incentive to hold naira assets. If that leads to stronger demand for foreign currency, the exchange rate could come under pressure. If the naira weakens materially, imported inflation could return and limit the room for further easing.

That is why the CBN’s characterization of the decision as a “reset” matters. The central bank is not presenting the move as the beginning of unrestricted monetary loosening. It is attempting to align the policy rate with market conditions at a point when inflation is falling, and economic activity is strengthening.

Thus, the 23% MPR marks a new phase in Nigeria’s monetary-policy cycle. The country has moved from the aggressive tightening that followed the inflation and foreign-exchange shocks of the previous years toward an environment in which policymakers can begin testing the benefits of cheaper capital.
AI’s Criminal Arms Race Is Becoming a Governance Problem

0

Artificial intelligence is becoming one of the most useful tools in finance—and one of the most efficient tools for criminals.

According to TRM Labs, criminal use of AI rose 40% over the past year, reflecting how quickly scammers are incorporating the technology into increasingly sophisticated attacks.

The development points to a broader transformation in digital crime: the problem is no longer simply that criminals have better tools, but that those tools can operate at scale.

For years, online scams depended heavily on human effort. A fraudster might manually contact potential victims, construct convincing messages, impersonate a company executive or search for information that could make a scam more believable.

Generative AI changes the economics of that process. It can produce personalized messages, imitate communication styles, translate languages and automate repetitive interactions, allowing relatively small operations to target far more people.

Crypto markets are particularly exposed because transactions can move rapidly across borders and, once completed, can be difficult to reverse. A convincing phishing message or fabricated investment opportunity can therefore become a financial event within minutes.

AI does not necessarily create entirely new forms of fraud; instead, it can make existing techniques cheaper, faster and more convincing.

That creates an uncomfortable symmetry for cryptocurrency exchanges. The same technology being used to attack financial infrastructure is increasingly being deployed to defend it.

Exchanges can use AI and machine-learning systems to identify unusual transaction patterns, flag suspicious accounts, detect coordinated activity and prioritize investigations.

But this introduces another layer of risk. When an exchange relies on automated systems to identify potentially criminal behavior, the quality of those systems becomes part of the security architecture.

A model can produce false positives, miss sophisticated attacks or react incorrectly to unusual but legitimate behavior. In a financial environment, an error is not merely technical. It can mean a delayed withdrawal, a frozen account or a legitimate transaction being treated as suspicious.

This is where governance becomes as important as detection. KuCoin’s acquisition of ISO/IEC 42001:2023 certification for its AI management system illustrates the emerging focus on that problem.

The international standard addresses how organizations establish governance around artificial intelligence, including responsibilities, processes and oversight. Its significance is therefore different from a claim that an AI system will always make the correct decision.

An AI management certification cannot guarantee that an automated fraud-detection model will never make a mistake. What it can provide is a framework for asking whether an organization has established procedures for managing those risks.

Who is responsible when an AI system produces an erroneous result? How are models reviewed? How are failures documented? Can decisions be challenged? And how does an organization respond when criminals adapt to the system?

These questions will become increasingly important as AI becomes embedded in financial infrastructure. The next phase of crypto security may therefore involve an arms race between automated offense and automated defense.

Criminal groups can use AI to increase the volume and sophistication of attacks, while exchanges can use AI to process enormous quantities of transactions and identify anomalies that humans could not efficiently detect.

The decisive issue may not be whether AI is used, but whether its use is governed responsibly. As artificial intelligence becomes part of the machinery protecting billions of dollars in digital assets, transparency, accountability and human oversight are becoming security controls in their own right.

The technology can detect threats, but governance determines what happens when the technology itself becomes wrong.

Wall Street’s Earnings Test Meets the AI Agent Monetization Question

0

As another earnings season approaches, Wall Street is entering a familiar but increasingly complicated phase: investors must decide whether lofty expectations for corporate growth are actually supported by earnings.

While simultaneously trying to understand where the next generation of artificial intelligence businesses will generate durable revenue. Morgan Stanley has highlighted more than a dozen stocks it is watching closely heading into earnings season.

Reflecting a market where expectations have become almost as important as the reported numbers themselves. For investors, the question is no longer simply whether companies can beat quarterly estimates.

It is whether management teams can demonstrate that current valuations are supported by sustainable demand, improving margins and credible growth.

That distinction matters particularly for technology companies. The artificial-intelligence boom has already produced enormous gains for chipmakers, cloud providers and software companies supplying the infrastructure behind increasingly sophisticated models.

But earnings season can expose the difference between capital expenditure and actual economic returns. Companies may be spending heavily on AI because they fear falling behind competitors.

Yet investors need evidence that these investments can translate into higher productivity, stronger pricing power, new customers or entirely new revenue streams.

That leads directly to another question highlighted by Goldman Sachs: How will AI agents actually make money? AI agents represent a potential shift from today’s chatbot economy.

Instead of simply answering questions, agents are designed to perform tasks: conducting research, managing workflows, writing software, arranging transactions or interacting with other digital systems.

If that vision becomes commercially viable, the economic model could move beyond subscriptions and toward transaction-based or outcome-based payments. An agent that completes a business process could potentially be paid according to the value or volume of the work it performs.

A sales agent might generate revenue through completed transactions. A coding agent could be priced according to software development output. A financial agent might eventually execute permitted services and receive fees associated with those activities.

But monetization remains unresolved. The challenge is that AI agents could also place enormous pressure on existing software businesses. If one agent can replace several software interfaces, customers may become less interested in paying for dozens of separate applications.

Instead, they could pay for an intelligent system capable of completing the underlying task. That would fundamentally change the economics of software. For public markets, earnings season therefore becomes a test of two related narratives.

The first concerns whether today’s AI spending is producing measurable financial returns. The second concerns whether tomorrow’s AI products can establish business models capable of capturing those returns.

Morgan Stanley’s stock watchlist and Goldman’s focus on agent monetization point toward the same underlying issue: AI enthusiasm eventually has to become an income statement reality. Investors will be watching revenue growth, margins, capital expenditure, guidance and customer demand for clues.

Meanwhile, the AI industry is still experimenting with how autonomous systems should be priced and what customers will actually pay for. The market may have already priced in much of the technological promise.

The harder task now is identifying the economic architecture that converts that promise into recurring cash flow. This earnings season, therefore, is not merely about who beats estimates. It is increasingly about whether the companies building the AI economy can prove that intelligence itself can become a scalable business.

What Crypto to Buy Now? BlockDAG’s $0.03 USDT Buyback Opens as Zcash Holds $1,506 and Hyperliquid Crosses $97

0

Two things are on every serious crypto buyer’s radar on September 23, 2026: where the market is moving and where the next clean entry is. Zcash is holding above $1,506 after a 21Shares ETP launched on Euronext Amsterdam and Paris, adding regulated European access to a token already backed by a Grayscale ETF with over $233 million in inflows. Hyperliquid crossed $97.46 on $429 million in year-to-date on-chain protocol revenue and a new Layer 2 testnet going live.

And BlockDAG just handed holders a calculation they can run in seconds: a $0.03 USDT Buyback Price, 1.5 times the previous rate of $0.02, live for 7 days only, with direct BDAG available at $0.00000017 and both Legacy and New BDAG purchases counting toward your eligible Buyback Allocation. For anyone deciding what crypto to buy now, the dashboard has the number. The window has a deadline.

BlockDAG (BDAG): The USDT Figure on Your Dashboard Is Not the Finish Line. It Is the Starting Point.

Most presale projects measure success by what they raise. BlockDAG is measuring something different right now: whether holders can see exactly what they own, in dollar terms, before they decide what to do next.

BlockDAG has finalized a new structure that allows the USDT Buyback to move forward under updated requirements. The previous buyback price was $0.02. For the next 7 days, that price has been raised to $0.03, and every eligible BDAG purchase made during this window builds toward that buyback rate. The path is: buy direct BDAG at $0.00000017, accumulate eligible Legacy BDAG and New BDAG, and let the dashboard calculate your USDT Buyback Balance automatically. Eligible BDAG goes through compression to a final eligible Buyback Allocation, priced at $0.03. One balance. Everything in one place.

At $500 invested at the current direct price of $0.00000017, a buyer receives approximately 294 billion BDAG. The dashboard then shows what that allocation is worth in USDT Buyback terms at $0.03. The math is not hidden. It is the first thing visible when you open the dashboard.

The previous eligible Buyback amount is already back in every verified holder’s USDT Buyback Balance. Legacy BDAG and New BDAG are consolidated under a single figure, no separate calculations, no split positions. USDT Buyback settlements will be processed in batches under the updated regulatory and compliance structure, with additional processing time required as each batch is completed.

The best crypto to buy today is rarely the one with the most complex pitch. Here, the path is four steps on your screen: buy BDAG, build allocation, get $0.03 buyback price, check balance. The 7-day window decides how much time you have to take it.

Zcash (ZEC): European ETP and ETF Split Expand Institutional Access

Zcash is holding above $1,506 as of September 22–23, 2026, up 3.1% in 24 hours, per CoinMarketCap data. The token’s institutional infrastructure expanded on two fronts this week. 21Shares launched a physically backed Zcash Exchange Traded Product on Euronext Amsterdam and Paris, opening regulated access to ZEC for European investors through standard brokerage accounts.

Separately, Grayscale announced a 3-for-1 forward split on its Zcash Trust ETF, effective September 30, following inflows exceeding $233 million, the split lowers the share price to improve retail accessibility without changing the underlying fund value.

Analyst targets for ZEC sit in the $1,770–$1,884 range, with the Cypherpunk Technologies board appointment of mining veteran Amanda Fabiano adding an infrastructure signal to the narrative. ZEC’s combination of ETF inflows, a new European ETP, and a quantum-proof protocol upgrade scheduled for November 2026 keeps it in the what crypto to buy now conversation for investors focused on privacy assets with institutional backing.

Hyperliquid (HYPE): $429M in Protocol Revenue and a New Layer 2 in Testing

Hyperliquid reached $97.46 on September 22–23, 2026, up 3.37% in 24 hours, per CoinMarketCap data, with social dominance hitting its highest point of 2026. The number that underpins the price is $429 million, on-chain protocol revenue generated through mid-September, outpacing every other crypto protocol by a measurable margin. That is recorded output, not a projection.

The new development this week is the Kinetiq Elysium testnet launch, a Layer 2 built on Hyperliquid targeting 300 million gas per second, with HYPE as the native gas token. HYPE-specific ETFs attracted $2.82 million in net inflows, primarily into the 21Shares THYP fund. A protocol generating $429 million in revenue while simultaneously launching Layer 2 infrastructure and pulling ETF inflows is doing three things at once that most tokens never manage individually.

Last Say

Zcash is stacking institutional access on two continents, a European ETP, a Grayscale ETF split, a quantum upgrade in November, and holding $1,506 while it does it. Hyperliquid has $429 million in real protocol revenue, a Layer 2 in testing, and $97 as the current floor.

BlockDAG is doing something neither of them is: raising its USDT Buyback Price from $0.02 to $0.03 for a 7-day window, with direct BDAG at $0.00000017 and a unified balance that covers Legacy and New BDAG automatically on your dashboard. What crypto to buy now is a question with strong answers across all three this week. The one with a 1.5x buyback uplift and a 7-day countdown is the one that requires a decision before the others do.


Presale: https://purchase.blockdag.network

Website: https://blockdag.network

Telegram: https://t.me/blockDAGnetworkOfficial

Discord: https://discord.gg/Q7BxghMVyu

Vintage Family Photo Prompts for a Natural Film Look

0

A convincing vintage family portrait begins with how the people relate to one another. The faded colors can come later. For an imagined family scene, an AI image generator lets you describe a shared glance, familiar clothing, and the light across a porch or living room. Those choices give the picture its character before you add a film-like finish.

Natural Expressions Start With a Shared Moment

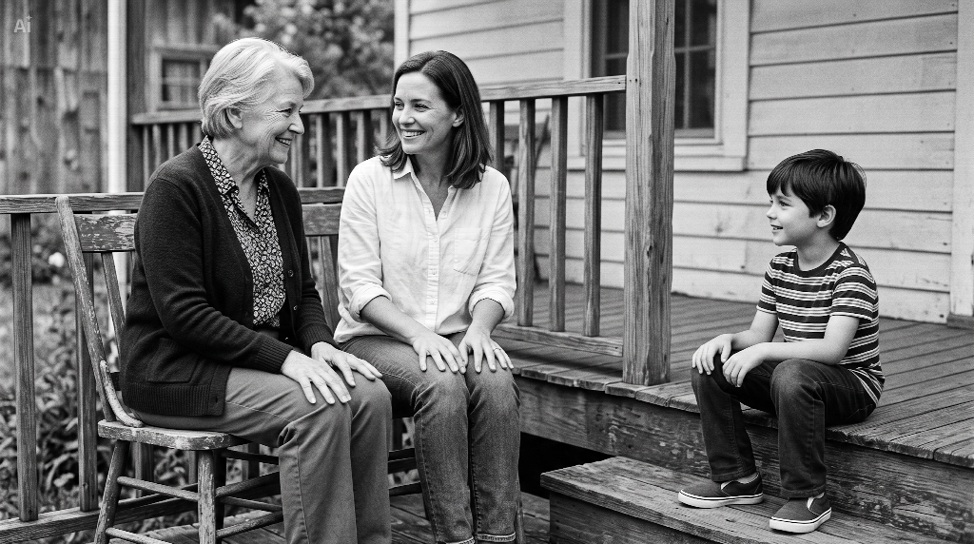
In the porch portrait, the adults exchange a smile while the child looks toward them. Their different lines of sight make the group feel connected without requiring everyone to face the camera. The setting is modest enough to remain part of the moment rather than competing with it.

Write the relationship into the action. “A grandmother and her adult daughter share a quiet smile as a child listens” is more useful than “a happy family.” It establishes who is responding to whom. You can also choose a more reserved moment, such as siblings sitting close together and looking toward someone outside the frame.

Specify the number of people and where each sits or stands. With three subjects, placing the child slightly lower can create a readable arrangement of faces. Keep the hands in simple positions on laps or knees, especially when several bodies overlap. Avoid giving every person a separate activity that needs its own set of props.

A Few Period Details Are Enough

Choose a broad period before describing clothing and surroundings. For an understated 1980s-inspired portrait, plain cotton shirts, a knit cardigan, and a weathered porch can establish the direction without turning the family into costume characters. Use differences in fabric and tone to distinguish people while keeping their outfits plausible together.

The background should agree with that choice. A modern phone in someone’s hand can interrupt the intended period more quickly than subtle grain can establish it. Ask for a simple setting with only the details you need. You do not have to fill the frame with recognizable vintage objects.

Be equally selective about aging effects. Heavy scratches, torn borders, and strong yellowing describe the condition of a damaged print. If the goal is a natural family photograph, begin with an intact image and restrained texture. The expressions should remain easier to see than the effect applied over them.

One Prompt for a Relaxed Porch Portrait

Open CapCut’s AI image generator and use a complete scene description rather than entering only “vintage family photo.” CapCut supports creating images from text, so an invented group is a straightforward starting point. Describe the people first, then their arrangement and the photographic treatment.

Create a horizontal, photorealistic black-and-white family portrait with a subtle 1980s film-photo feeling. Show exactly three fictional people on a covered wooden porch: a silver-haired grandmother in a dark cardigan, her adult daughter in a light cotton blouse, and a young boy in a striped shirt seated on a lower step. The adults exchange a relaxed smile while the boy looks toward them. Keep all faces visible, with natural age differences and hands resting separately on their own knees. Include weathered boards and plain house siding. Use soft open-shade daylight, gentle highlights, clear midtones, and fine grain. Keep skin texture natural. No additional people, pets, modern devices, lettering, scratches, or decorative border.

The clothing contrast has a practical role in this monochrome version. A light blouse separates the daughter from the darker cardigan beside her. If two people blend together, change one garment’s tone before asking for stronger contrast across the entire picture.

Warm Color Changes the Feeling of the Room

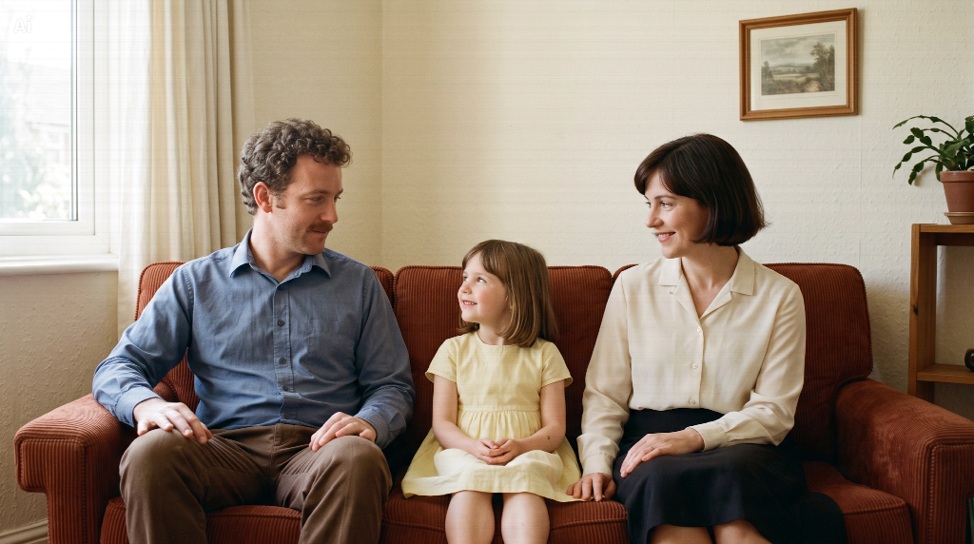
A muted color version can draw attention to the home as well as the faces. A rust-colored sofa and softly colored clothes give the room warmth, while a side window keeps the lighting connected to a visible part of the setting. The family still needs a shared moment; color alone cannot supply that interaction.

To explore this direction, replace the porch description with a simple living room and choose a quiet exchange on the sofa. Ask for warm, restrained colors with believable skin tones. Keep the shadows neutral enough that dark hair and clothing remain distinct. Avoid requesting an orange cast over the whole image.

Use this adaptation for the tone and setting: “An early-1980s-inspired living room with a rust-colored fabric sofa. Two parents sit with their child between them, exchanging relaxed glances. Soft daylight enters from a side window. Use muted warm colors, gentle contrast, and fine film-like grain, with clear facial features and no distressed-print effects.”

This is a separate imagined family scene, so you can change the people and their arrangement along with the room. If you instead want to work from your own family photograph, use a reference you have permission to upload and specify which expressions and relationships you want to retain.

A Shared Laugh Can Replace a Formal Pose

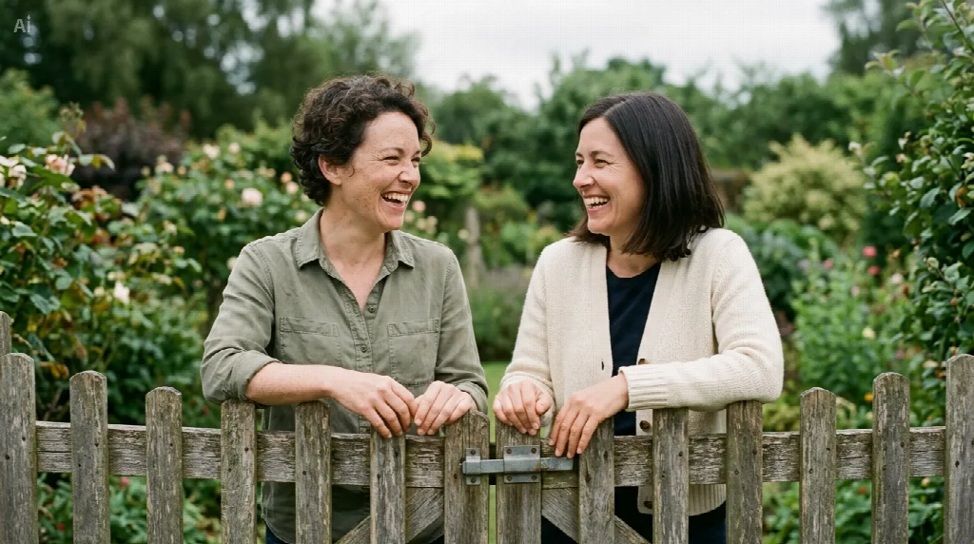
A portrait of adult siblings can feel familiar without including a whole household. Here, two imagined sisters lean on a garden gate and laugh toward each other. Their faces, shoulders, and resting hands belong to the same small exchange. The fence gives their arms a natural place to settle, while the softened foliage keeps attention on the expressions.

This is a different kind of moment from the quieter porch and sofa scenes. Describe the instant during the laugh, not a sequence of talking, turning, and laughing. Let the two expressions differ slightly; matching smiles and identical head angles can make an otherwise informal arrangement feel posed.

To try a late-1970s-inspired outdoor variation, specify two adult siblings beside a weathered gate, simple cotton and knit clothing, and soft overcast light. Ask for restrained color and faint grain rather than a yellowed finish. Keep their hands below their faces so the eyes and mouths remain unobstructed. You can suggest closeness through inward-facing shoulders and shared attention without adding an embrace or extra objects.

Film Grain Should Not Hide Facial Details

When reviewing a result from an AI photo generator, first look at the group from normal reading distance. Can you follow who is looking at whom? Are the ages, seated heights, and body positions believable? Then enlarge the faces and hands. Texture should not hide those details.

For a focused adjustment in CapCut, describe the change in relation to the image: “Reduce the grain over the faces while keeping the soft monochrome tones,” or “Keep the warm sofa, but make the skin tones less orange.” Inspect the revised result before changing anything else. Download the version whose expressions still feel natural when the image is viewed small.

Summary

Vintage family portraits feel personal when the interaction is clear and the period details stay understated. Start an imagined scene with CapCut’s AI image generator, then choose soft monochrome or restrained warm color. Keep the film texture subtle enough for the family to remain the focus.