

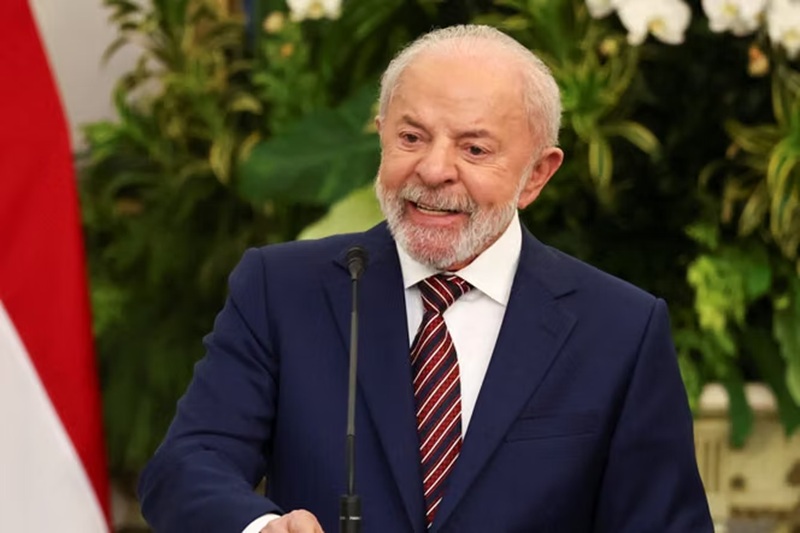
Brazil’s presidential election is setting up a sharp divide on Wall Street, with investors expecting markedly different outcomes for the country’s currency, bonds and equities depending on whether leftist Luiz Inácio Lula da Silva or right-wing candidate Flávio Bolsonaro emerges victorious.
The first round of voting took place Sunday, with neither candidate currently assured of securing the 50% threshold needed to avoid a runoff. If no candidate wins a majority, the election will go to a second round on October 25.
“The Brazil trade is: Does Lula win or does Bolsonaro win?” said Fernando Marengo, chief economist at Black Toro Global Investments.
Register for the next Tekedia Mini-MBA.
Register for Tekedia AI in Business Masterclass.
Join Tekedia Capital Syndicate and co-invest in great global startups.
Lula, 80, is seeking a fourth presidential term, while Bolsonaro, 45, is the son of former President Jair Bolsonaro and is running on a more fiscally conservative platform. The stark market reaction to the race reflects a broader concern about Brazil’s deteriorating fiscal position and the extent to which the next government will be willing and able to address it.
In broad terms, Wall Street expects Brazilian assets to perform better under a Bolsonaro victory, largely because investors anticipate a stronger commitment to fiscal discipline and structural reforms.
Brazilian stocks have already moved higher as Bolsonaro gained ground in opinion polls in recent months. JPMorgan said in a recent note that the MSCI Brazil index “rose by 0.25% on average each day that Flavio gained in the polls.”

Prediction markets have gone even further in favoring Bolsonaro, although their reliability as a measure of Brazilian voter sentiment is limited. Kalshi markets show Bolsonaro with a 60% probability of winning compared with 39% for Lula. Prediction markets are prohibited in Brazil.
Richard Lapper, senior adviser at Aurora Macro Strategies, said the balance had shifted toward Bolsonaro over the past month but cautioned that the move had not been nearly as large as prediction markets suggest.
“The balance has shifted toward Flavio over the past month, but not nearly as far as the prediction markets are pricing,” Lapper said.

The market preference for Bolsonaro is closely tied to fiscal policy. Brazil’s debt-to-GDP ratio has risen to 81.9%, about 10 percentage points higher than when Lula took office, increasing pressure on the next government to demonstrate that public finances can be stabilized.
Leonardo Porto, Brazil head economist at Citi, estimates that Brazil needs a fiscal adjustment of between 3% and 3.5% of GDP to stabilize public debt.
“We need a 3-3.5% fiscal adjustment to stabilize the public debt in relation to GDP,” Porto said. He added that the adjustment cannot rely on temporary measures such as privatizations. “Brazil needs a permanent fiscal adjustment.”
That would be difficult for any government to deliver.
About 90% of Brazil’s federal budget is composed of mandatory spending, with some obligations embedded in the constitution. At the same time, the country already has the highest tax burden in Latin America at about 32%, according to the OECD, leaving limited political room to rely solely on higher taxes.
The fiscal challenge is therefore likely to involve difficult decisions over spending, taxation and entitlement programs, while the economy faces relatively weak growth prospects.
Reform Expectations Drive The Market Divide
Investors are looking to Bolsonaro’s father for evidence of how markets could respond if the younger Bolsonaro were able to implement a substantial reform program.
During Jair Bolsonaro’s presidency, pension reform was passed that JPMorgan estimates saved hundreds of billions of dollars. The legislation established minimum retirement ages of 65 for men and 60 for women, replacing a system that allowed retirement after 35 years of contributions for men and 30 years for women regardless of age.
The previous system resulted in average retirement ages of about 56 for men and 53 for women. During that reform period, JPMorgan said Brazil’s two-year government bond yield fell to almost 4.7%, while the equity market rose 130%.
The historical comparison is driving some of the more bullish scenarios for Brazilian assets if another period of reform follows the election. JPMorgan estimates that interest rates could eventually decline toward a neutral level of about 6% in real terms, or roughly 10% nominally.
Under that scenario, the firm sees potential upside of between 21% and 41% for the MSCI Brazil index. A successful reform cycle could also lead to a significant expansion in equity valuations, with the forward price-to-earnings ratio potentially rising from about 8.6 currently to 13.3, a level last reached in 2020.
The currency market could also produce a sharp divergence between the two political outcomes.
JPMorgan describes the potential exchange-rate response as “bimodal,” forecasting the dollar at around 5.50 reais if Lula wins and 4.90 reais if Bolsonaro wins.
The gap reflects more than a simple political preference. A stronger fiscal framework could reduce the risk premium demanded by investors to hold Brazilian assets, supporting the real while lowering borrowing costs and improving equity valuations.
But markets may already have anticipated part of that outcome.
Marengo noted that recent victories by pro-business candidates elsewhere in Latin America have triggered significant gains across stocks, bonds and currencies. In Colombia, he said, the country’s risk premium compressed by about 200 basis points, while equities posted some of the region’s strongest gains. Peru experienced a similar market reaction.
The Brazilian market, however, has already been moving in anticipation of a Bolsonaro advance, meaning the eventual rally could be smaller if investors have already priced in a meaningful portion of the expected reform premium.
The election also extends beyond the presidential contest. Voters will determine the entire lower house and one-third of the upper house, making the composition of Congress a critical variable for whoever wins the presidency.
A president promising fiscal reform would still need sufficient congressional support to pass legislation. That makes the legislative results potentially as important to investors as the presidential vote itself. A Bolsonaro victory accompanied by a fragmented or opposition-controlled legislature could limit his ability to implement the reforms underpinning the market’s bullish scenario.
Likewise, a Lula administration could face pressure from markets if investors interpret its fiscal policy as insufficient to stabilize debt, particularly given the country’s already elevated interest burden.
There are also risks that extend beyond Brazilian politics.
As with other emerging markets, higher global interest rates could reduce the attractiveness of Brazilian assets by increasing the return investors can earn in developed markets and raising the country’s external financing costs. For Latin America, weather is another important variable. A strong El Niño could damage agricultural production, affecting one of the region’s important export sectors and adding another source of economic volatility. That leaves Brazil facing a market reaction that could be unusually sensitive to both the presidential and congressional results.
However, a Bolsonaro victory is expected to initially trigger a rally in the real, government bonds and equities as investors price in the prospect of fiscal reform and lower risk premiums. But analysts say sustaining that rally would depend on congressional support and the government’s ability to turn reform promises into durable changes in spending and public finances.
Additionally, a Lula victory is expected to force markets to reassess those expectations, particularly if investors conclude that fiscal consolidation will be slower or less ambitious.
With the election increasingly being treated as a referendum on Brazil’s fiscal trajectory, the next president’s ability to control debt and build legislative support may matter more to asset prices than the campaign rhetoric itself.