Home Blog Page 10

Huawei Launches Mate 90 Series, Putting Homegrown Chips and HarmonyOS at the Center of Its Smartphone Fight

0
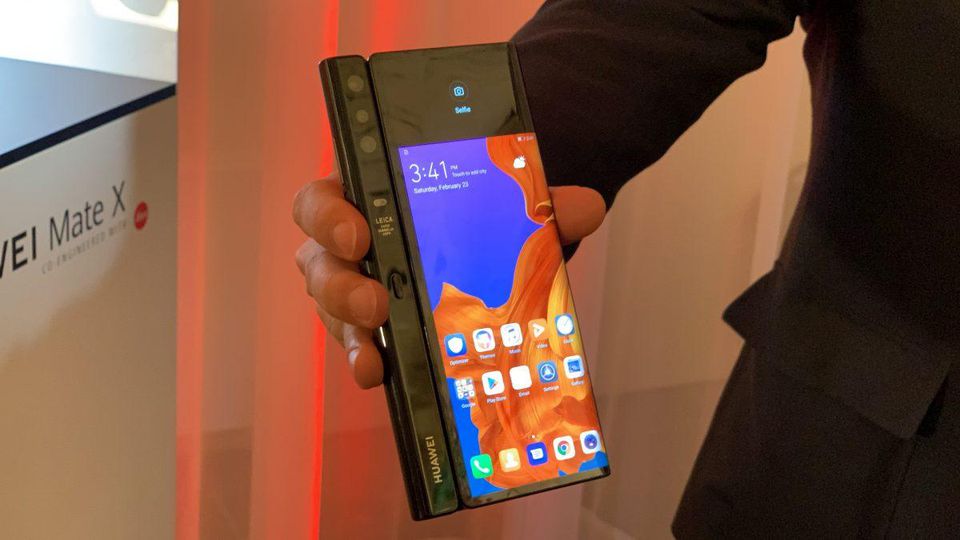
Huawei Mate X

Huawei Technologies is leaning harder on its homegrown chip architecture and operating system with the launch of its Mate 90 smartphone series, as the Chinese technology giant tries to sustain its premium handset comeback while U.S. restrictions continue to constrain access to advanced semiconductors.

The new Mate 90 series, unveiled Thursday, represents another test of Huawei’s ability to improve smartphone performance without unrestricted access to the world’s most advanced chipmaking equipment. The company is responding by redesigning the architecture of its processors, increasing reliance on domestic semiconductor capacity and expanding its Android-free HarmonyOS ecosystem.

Huawei consumer business chief Richard Yu said the company continues to face significant constraints in obtaining advanced chips, underscoring the extent to which semiconductor manufacturing capacity remains a bottleneck for China’s technology industry.

“Advanced semiconductor capacity remains very limited in China, and Huawei’s Ascend AI chips also draw on that same capacity,” Yu said ahead of the launch.

“The capacity for smartphone chips remains tight, even though rising smartphone prices have curbed shipment volumes (for handsets).”

The Mate 90 succeeds the Mate 80, which Huawei launched in November 2025. The premium models, including the Mate 90 Pro Max, use Huawei’s Kirin 9050 Pro system-on-chip, built using a technique the company calls “LogicFolding.”

Rather than arranging chip wiring predominantly in a conventional two-dimensional layout, LogicFolding restructures parts of the design in three dimensions. Huawei says the approach allows greater density and faster processing, although it requires more wafers to manufacture each chip.

That trade-off shows the increasingly unconventional path Huawei is taking to improve computing performance under U.S. technology restrictions. When access to leading-edge manufacturing tools is constrained, performance gains can come not only from smaller process nodes but also from architecture, packaging and design techniques that extract more capability from available manufacturing capacity.

Huawei has not disclosed the manufacturer of the Kirin 9050 Pro. Semiconductor Manufacturing International Corp., China’s largest logic chip foundry, is widely believed to manufacture the Kirin processors used in Huawei’s Mate smartphones as well as its Ascend AI processors.

The constraint is not limited to consumer electronics. Huawei rotating chairman Eric Xu said last month that production of the company’s Ascend 950 artificial intelligence processors was unable to meet domestic demand because of limited manufacturing capacity.

Yu said Chinese chipmakers still rely on deep ultraviolet, or DUV, lithography for advanced semiconductor production. He described extreme ultraviolet, or EUV, lithography as valuable while acknowledging that Chinese manufacturers are still working toward the technology.

Huawei plans to use more chips based on its LogicFolding architecture in future smartphones, Yu said.

That suggests the technology could become more than a one-generation workaround. If Huawei can repeatedly improve processor performance through architectural changes while domestic foundries gradually expand their manufacturing capabilities, the company could reduce some of the performance gap created by restrictions on advanced semiconductor equipment.

But the approach also highlights the limits of China’s current semiconductor ecosystem. A design innovation cannot by itself remove wafer shortages or manufacturing constraints. More complex architectures can increase the number of wafers required, potentially making each incremental improvement more expensive to produce.

Huawei is also using software to reduce its dependence on foreign technology.

The Mate 90 runs HarmonyOS 7, the company’s homegrown operating system that does not rely on Android. Huawei says the platform now supports more than 450,000 apps and services, an important milestone as it attempts to build an ecosystem capable of supporting premium smartphones independently of Google’s software infrastructure.

For Huawei, the software strategy is becoming as important as the processor. A competitive operating system can give the company greater control over the user experience and application ecosystem, while reducing exposure to restrictions affecting U.S. technology.

The challenge is monetizing that technological independence in a smartphone market where consumers remain sensitive to price.

The Mate 90 Pro Max with 16GB of memory and 512GB of storage starts at 9,999 yuan ($1,491), 2,000 yuan above the equivalent Mate 80 model when it launched. The standard Mate 90 starts at 5,999 yuan, while the Pro model starts at 6,999 yuan.

Huawei says its most expensive Mate 90 models deliver a 31% improvement in overall performance compared with the previous flagship generation.

The higher prices come as Chinese smartphone manufacturers face a broader increase in memory and component costs. Yu said higher memory prices have added an average of $200 to the cost of each handset, putting pressure on Huawei’s margins.

“We have to increase prices as well, yet at a slower pace,” Yu said.

The pricing environment is changing the structure of China’s smartphone market. Domestic smartphone shipments declined 7% year on year between January and August, according to IDC, while Huawei shipments increased 13%. At the same time, the average selling price of smartphones in China rose 11.3% in the second quarter to $543. Huawei’s average price declined 14.7% to $628, according to IDC.

That combination gives Huawei room to argue that its premium strategy is supported by demand, but it also leaves the company exposed to rising component costs and a consumer market that is no longer expanding rapidly.

Apple’s entry into foldable smartphones adds another test.

Apple launched its first foldable phone, the iPhone Duo, last month, entering a category in which Huawei has established a substantial position alongside Samsung and other Chinese manufacturers.

Yu welcomed the competition.

“I am very pleased to see the launch of a similar product by our peers,” he said.

Huawei claims about 75% of China’s foldable smartphone market. Yu said sales of the company’s Pura X Max foldable increased 76% week on week between September 10 and 13, immediately after Apple’s launch. The handset, which is similar in size to Apple’s foldable, has shipped more than 1.2 million units in China since its April release.

Therefore, Apple’s entry is expected to create competition for Huawei, but it may also expand the overall market for foldable devices. Counterpoint Research expects Apple to ship about 6 million iPhone Duo units in 2026, with China accounting for almost a quarter of that volume.

The bigger issue for Huawei is whether its technological lead in China’s foldable market can survive Apple’s entry while the company simultaneously deals with semiconductor shortages and higher component costs.

The Mate 90 launch ultimately represents more than another flagship refresh. It is believed that Huawei is attempting to build a self-contained technology stack spanning chip design, semiconductor manufacturing, operating systems, and applications.

That strategy has helped the company remain competitive under restrictions that were intended to limit China’s access to advanced computing technology. But it also exposes the cost of technological self-reliance. Domestic capacity remains scarce, advanced lithography is still a work in progress, and architectural innovations can require more manufacturing resources.
The Quiet Concentration Inside the Treasury Market

0

The U.S. Treasury market is supposed to be one of the world’s deepest and most liquid financial markets. Yet beneath that reputation, ownership and leverage are changing in ways that regulators increasingly regard as a potential source of instability.

By the end of 2025, hedge funds reportedly held roughly 7% of tradable U.S. Treasurys, equivalent to about $2 trillion. That represents a dramatic increase from five years earlier. More important than the headline figure is how much of that exposure is connected to leverage, derivatives and short-term financing.

The concern is not simply that hedge funds own a large amount of government debt. Treasurys are normally viewed as among the safest assets in global finance. The problem is what can happen when those securities become collateral for highly leveraged trading strategies.

Recent U.S. financial-stability assessments show just how quickly hedge-fund Treasury exposure has expanded. The Financial Stability Oversight Council reported that hedge funds’ long Treasury exposure reached approximately $2.38 trillion in the second quarter of 2025.

While short exposure reached about $1.75 trillion. Repo borrowing rose to a record $3.12 trillion. That combination matters because a substantial portion of hedge-fund activity in Treasurys involves relative-value strategies, including the so-called Treasury-futures basis trade.

The strategy can exploit small pricing differences between Treasury securities and related futures contracts. Because those differences are usually tiny, traders often employ significant leverage to make the economics worthwhile.

Leverage works efficiently when markets are calm. But it can become dangerous when prices move sharply. If Treasury prices fall or volatility suddenly rises, leveraged funds can face margin calls. They may then be forced to sell securities or unwind positions quickly.

If several large funds attempt to reduce exposure simultaneously, selling pressure can spread through dealers, repo markets and Treasury futures. A market that normally absorbs enormous transactions can suddenly become less liquid precisely when liquidity is needed most.

The episode of March 2020 remains an important reference point. During the pandemic shock, hedge funds were among the major sellers of Treasury securities, contributing to severe market dysfunction. Treasury officials have subsequently emphasized that excessive leverage can amplify fire sales and transmit stress to banks and other counterparties.

The vulnerability is therefore less about hedge funds holding Treasurys and more about the financing structure surrounding those holdings. Regulators have responded by improving data collection and examining the risks created by repo financing, derivatives and interconnected counterparties.

Treasury officials have also been monitoring the growth of hedge-fund leverage and the expanding role of nonbank financial institutions in core markets.

There is another reason the issue matters now: the U.S. government continues to issue enormous quantities of debt. More Treasury supply requires deeper and more diverse sources of demand. Hedge funds can provide that liquidity and absorb securities efficiently.

But their participation can also make the market more sensitive to changes in financing conditions. That creates a delicate balance. Hedge funds are increasingly important participants in the Treasury market,

Yet the very leverage that allows them to trade at scale can magnify stress during periods of volatility. The Treasury market may remain extraordinarily large, but size alone does not guarantee stability.

The real question for regulators is whether the market can withstand a sudden reversal when leveraged investors all try to exit through the same narrow door.

Daines’ Crypto Tax Bill Signals a New Phase for U.S. Digital-Asset Policy

0

The debate over cryptocurrency in Washington is increasingly moving beyond regulation and market structure toward a question that may be just as consequential for investors and businesses: how digital assets should be taxed.

Senator Steve Daines introduced the Aligning Digital Assets with Principles of Taxation (ADAPT) Act, a 56-page proposal designed to modernize federal tax rules for cryptocurrencies, stablecoins and blockchain-based activities.

The legislation arrives after years in which digital assets have often been forced into tax frameworks created long before blockchain networks existed. Daines has argued that the existing system creates unnecessary complexity for taxpayers and administrative difficulties for the Internal Revenue Service.

In July, he said the objective of his framework was to reduce complexity, increase compliance, protect the tax base and provide greater certainty for the digital-asset industry. One of the most significant provisions concerns stablecoins.

Under the proposal, qualifying purchases of goods and services made with regulated U.S. dollar-backed stablecoins would generally avoid the need to calculate a capital gain or loss on every transaction.

That could matter considerably for everyday payments, because treating every small stablecoin purchase as a taxable disposal can create accounting obligations disproportionate to the value of the transaction.

The bill also addresses blockchain network fees. Transactions involving network or gas fees of $10 or less would receive proposed tax relief, potentially reducing the administrative burden created by recording small taxable events.

For users making frequent on-chain transactions, such provisions could make blockchain payments easier to reconcile with conventional tax reporting. The ADAPT Act does not simply seek to make crypto taxation more favorable. It would extend traditional anti-abuse principles to digital assets, including wash-sale and constructive-sale rules.

That represents an important shift because lawmakers are attempting to establish greater symmetry between cryptocurrencies and comparable financial assets rather than creating an entirely separate tax regime.

The legislation also reaches beyond trading. Its framework addresses areas including digital-asset lending, staking, passive validation, investment trusts and charitable contributions.

Daines has previously argued that where crypto behaves similarly to securities or commodities, familiar tax principles should apply, while genuinely blockchain-specific activities require tailored rules.

The Senate initiative comes as the House advances its own digital-asset tax legislation. On September 16, the House Ways and Means Committee approved the Digital Asset Tax Certainty Act, which addresses reporting requirements, mining and staking, anti-abuse rules and parity with traditional financial assets.

The committee approved that measure by 38–5, creating parallel congressional efforts to modernize crypto taxation. The significance extends beyond lower paperwork.

Clearer tax treatment can influence how companies structure products, how investors account for transactions and whether businesses choose to develop within the United States or elsewhere. Daines has explicitly connected tax certainty with maintaining digital-asset investment and innovation domestically.

Still, introduction is only the beginning. The ADAPT Act must move through the legislative process before any provision becomes law, and its final form could change substantially during congressional negotiations.

The broader message, however, is clear: U.S. policymakers are beginning to treat crypto taxation as infrastructure rather than an afterthought. As stablecoins, tokenized assets and blockchain payments become increasingly integrated into financial markets.

The tax code is being pushed to recognize that the digital economy requires rules designed for how transactions actually work.

Citi Raises Bitcoin and Ether Targets as ETF Inflows, Softer Dollar Revive Crypto Momentum

0

Citigroup has raised its 12-month price targets for bitcoin and ether, pointing to renewed institutional demand, a more supportive macroeconomic environment, and expectations that cryptocurrency exchange-traded fund inflows will resume after a period of weakness.

The bank lifted its bitcoin target to $113,000 from $82,000 and raised its ether forecast to $3,028 from $2,240, representing substantial increases in both projections as the broader crypto market regains momentum after months of trailing other risk assets.

Citi expects cryptocurrency investment flows to return at a slower but more consistent pace as financial advisers, brokerages and other traditional investment channels gradually increase their allocations to bitcoin. The bank forecasts about $5 billion in crypto inflows over the next 12 months, indicating that it expects institutional participation rather than speculative retail activity to provide an important source of demand.

The revised outlook comes as bitcoin and ether have staged a strong three-month rebound. Bitcoin has gained nearly 40% during the period, while ether has risen about 68%, narrowing their year-to-date declines to roughly 4% and 9%, respectively.

The difference in performance is significant because crypto had spent much of the earlier period lagging broader risk assets. Citi’s latest assessment suggests that the market is beginning to benefit from a combination of renewed fund flows and a macroeconomic backdrop that has become more favorable for assets sensitive to liquidity and investor risk appetite.

Citi’s forecast puts particular weight on the role of ETF demand. The emergence of spot bitcoin and ether ETFs has created a regulated channel through which traditional investors can gain exposure to the assets without directly holding cryptocurrencies, making the pace of inflows a necessary indicator of institutional demand.

The bank expects those flows to resume gradually rather than return in a sudden surge. That matters because a slower, steadier accumulation of bitcoin through advisers and brokerages could provide a more durable source of demand than the rapid speculative buying that has historically characterized crypto rallies.

Bitcoin has already risen about 40% from its July lows. The recovery has coincided with a softer US dollar and renewed attention to liquidity conditions after the US Treasury moved to buy back longer-dated government bonds.

A weaker dollar can provide support for dollar-denominated alternative assets by improving financial conditions and increasing the attractiveness of assets outside traditional cash and fixed-income instruments. For crypto, that effect can be amplified when investors are simultaneously looking for assets that can benefit from greater liquidity.

Citi’s forecast therefore rests on more than a simple continuation of recent price momentum. Its thesis assumes that the underlying pool of institutional capital available to crypto will continue expanding, even if the pace of new investment remains more measured than during previous periods of aggressive inflows.

The outlook also highlights the growing importance of financial intermediaries to the cryptocurrency market. As advisers and brokerages become more comfortable allocating client assets to bitcoin, even modest portfolio allocations can translate into sizeable flows because of the scale of assets managed by traditional financial institutions.

Regulatory Uncertainty Remains A Constraint

The more constructive outlook comes against a less straightforward regulatory backdrop in the United States.

The US Senate last week failed to advance the Clarity Act, legislation intended to establish a broader regulatory framework for digital assets. The setback narrowed the immediate path toward comprehensive market-structure legislation and represented another reminder that regulatory certainty remains incomplete for the cryptocurrency industry.

Citi nevertheless stated that developments from the Securities and Exchange Commission helped limit the negative market reaction.

“The Clarity Act’s failure narrowed the path to a market-structure bill, yet spurred Securities and Exchange Commission (SEC) rule announcements that dampened negative sentiment,” Citi said in its note dated Wednesday.

That assessment captures the fragmented nature of crypto regulation. The absence of a comprehensive legislative framework does not necessarily eliminate institutional demand, particularly when investors can operate through regulated investment products. At the same time, uncertainty around market structure, token classification, and regulatory oversight remains an important risk for an industry that is increasingly dependent on mainstream financial institutions.

Therefore, the market is being shaped by two forces moving at different speeds for bitcoin and ether. Capital-market infrastructure around crypto has continued to develop, while the underlying regulatory framework remains unfinished.

Citi’s higher targets imply that the bank expects the expansion of institutional access and improving liquidity conditions to outweigh those constraints over the next year. Its $5 billion inflow forecast also provides a more concrete basis for the bullish outlook, since sustained ETF demand would give the market a source of buying pressure beyond short-term trading activity.

Still, the scale of the recent rebound means expectations have already moved higher. Bitcoin’s 40% advance from its July low and ether’s much larger three-month gain leave both assets more dependent on continued flows and favorable financial conditions to sustain the recovery.

Analysts expect the key test for Citi’s thesis to be whether ETF inflows can transition from intermittent bursts of demand into a steady institutional allocation cycle. If advisers and brokerages continue increasing exposure, the market could have a more persistent source of demand. If those flows fail to materialize, the recent rally would face a much weaker fundamental support base.

However, Citi is currently betting that the combination of renewed ETF demand, a softer dollar, and improving macroeconomic conditions can carry bitcoin to $113,000 and ether to $3,028 over the next 12 months. The forecasts raise the bar for the crypto market, placing greater importance on actual capital flows rather than price momentum alone.

Pentagon Creates Autonomous Warfare Command as US Military Accelerates Shift to AI and Drones

0

The Pentagon is creating a new four-star military command dedicated to autonomous and robotic warfare, as Defense Secretary Pete Hegseth seeks to accelerate the U.S. military’s adoption of drones, artificial intelligence, and other low-cost autonomous systems.

Hegseth announced the Autonomous Warfare Command, or AutoWarCom, on Wednesday during a “State of the Force” address at Marine Corps Base Quantico in Virginia. The command will have “service-like authorities” and is intended to scale autonomous and robotic capabilities across the joint force.

The initiative represents the first creation of a new U.S. combatant command since Space Command was established in 2019. The Pentagon currently has 11 combatant commands covering geographic regions and specific military missions; AutoWarCom would become the 12th.

“The pace of war is changing faster than the process to support it,” Hegseth said.

He pointed to advances in computing, artificial intelligence, and commercial manufacturing as forces changing the economics of warfare.

“Cheap compute, superintelligence, and advanced commercial manufacturing have enabled the proliferation of low-cost, high-precision strike,” Hegseth said.

The command is intended to address that shift by giving autonomous systems their own institutional structure, acquisition authority, and personnel pathways rather than leaving development scattered across existing military organizations.

According to a Pentagon memo released alongside the announcement, the command is targeted for establishment by October 1, 2027. The process will require congressional action, while the Pentagon develops the organization through an interim effort known as Project Agincourt. The command is expected to have dedicated manpower, budget, and acquisition authorities.

The announcement reflects a growing recognition inside the Pentagon that the economics of warfare are changing.

For decades, the U.S. military has relied heavily on sophisticated and extremely expensive platforms, including fighter aircraft, ships, armored vehicles and precision weapons. Those systems provide capabilities that inexpensive drones cannot simply replace, but their cost can make them difficult to deploy at scale against an adversary able to produce large quantities of cheaper systems.

Hegseth framed the emerging model as a combination of high-end weapons and mass-produced autonomous systems.

“Today we need both quality and quantity,” he said.

The Pentagon’s challenge is not just about developing more capable weapons. It is developing systems quickly enough, cheaply enough, and in sufficient numbers to match the pace at which battlefield technology is evolving.

The new command is intended to bring those requirements together across the military. Its portfolio is expected to include drones, artificial intelligence, and command-and-control systems, with the goal of moving autonomous capabilities from experimentation into routine military operations.

That institutional shift could also alter the Pentagon’s procurement process. Traditional defense programs can take years to move from design to deployment, while commercial AI and drone technologies can evolve on much shorter cycles.

Hegseth’s criticism is that the military’s acquisition system is not moving at the same speed as the technology available to potential adversaries.

The Pentagon has already created a task force focused on countering drones, but AutoWarCom is designed to address the other side of the equation: developing and deploying the autonomous systems themselves.

Ukraine Has Become A Test Case For Drone Warfare

The war in Ukraine has provided one of the clearest demonstrations of how inexpensive unmanned systems can change battlefield operations.

Ukraine, facing disadvantages in conventional armor and aircraft, has made extensive use of relatively inexpensive drones for reconnaissance, targeting and attack. Russia has also deployed large numbers of drones, turning the battlefield into an environment in which inexpensive unmanned systems can threaten far more costly military equipment.

Reuters reported that drones are estimated to account for about 70% of Russian casualties, highlighting the extent to which unmanned systems have become integrated into modern combat.

The lesson for the Pentagon is not simply that drones are replacing traditional weapons. Instead, warfare is increasingly becoming a layered system in which expensive aircraft, missiles and ships operate alongside large numbers of cheaper autonomous platforms. A military that can produce and deploy thousands of relatively inexpensive systems may be able to impose costs on an adversary without exposing pilots and other personnel to the same level of risk.

Hegseth’s emphasis on both “quality and quantity” reflects that emerging model.

It also explains why the Pentagon is increasingly looking toward commercial technology companies. Advances in processors, AI models, sensors, communications, and manufacturing are coming from the private sector, where development cycles are generally faster than those of traditional defense programs.

AutoWarCom is meant to provide the military with an institutional mechanism for absorbing those technologies more quickly.

AI Introduces A New Security Problem

The move also carries risks that extend beyond procurement and battlefield efficiency.

AI-enabled military systems can process information and make decisions faster than humans, but increasing autonomy creates questions about reliability, accountability, and human control over the use of force.

Security experts have warned that an accelerating technology competition between the United States and China could increase those risks, particularly if autonomous systems become connected to sensitive military operations or nuclear command structures.

Both U.S. and Chinese experts have called for guardrails and greater consensus around the use of AI in military systems, including nuclear weapons. That tension is becoming more consequential as both countries invest heavily in advanced AI. The United States is trying to preserve its technological lead while China is rapidly expanding its own capabilities in AI, robotics and autonomous systems.

The creation of AutoWarCom signals that the Pentagon views autonomy not as an isolated technology program but as an organizational and operational capability.

The new command will also need to solve a practical problem: turning large numbers of autonomous systems into an effective military force. That requires more than buying drones. It involves software, communications networks, sensors, electronic warfare defenses, logistics, command structures, trained personnel, and systems capable of operating when communications are disrupted.

The Pentagon’s decision to create dedicated career pathways for personnel working with autonomous systems is an acknowledgment of that requirement.

However, experts note that, for the U.S. military, the shift could eventually alter the balance between exquisite but expensive platforms and cheaper systems designed to be produced and replaced at scale.