Home Blog Page 147

Arm CEO Sees AI Transforming Cancer Research, but Chip and Energy Bottlenecks Could Slow the Revolution

0

Arm CEO Rene Haas believes artificial intelligence could help humanity cure cancer within his lifetime. But his prediction comes with a major qualification: the technology’s medical promise will depend on whether the semiconductor industry can supply the chips, memory, data centers and electricity needed to run powerful AI systems.

“I’ve always thought that the killer app for AI is health,” Haas said in an interview with the BBC released Tuesday. “AI is going to not only shorten the amount of time that those drugs can be invented, it’s going to shorten the amount of time that you test them.”

“I believe in our lifetime, AI will help cure cancer,” he added.

Haas’s comments capture the widening gap between AI’s ambitions and the physical infrastructure required to support them. The industry is increasingly presenting AI as a tool for solving some of humanity’s most difficult problems, from drug discovery and climate modeling to robotics and advanced manufacturing. Yet the systems needed to deliver those breakthroughs are placing unprecedented pressure on semiconductor supply chains.

Haas has led Arm, the British chip-design company whose technology is used in products ranging from smartphones to data-center processors, since February 2022. He joined the company in 2013 after spending seven years at Nvidia, where he was vice president of its computing products business.

His background gives him a direct view of the infrastructure demands created by the AI boom. Arm does not manufacture chips itself; instead, it licenses processor designs to companies that build chips for phones, servers, vehicles and other devices. As AI workloads spread across those markets, demand is rising for both high-performance data-center processors and more efficient chips capable of running AI applications at the edge.

“Right now, it’s quite constrained. We need more fabs before we can put a data center in space, I’ll tell you that much,” Haas said. “We’ll probably only put data centers in space when the biggest impediment to data centers is the cost of the data center.”

His reference to space-based data centers was partly humorous, but it underscored a serious point: the industry is still struggling to expand capacity on Earth. Semiconductor manufacturers are operating in what Haas described as an “absolutely supply-constrained environment,” and he expects shortages to persist.

AI’s Hardware Bottleneck Is Broader Than Processors

The shortage is not limited to the graphics processors and custom accelerators used to train and run AI models. One of the most important constraints is high-bandwidth memory, or HBM, which allows AI accelerators to move large volumes of data quickly.

Modern AI systems require enormous amounts of memory because their models contain billions or even trillions of parameters. As models become larger and more capable, the amount of memory needed to train and operate them increases. HBM has therefore become a critical component in the AI supply chain, and its production is concentrated among a small number of manufacturers.

But that concentration creates a vulnerability. Even if chipmakers can produce more AI accelerators, they may not be able to ship complete systems without sufficient supplies of advanced memory and packaging capacity. In many cases, the limiting factor is not the processor itself but the ability to combine the processor, memory, and networking components into a functioning AI system.

Micron Chief Operating Officer Manish Bhatia described the memory shortage as “really unprecedented” in a January interview. He said demand for HBM was consuming manufacturing capacity and contributing to shortages of memory used in more traditional products, including smartphones and personal computers.

Qualcomm CEO Cristiano Amon also warned during the company’s February earnings call that an “industry-wide memory shortage and price increases” could affect the size of the handset market during the year. The comments show that AI demand is beginning to influence markets far beyond data centers.

The pressure is also spreading to advanced packaging, the process used to connect processors and memory in high-performance systems. Packaging has become strategically important because AI accelerators cannot deliver their full performance without fast connections to memory. Expanding packaging capacity can be as difficult and time-consuming as increasing chip production itself.

Building Fabs Takes Years, While AI Demand Is Rising Now

The semiconductor industry is responding with a wave of investment. Chipmakers, memory manufacturers and governments are committing tens of billions of dollars to new fabrication plants, packaging facilities and research programs.

But supply cannot expand quickly. A new semiconductor fabrication plant can cost tens of billions of dollars and typically takes two or three years to build, followed by a lengthy process to install equipment, qualify production lines and reach high yields.

The development has created a mismatch between the speed of AI investment and the pace of industrial expansion. Technology companies can deploy new models and order additional computing capacity within months, while the factories needed to produce the required hardware may take years to complete.

The result could be periodic shortages, higher prices, and greater competition among customers. Large cloud providers and AI companies are likely to receive priority because of their purchasing power and long-term contracts, potentially leaving smaller businesses, universities and startups with less access to advanced computing.

The shortage could also encourage companies to develop smaller, more efficient models that require less computing power. Improvements in algorithms, model compression, specialized chips and software optimization may reduce the amount of hardware needed for some applications. But efficiency gains may not fully offset demand if AI use continues expanding into new industries.

Data Centers Face An Energy And Public-Acceptance Problem

Even when chips are available, AI companies need somewhere to operate them. Data centers require large amounts of electricity, cooling, land, and network infrastructure.

In the United States, more than 1,400 data centers had been built or approved for construction by the end of last year, as technology companies and infrastructure developers raced to accommodate generative AI and other compute-intensive applications.

The expansion is increasingly generating opposition from local communities concerned about electricity consumption, water use, noise, land development and environmental effects. A Gallup survey of 1,000 U.S. adults published in May found that seven in 10 respondents opposed building AI data centers in their local area, with nearly half saying they were strongly opposed.

That resistance could become a significant constraint on AI growth. Data-center developers may have access to capital and hardware but still face years of delays while securing permits, connecting to power grids, and negotiating with local governments.

Electricity availability is becoming a huge issue. Large AI facilities can require as much power as a small city, and clusters of data centers can place pressure on regional grids. Utilities may need to build new generation, transmission lines, and substations before facilities can begin operating at full capacity.

Water use is another concern, especially in regions where data centers rely on evaporative cooling. Developers are exploring alternative cooling systems, including closed-loop and liquid-cooling technologies, but those approaches can increase construction costs and complexity.

AI Could Accelerate Cancer Research, But It Cannot Eliminate Clinical Risk

For healthcare, the potential benefits of more computing power are substantial. AI systems are already being used in drug discovery, protein analysis, medical imaging, patient monitoring and the identification of potential therapeutic targets.

AI can search large biological databases, predict how proteins interact, identify patterns in medical images and help researchers prioritize compounds for laboratory testing. In principle, these tools could reduce the time and cost required to move from a biological hypothesis to a candidate treatment.

But Haas’s prediction should not be interpreted as evidence that a universal cancer cure is imminent. Cancer is not a single disease but a collection of more than 100 diseases, each involving different genetic mutations, biological mechanisms, and responses to treatment.

AI may improve the odds of finding effective therapies, but it cannot remove the fundamental uncertainty of human biology. A compound that performs well in a computer simulation or laboratory experiment may fail in animals or humans. A treatment that works for one genetic subtype of cancer may be ineffective for another.

Clinical trials remain essential. Researchers must establish that a treatment is safe, determine the appropriate dosage, measure its effectiveness, and understand its long-term risks. Regulatory review and manufacturing also take time, even when the underlying discovery process is accelerated.

AI could therefore have its greatest near-term impact not by producing a single cure for cancer, but by helping develop more precise treatments for specific cancer types. It may also improve early detection, identify patients most likely to respond to a therapy, and help doctors select combinations of existing treatments.
China’s Exports Surge 25% in August as AI Boom Offsets Weak Domestic Demand

0

Strong demand for semiconductors, AI-related equipment and electric vehicles is keeping China’s trade engine running, even as consumption, investment and property remain under pressure.

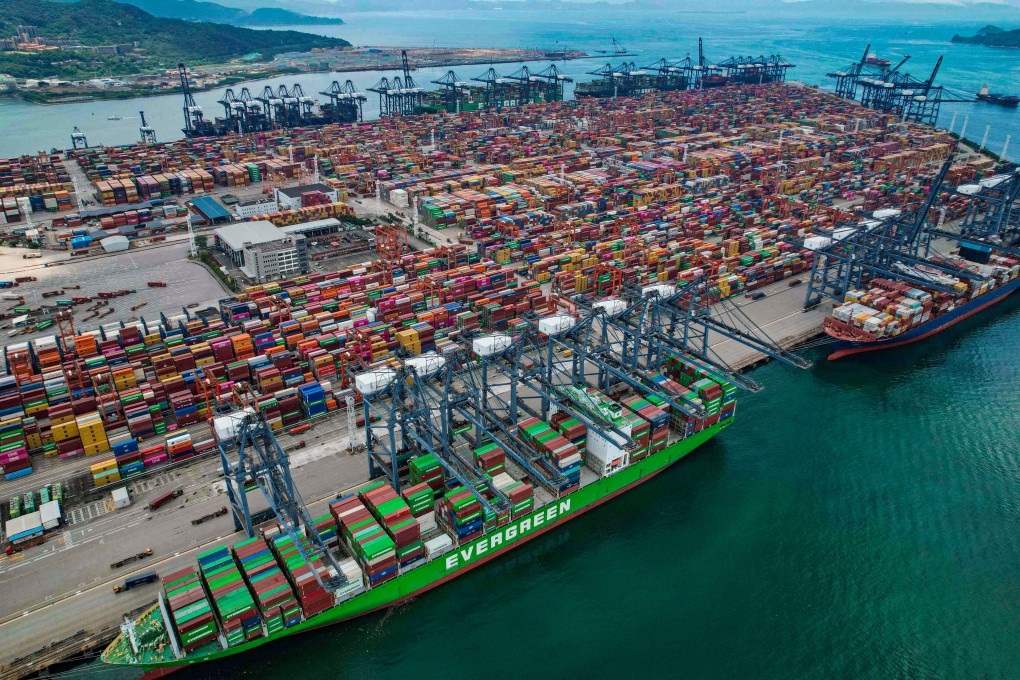
China’s exports accelerated in August, driven by strong overseas demand for high-tech and artificial intelligence-related products, providing a crucial source of growth for an economy still struggling to revive domestic consumption and investment.

Exports from the world’s second-largest economy rose 25% year on year in U.S. dollar terms, matching economists’ forecasts and accelerating from a 23.9% increase in July, customs data showed Tuesday.

Imports also strengthened, climbing 28.2% from a year earlier after rising 27.5% in July, although the increase fell short of the 30% growth economists had expected.

The figures underpin an important divide in China’s economy: external demand remains resilient while activity at home is losing momentum. Beijing is targeting economic growth of between 4.5% and 5% this year, but weaker consumption, investment and the prolonged property downturn are making exports an important support.

“External demand has significantly outpaced domestic consumption,” said Lynn Song, chief economist for Greater China at ING. “Tariff risks and the durability of the tech investment cycle are the key factors to watch to see how long this strength will persist.”

China’s high-tech exports have emerged as a major driver of the expansion. In the first eight months of the year, exports of high-tech products increased 42.9% in U.S. dollar terms.

Semiconductor exports more than doubled in value over the period even though volumes increased only 4.1%, indicating that higher prices and stronger demand for advanced memory and computing components are playing an important role in the export surge.

Automobile exports also rose by more than 50% in both value and volume, reinforcing China’s growing position as a major exporter of electric vehicles and other technology-intensive products.

Strong demand for AI-related equipment, electric vehicles, solar cells and lithium-ion batteries helped offset disruptions caused by weather events, said Zhaopeng Xing, senior China strategist at ANZ.

Xing also noted that companies continued rushing shipments to the United States amid uncertainty over tariffs, potentially bringing some future demand forward.

AI Investment Drives Trade

China’s push to develop strategic technologies is increasingly feeding through into its trade figures. The country is investing heavily in semiconductors, artificial intelligence and advanced manufacturing as Beijing seeks to reduce its reliance on foreign technology and strengthen domestic supply chains.

“The main areas of import growth still look tied to tech products, showing China continues to spend in the ongoing tech race,” Song said.

That investment is benefiting manufacturers across the technology supply chain. Chinese memory-chip producer CXMT, for example, swung to a first-half profit in its first earnings report since listing, helped by higher memory-chip prices and rising demand for AI computing.

The strength of technology exports, however, masks considerable weakness in sectors dependent on Chinese consumers. Companies serving the domestic market continue to face soft demand and producer-price deflation, limiting their ability to pass higher costs on to customers and putting pressure on profitability.

China’s growing reliance on overseas markets also creates a significant policy risk. Using foreign demand to absorb excess industrial capacity can support growth in the short term, but it risks provoking additional trade restrictions from major trading partners already concerned about China’s expanding trade surpluses.

China’s trade surplus reached $119.09 billion in August, up from $112.5 billion in July. For the first eight months of the year, the surplus totaled $805.51 billion, putting the country on course to exceed $1 trillion for the second consecutive year.

The surplus with the United States rose to $29.18 billion from $28 billion in July. Chinese exports to the U.S. jumped 34.4% year on year, substantially outpacing the 17.8% increase in imports.

A trade truce between Beijing and Washington has so far prevented tensions from escalating into a broader confrontation. The two governments are exploring reciprocal tariff reductions covering $30 billion of goods on each side ahead of another summit between the countries’ presidents later this month.

But the sheer scale of China’s trade surplus could make the relationship increasingly difficult to manage, particularly if exports continue to outpace imports.

China’s rare-earth exports increased month on month in August but remained well below the average monthly level for the year. Crude-oil imports fell 23.4% year on year in volume terms, suggesting that the broader import picture is being shaped heavily by technology investment rather than a broad-based acceleration in domestic demand.

The trade figures had little immediate impact on financial markets, with the yuan broadly flat and Chinese stocks slightly higher as investors awaited U.S. inflation data for clues about the Federal Reserve’s interest-rate path.

Domestic Economy Remains The Weak Link

The export strength comes as several major indicators point to slower momentum at home.

China’s economy grew 4.3% in the second quarter, while data released last month showed industrial production and retail sales slowing at the start of the third quarter. Fixed-asset investment also declined more sharply in the first seven months.

The property sector, previously one of the country’s most important sources of economic growth, remains trapped in a prolonged downturn, weighing on household wealth, construction activity and consumer confidence.

Premier Li Qiang called in August for measures to stabilize external demand while acknowledging insufficient domestic demand, difficulties facing industries and rising uncertainty in the international environment.

Beijing has increased fiscal support, including an 800 billion yuan ($119.21 billion) financing facility intended to strengthen infrastructure investment.

But strong exports reduce the immediate pressure on policymakers to introduce more aggressive measures aimed at households, employment and the property market. As long as factories can continue selling abroad, China can partially offset weak domestic demand without relying solely on large-scale stimulus.

That dynamic could also influence monetary policy.

“The latest trade data do not materially strengthen the case for an imminent interest rate cut,” said Hao Zhou, a Hong Kong-based analyst at Guotai Haitong Securities.

“While further policy support cannot be ruled out, the combination of resilient external demand, steady industrial momentum, and increasingly targeted fiscal measures implies that the timing and necessity of additional monetary easing will require further observation,” he said.

However, it is currently not clear if the export boom can remain strong enough to compensate for weakness at home without generating a new wave of trade tensions. AI investment, semiconductors, electric vehicles and other high-tech products are giving China’s exporters a powerful source of momentum.

But the longer domestic consumption remains subdued, the more dependent the economy becomes on foreign buyers, leaving its growth outlook exposed to tariffs, protectionism and the durability of the global technology investment cycle.

Canada Imposes Up to 50% Tariffs on U.S. Goods as Trade War With Trump Escalates

0

Canada imposed a new round of retaliatory tariffs on U.S. goods on Tuesday, escalating the trade confrontation between the two North American allies after negotiations collapsed and President Donald Trump intensified pressure on Ottawa.

The new duties range from 15% to 50% and cover hundreds of U.S. products with a combined value of about $27.6 billion. Targeted goods include dairy products, agricultural equipment, paper, household appliances and electronics.

Canada also doubled its tariffs on U.S. steel, aluminum and iron products to 50%. Furniture, motorcycles, clothing and selected beauty products are among the goods facing the highest tariff rate.

Ottawa described the measures as a “dollar for dollar” response to U.S. tariffs imposed on Canadian products, saying the policy was designed to protect Canadian workers, producers and manufacturers from the competitive impact of American imports.

The new measures add to existing Canadian tariffs, including a 25% duty on U.S. automobiles, leaving significant parts of the bilateral manufacturing supply chain exposed to higher costs.

The latest escalation follows the breakdown of trade negotiations at the end of August. Officials in Washington and Ottawa have blamed each other for the failure to reach an agreement, with both sides publicly identifying areas where negotiations failed to produce a compromise.

The deterioration in relations has also spread into the aerospace sector.

Trump on Monday called for a boycott of Canadian aircraft manufacturer Bombardier, writing on Truth Social: “NO MORE SELLING BOMBARDIER IN THE UNITED STATES!”

The statement added uncertainty for an industry whose supply chains extend across the U.S.-Canada border and involve American workers, suppliers and aerospace companies.

The economic relationship at stake is considerably larger than the products covered by Tuesday’s new tariffs.

The United States exported $333.6 billion of goods to Canada and imported $381.9 billion from its northern neighbor. The two countries maintain deeply integrated supply chains spanning energy, automobiles, heavy machinery, aircraft, pharmaceuticals, furniture, clothing and food products.

That integration makes the economic consequences of tariffs different from those of a conventional trade dispute between less-connected economies. Components can cross the border multiple times before a finished product reaches consumers, meaning tariffs imposed on one side can increase costs for manufacturers on both sides.

Economists say the newly targeted products represent a relatively small portion of total bilateral trade, limiting the immediate macroeconomic impact. The effect could nevertheless be severe for companies concentrated in the affected industries, particularly small and medium-sized businesses with less capacity to absorb higher input costs or shift suppliers.

Canadian businesses may face higher prices for American machinery, equipment and components, while U.S. exporters could lose market share as Canadian importers look for alternatives.

Agriculture is another potential pressure point. Tariffs on dairy and other food products can alter sourcing patterns and raise costs for consumers, while retaliatory measures can reduce access to an important export market for American producers.

The steel and aluminum measures carry additional significance because metals are fundamental inputs for construction, machinery, transportation and manufacturing. A 50% tariff can therefore affect companies beyond the industries directly covered by the measure if higher material costs work their way through supply chains.

Ottawa has attempted to cushion the impact on its domestic economy.

The Canadian government announced a C$7.5 billion support package for affected businesses and workers last month, adding to roughly C$25 billion in measures introduced in response to the broader U.S. tariff campaign that began in April 2025.

The government is effectively trying to offset some of the disruption created by its own retaliatory strategy while maintaining pressure on Washington to negotiate. That approach creates a difficult balance for Prime Minister Mark Carney’s government. Retaliatory tariffs can increase the political cost for U.S. exporters and strengthen Ottawa’s bargaining position, but they can also raise costs for Canadian companies and consumers.

The dispute comes with a similar risk for Washington. Canada is the largest trading partner for many U.S. businesses and an important destination for American agricultural, industrial and consumer exports. Prolonged restrictions could therefore create pressure from U.S. companies that depend on Canadian demand.

The dispute is also unfolding against a wider U.S. push to use tariffs to encourage domestic production and extract concessions from trading partners. That strategy has increasingly shifted the focus of trade policy from reducing barriers to reshaping where companies manufacture and source products.

Against this backdrop, the stakes are high for Canada and the United States, because their economies have been integrated for decades. Energy networks, factories, transportation systems and supplier relationships have been built around relatively frictionless cross-border commerce.

However, analysts believe the immediate impact of Tuesday’s tariffs may be concentrated in specific industries rather than the broader economy. The larger concern is what happens if the measures remain in place long enough for companies to redesign supply chains, relocate production or permanently shift toward alternative suppliers.

With negotiations currently stalled and rhetoric intensifying, the latest tariffs risk becoming more than a temporary negotiating tool. They could accelerate a structural change in one of the world’s most integrated trading relationships.

Crypto Platforms Lose $3.6 Billion to Hacks Despite Widespread Security Audits

0

Cryptocurrency platforms lost more than $3.63 billion to cyberattacks and stolen credentials between January 2025 and July 2026, with security audits failing to prevent many of the largest losses, according to a CoinGecko report.

The crypto market data provider said about 88% of the stolen funds came from platforms that had completed independent security audits. Roughly 60% of the affected platforms had also undergone such audits.

The findings raise questions about the effectiveness of relying on conventional security audits as a primary defense against attacks in an industry where control over private keys, administrative credentials and transaction-signing systems can determine whether billions of dollars remain secure.

CoinGecko said many of the attacks exploited areas that standard security checks do not typically cover.

An audit generally assesses a defined set of systems, controls or code at a particular point in time. It does not necessarily demonstrate that an exchange or decentralized protocol can withstand sophisticated social engineering, compromised credentials, insider threats, supply-chain attacks, or the theft of cryptographic keys used to authorize transactions.

The scale of the losses illustrates the consequences.

Bybit suffered the largest reported loss, with about $1.4 billion stolen in a February 2025 attack. Blockchain intelligence firm Elliptic attributed the theft to North Korea.

KelpDAO was the second-most affected platform, with losses of about $292 million, followed by Drift Protocol at $285 million, according to CoinGecko.

The concentration of losses among a relatively small number of major incidents also reveals the asymmetric nature of cryptocurrency security. A platform can maintain extensive security controls for years and still face a single successful compromise capable of producing losses far larger than the cost of routine security testing.

The problem is particularly acute in systems where large amounts of assets can be moved rapidly once an attacker gains access to the mechanisms that authorize transactions.

The CoinGecko findings therefore point to a broader shift in how crypto security may need to be evaluated. Code reviews and independent audits remain necessary, particularly for decentralized protocols, but they address only part of the threats.

Operational security equally matters. Protecting signing keys, restricting administrative privileges, separating transaction approval from transaction execution, monitoring unusual transfers, and maintaining robust incident-response procedures can determine whether a compromised account becomes a limited security event or a nine-figure loss.

The findings also expose a potential weakness in how security is communicated to investors and users. The presence of an independent audit can create an impression of comprehensive protection even when the audit covers only specific components or vulnerabilities.

For crypto platforms holding or controlling large pools of customer assets, that gap has financial and reputational consequences. A successful exploit can drain funds directly, trigger withdrawals, disrupt trading and undermine confidence in the platform’s broader security architecture.

The industry is also facing increasingly sophisticated attackers. State-linked groups, organized cybercriminals and highly specialized hackers have strong financial incentives to target cryptocurrency because transactions can move large sums across borders without the same intermediaries used in traditional finance.

The $3.63 billion in reported losses through July 2026 is seen as an indication that security spending is not necessarily translating into proportionate protection. The fact that audited platforms accounted for the majority of stolen funds does not mean audits caused the breaches, but it does show that passing an audit should not be treated as evidence that a platform is immune to major attacks.

The situation has sustained a question for crypto investors and institutions: do platforms have layered defenses that remain effective after an attacker bypasses its formal controls?

As the value locked in exchanges, decentralized finance protocols, and other digital-asset infrastructure continues to grow, security is becoming less a matter of passing a technical inspection and more a question of whether platforms can continuously protect the mechanisms that ultimately control billions of dollars.

Gold Slips as Oil-Driven Inflation Risks Lift Fed Rate-Hike Bets Ahead of U.S. Data

0

Gold prices edged lower on Tuesday as a jump in oil prices revived concerns about inflation, while stronger-than-expected U.S. labor-market data continued to push investors toward a more cautious view of Federal Reserve policy.

A weaker dollar and heightened geopolitical tensions helped limit bullion’s decline ahead of key U.S. inflation reports later this week.

Spot gold was down 0.1% at $4,399.99 an ounce by 1024 GMT, after rising as high as $4,442.70 earlier in the session. U.S. gold futures for December delivery fell 0.7% to $4,444.50.

“Gold trades cautiously today, caught between Fed rate hike bets and dollar softness. Higher oil prices stoke inflation risks and expectations for Fed rate hikes, putting the precious metal under pressure,” said Nikos Tzabouras, a senior market analyst at Jefferies-owned Tradu.com.

The market is being pulled in opposite directions. A weaker dollar supports gold by making the metal less expensive for buyers using other currencies, while geopolitical uncertainty encourages demand for traditional safe-haven assets. But those supports are being offset by rising oil prices and shifting expectations for U.S. interest rates.

Oil prices climbed to multi-week highs after Yemen’s Tehran-backed Houthis attacked energy facilities and cities in U.S. ally Saudi Arabia, adding a fresh geopolitical premium to crude. Higher energy prices can feed directly into headline inflation and raise costs for transportation, manufacturing and other businesses, increasing the risk that price pressures remain elevated for longer.

That prospect could make the Federal Reserve more reluctant to cut rates or could even revive expectations for tighter policy. Gold does not pay interest, so its appeal typically weakens when bond yields and policy rates rise, increasing the opportunity cost of holding bullion.

The pressure on gold has intensified since Friday, when the metal fell as much as 2.4% in its sharpest one-day decline in recent weeks. The sell-off followed U.S. employment data showing that job growth accelerated sharply in August, while the unemployment rate held at 4.1%. The figures suggested that the economy may be strong enough to withstand higher borrowing costs and reduced expectations for near-term monetary easing.

Markets are now pricing in about a 60% chance of a Federal Reserve interest-rate hike at its next policy meeting, according to the CME FedWatch Tool, up from roughly 50% before the employment report. The repricing has also increased the sensitivity of gold to Treasury yields and incoming economic data.

Investors will receive the U.S. producer price index on Thursday and the consumer price index on Friday. The reports will be scrutinized for signs that higher energy costs are spreading into broader inflation measures. Core inflation readings, which exclude volatile food and energy prices, may be required because they could show whether price pressures are becoming entrenched rather than remaining limited to fuel markets.

A hotter-than-expected report could push Treasury yields higher, strengthen the dollar and further reduce expectations for monetary easing, creating additional headwinds for gold. Softer inflation data could have the opposite effect by reviving expectations for a more accommodative Fed and supporting bullion.

“The precious metal may struggle for firm direction from any inconclusive prints, given fluid market pricing and a Fed that lacks conviction,” Tzabouras said.

The dollar index weakened on Tuesday, providing some support to gold and helping cushion the impact of higher rate expectations. Geopolitical tensions may also continue to underpin demand for bullion, especially if the conflict involving energy infrastructure raises concerns about supply disruptions or broader regional escalation.

Still, the market’s focus has shifted from gold’s safe-haven appeal to the interaction between oil, inflation and monetary policy. Analysts note that if crude prices continue rising while U.S. economic data remains resilient, investors may demand higher yields to compensate for inflation risk, weighing on gold. Conversely, evidence that inflation is cooling despite higher energy costs could allow bullion to regain momentum.

The broader precious-metals complex was mixed. Spot silver slipped 0.1% to $66.08 an ounce, while platinum rose 0.6% to $1,836.72. Palladium fell 0.4% to $1,387.43.

Currently, gold remains caught between a weaker dollar and geopolitical demand on one side, and higher oil prices, firmer rate expectations and resilient U.S. growth on the other. This week’s inflation data is expected to determine which force dominates and whether bullion resumes its advance or faces renewed pressure from rising yields and a less accommodative Federal Reserve.