DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 38

David Rubenstein on Wealth, Investing and the Value of Scarce Assets

0

For David Rubenstein, buying a baseball team was never simply a financial transaction. In 2024, the billionaire co-founder of Carlyle Group led a group that acquired the Baltimore Orioles for about $1.725 billion.

A price that reflected both the growing economic value of professional sports and a deeply personal connection to his hometown. Rubenstein grew up in Baltimore as a fan of the Orioles, at a time when owning a Major League Baseball franchise seemed completely outside his family’s economic reality.

His father worked for the post office, and Rubenstein has recalled that becoming a team owner was never something he imagined as a young man. Decades later, his success in private equity gave him the opportunity to acquire the club.

Yet Rubenstein’s explanation for the purchase goes beyond nostalgia. He has said that he had not done enough philanthropy in Baltimore and wanted to do something meaningful for the city. Sports ownership, in his view, provides an unusual combination of business, community identity and cultural influence.

The Orioles therefore represent both an investment and a civic commitment. The economics of sports also help explain the attraction. Team valuations have increased dramatically as television rights, media distribution.

Sponsorships and the scarcity of major professional franchises have transformed sports into a valuable asset class. Rubenstein has acknowledged that prices have risen sharply, while also warning that no asset rises forever.

His investment history contains a powerful reminder that even sophisticated investors miss enormous opportunities. Rubenstein identifies his two biggest investing mistakes as walking away from Amazon and Facebook in their early stages.

In Amazon’s case, Rubenstein and his Carlyle partners received an opportunity to own a stake in the company during its early years. They eventually sold after Amazon’s stock collapsed during the dot-com bust. The decision protected them from further losses at the time, but hindsight revealed the enormous opportunity cost.

The position could have been worth billions of dollars today. The Facebook opportunity was even more striking. Rubenstein was approached about investing roughly $30,000 when Mark Zuckerberg was seeking early capital for the company.

He did not take the proposal seriously. Eduardo Saverin provided the initial funding, and Facebook became one of the world’s most valuable technology businesses. These mistakes highlight an uncomfortable reality of investing.

The greatest losses are not always positions that collapse. Sometimes they are opportunities an investor never owns. Rubenstein’s experience also informs his view of today’s artificial-intelligence boom.

He has warned that AI valuations can be extremely difficult to justify in some cases, while acknowledging that the underlying technology is generating genuine economic value.

His lesson from the dot-com era is not simply to avoid bubbles, but to recognize that a speculative cycle can contain companies that ultimately become enormous businesses. That distinction matters.

Investors can be correct that a market is overheated and still miss its most important winners. Rubenstein’s Orioles purchase therefore fits into a broader philosophy: investing is not only about spreadsheets, valuations and projected returns.

It is also about understanding scarce assets, enduring institutions, human behavior and the opportunities that appear before their value becomes obvious. His career demonstrates that even billionaires can make decisions they later regret.

The difference is that the lessons from those decisions can become more valuable than the investments themselves.

Quantum Computing and AI Could Create New Risks for Blockchain Markets

0

Imagine a quantum computer feeding complex market variables into an artificial intelligence system.

The machine processes correlations across prices, liquidity, volatility, order books, macroeconomic indicators and blockchain activity at a speed far beyond conventional computing.

Then, somewhere inside that extraordinary calculation, a statistical glitch is mistaken for a financial crash. The AI reacts instantly. Thousands of accounts could be frozen.

Automated trading systems could begin selling. Smart contracts could activate emergency mechanisms. Liquidity could disappear from a decentralized market within seconds.

And because the underlying blockchain ledger is designed to preserve confirmed transactions, an erroneous action could become extremely difficult to reverse once it has been executed.

As Dr. Barry Childe warns, the danger is not necessarily that quantum computers or artificial intelligence will independently decide to destroy financial markets. The deeper concern is what happens when increasingly powerful technologies are given authority to make consequential decisions without sufficient human oversight.

Financial markets already depend heavily on algorithms. High-frequency trading systems can respond to information in fractions of a second, while decentralized finance protocols can automatically liquidate positions, adjust collateral requirements or execute transactions according to predefined rules.

AI introduces another layer of complexity because it can identify patterns that humans might never notice. Quantum computing could eventually expand that analytical capacity even further for certain classes of problems.

But speed is not the same as accuracy. A sophisticated system can still misunderstand its inputs. An unusual market movement might represent a temporary liquidity imbalance rather than a systemic collapse. A data-feed error could resemble a genuine price shock.

Correlated assets might suddenly move together because of technical factors rather than fundamental economic deterioration. If an AI model interprets such anomalies incorrectly and its conclusion is connected directly to automated financial infrastructure.

The consequences could spread before anyone has time to investigate. This creates a fundamental problem: the faster the system acts, the smaller the window becomes for human intervention. Blockchain technology makes the question even more complicated.

Immutability is one of its defining characteristics because it creates confidence that confirmed records cannot simply be rewritten. Yet the same feature can become a liability when an automated decision is wrong.

A transaction can be irreversible even when the information that triggered it was flawed. That does not mean immutable blockchains are inherently unsafe. Rather, it means financial infrastructure must distinguish between immutable records and irreversible decision-making.

A blockchain can preserve an accurate record of a bad decision just as effectively as it preserves a good one. The solution will therefore require layers of safeguards. Critical AI systems should operate with independent validation, anomaly detection, transaction limits and circuit breakers.

Human authorization may remain necessary for unusually large transfers or systemic interventions. Multiple data sources should be compared before an automated system treats an apparent market shock as genuine.

And smart contracts should be designed with carefully governed emergency mechanisms where appropriate. The central lesson is straightforward: financial automation needs brakes as much as it needs engines.

Quantum computing may eventually transform how markets model risk, while AI could make financial infrastructure dramatically more adaptive. But combining enormous computational power with autonomous execution also creates a new category of systemic risk.

The greatest danger may not be a machine that intentionally causes a crash. It may be a machine that confidently makes the wrong decision—and makes it faster than humans can stop it.

Wall Street Ends The Week Higher as AI Stocks Rebound, but 5% Treasury Yields Keep Markets on Edge

0

Wall Street ended higher on Friday as renewed demand for AI-related technology stocks helped the S&P 500 and Nasdaq recover from a volatile week, although the rally remained constrained by rising oil prices, elevated Treasury yields and growing expectations that the Federal Reserve could resume raising interest rates.

Microsoft was among the biggest drivers of the technology-led advance, gaining 3.7% after unveiling new capabilities for its Copilot artificial intelligence platform, including a coding tool and an always-on AI agent. The gain lifted Microsoft’s 2026 advance to 7%.

Qualcomm rose 4%, and Dell gained 5%, adding to a broader recovery in technology stocks tied to the continued expansion of AI infrastructure.

Akamai Technologies also advanced 3.2% after announcing an $11.6 billion, seven-year cloud infrastructure agreement with Anthropic. The deal includes a warrant that could give Anthropic a stake of as much as 5% in Akamai, creating another example of the interconnected financial relationships between AI developers and the companies supplying their computing infrastructure.

“That’s a positive from the standpoint that people are still investing, deals are still being done,” said Thomas Martin, senior portfolio manager at Globalt Investments in Atlanta. “It’s another circular deal, so OK … but Akamai stock is up.”

The gains pushed the S&P 500 up 0.51% to 7,743.41. The Nasdaq rose 0.48% to 27,068.72, while the Dow Jones Industrial Average gained 0.93% to 51,828.62.

For the week, the S&P 500 advanced 1.2%, and the Nasdaq gained 2%, following a record close for the technology-heavy index on Tuesday.

Yet the market’s weekly performance masks a more complicated backdrop. Investors are increasingly having to assess two opposing forces: the earnings and investment momentum generated by AI, and the tightening financial conditions created by higher oil prices and government bond yields.

AI Spending Continues to Support Markets

Seven of the S&P 500’s 11 sector indexes finished higher on Friday, led by information technology, which gained 0.91%. Industrials followed with a 0.6% increase.

The latest economic data also bolstered the importance of AI investment to the US economy.

Business spending on AI-related infrastructure helped drive demand for key manufactured capital goods in August, with orders exceeding expectations. That provides another indication that the AI boom is translating into real investment across the broader economy rather than remaining confined to technology companies.

The market’s enthusiasm, however, is increasingly dependent on whether that spending eventually produces sufficient earnings.

The S&P 500 traded at just under 19 times expected earnings during the week, its lowest valuation since 2023, according to LSEG data. AI-heavy companies have accounted for much of the recent improvement in earnings expectations, creating a potentially important distinction for investors. The market is not simply pricing AI as a technological theme. It is increasingly relying on the technology’s ability to generate earnings growth large enough to justify the capital being deployed across chips, cloud computing, data centers, and software.

Microsoft’s latest Copilot expansion and Anthropic’s massive Akamai commitment provide fresh evidence of continuing AI demand. But they also highlight the scale of investment required to sustain the sector.

Treasury Yields Remain The Bigger Macro Threat

The strongest constraint on the equity rally came from the bond market. The benchmark 10-year Treasury yield reached a fresh 19-year high and was last up 3.4 basis points at 5.196%. A yield above 5% represents a significant change in the financial environment for equities because it raises the return investors can obtain from relatively low-risk government debt.

It also increases borrowing costs throughout the economy.

The rise in Treasury yields has been driven by a combination of persistent inflation concerns, strong economic data, and expectations that the Federal Reserve may need to raise interest rates again.

Markets were pricing a 66% probability of at least a 25-basis-point Fed rate increase in October, according to CME Group’s FedWatch Tool, up from roughly 50% earlier in the week. That repricing is occurring even as investors continue to absorb the effects of already elevated borrowing costs.

For technology companies, the issue has become relevant because higher interest rates increase the discount rate applied to future earnings. Companies whose valuations depend heavily on expectations of strong earnings growth several years into the future can therefore face greater pressure when bond yields rise.

The fact that technology stocks still advanced in the face of a 5.2% 10-year yield suggests that investors remain willing to pay for companies they believe can produce sufficient AI-driven growth. But it also means the earnings burden on the sector is becoming higher.

Oil Adds Another Inflation Risk

Oil remains another source of uncertainty. Brent crude eased on Friday but stayed above $100 a barrel as investors monitored diplomatic efforts to end the US-Iran war and reopen the Strait of Hormuz.

Reports that US and Iranian negotiators were exploring a phased path out of the conflict provided some relief to markets. Such an arrangement would involve Tehran reopening the strategic waterway and Washington lifting its economic blockade of Iran.

The prospect of easing tensions helped offset some of the pressure created by elevated energy prices.

The market remains highly sensitive to developments in the Middle East because a prolonged disruption around the Strait of Hormuz could feed directly into global energy prices and inflation expectations.

Higher oil prices create a difficult policy environment for the Federal Reserve. Energy costs can raise headline inflation while simultaneously reducing consumers’ purchasing power and increasing companies’ operating expenses. That combination could make it harder for the central bank to support economic activity through lower interest rates.

Investors Remain Selective Within AI

The week’s trading also showed that enthusiasm for AI is no longer uniform across the technology sector.

Microsoft rallied strongly, while Qualcomm, Dell and Akamai also benefited from expectations surrounding AI-related demand.

Meta Platforms, however, fell 3.3% on Friday even though its shares had climbed about 13% during the week following the strong reception to its Muse AI agent.

Muse has generated expectations that AI agents could benefit companies providing computing infrastructure, but the technology could also disrupt businesses that depend on conventional digital intermediaries, including banks, online shopping platforms and other consumer-facing services.

Despite the headline gains, market breadth remained mixed.

Advancing stocks outnumbered declining stocks within the S&P 500 by 1.9 to 1, but the Nasdaq recorded 175 new lows against 54 new highs. The S&P 500 posted three new highs and 31 new lows.

Trading volume was also relatively light, with 14.9 billion shares changing hands compared with a 20-session average of 16.8 billion.

That suggests Friday’s advance was not necessarily evidence of a broad-based removal of risk from the market. Investors continued to concentrate on companies with strong AI exposure and the earnings growth associated with it, while other areas remained vulnerable to higher rates and energy costs.

The summit between Trump and Chinese President Xi Jinping also provided some support to sentiment. Trump described his meeting with Xi as “very productive” following their three-day summit, although the gathering produced limited publicly announced breakthroughs on the most contentious economic issues.

For Wall Street, the immediate focus remains the interaction between AI-driven earnings growth and increasingly restrictive financial conditions.

AI investment is still providing a powerful source of economic and corporate momentum. Microsoft, Qualcomm, Dell and Akamai all offered fresh evidence of that spending cycle this week.

But with the 10-year Treasury yield approaching 5.2%, oil above $100 and markets assigning a rising probability to another Fed rate increase, investors are confronting a higher hurdle for virtually every asset.

The result is a market where AI optimism remains powerful, but increasingly has to compete with the mathematics of higher interest rates and more expensive energy.

Neko Health Comes to New York With a $499 Preventive Health Scan

0

For years, preventive healthcare has operated on a simple rhythm: wait for a problem, visit a doctor, run a few tests and hope nothing serious appears. Neko Health is proposing a different model.

Scan first, understand the data quickly and potentially identify warning signs before they become obvious. Its arrival in New York puts that idea directly in front of American consumers for $499.

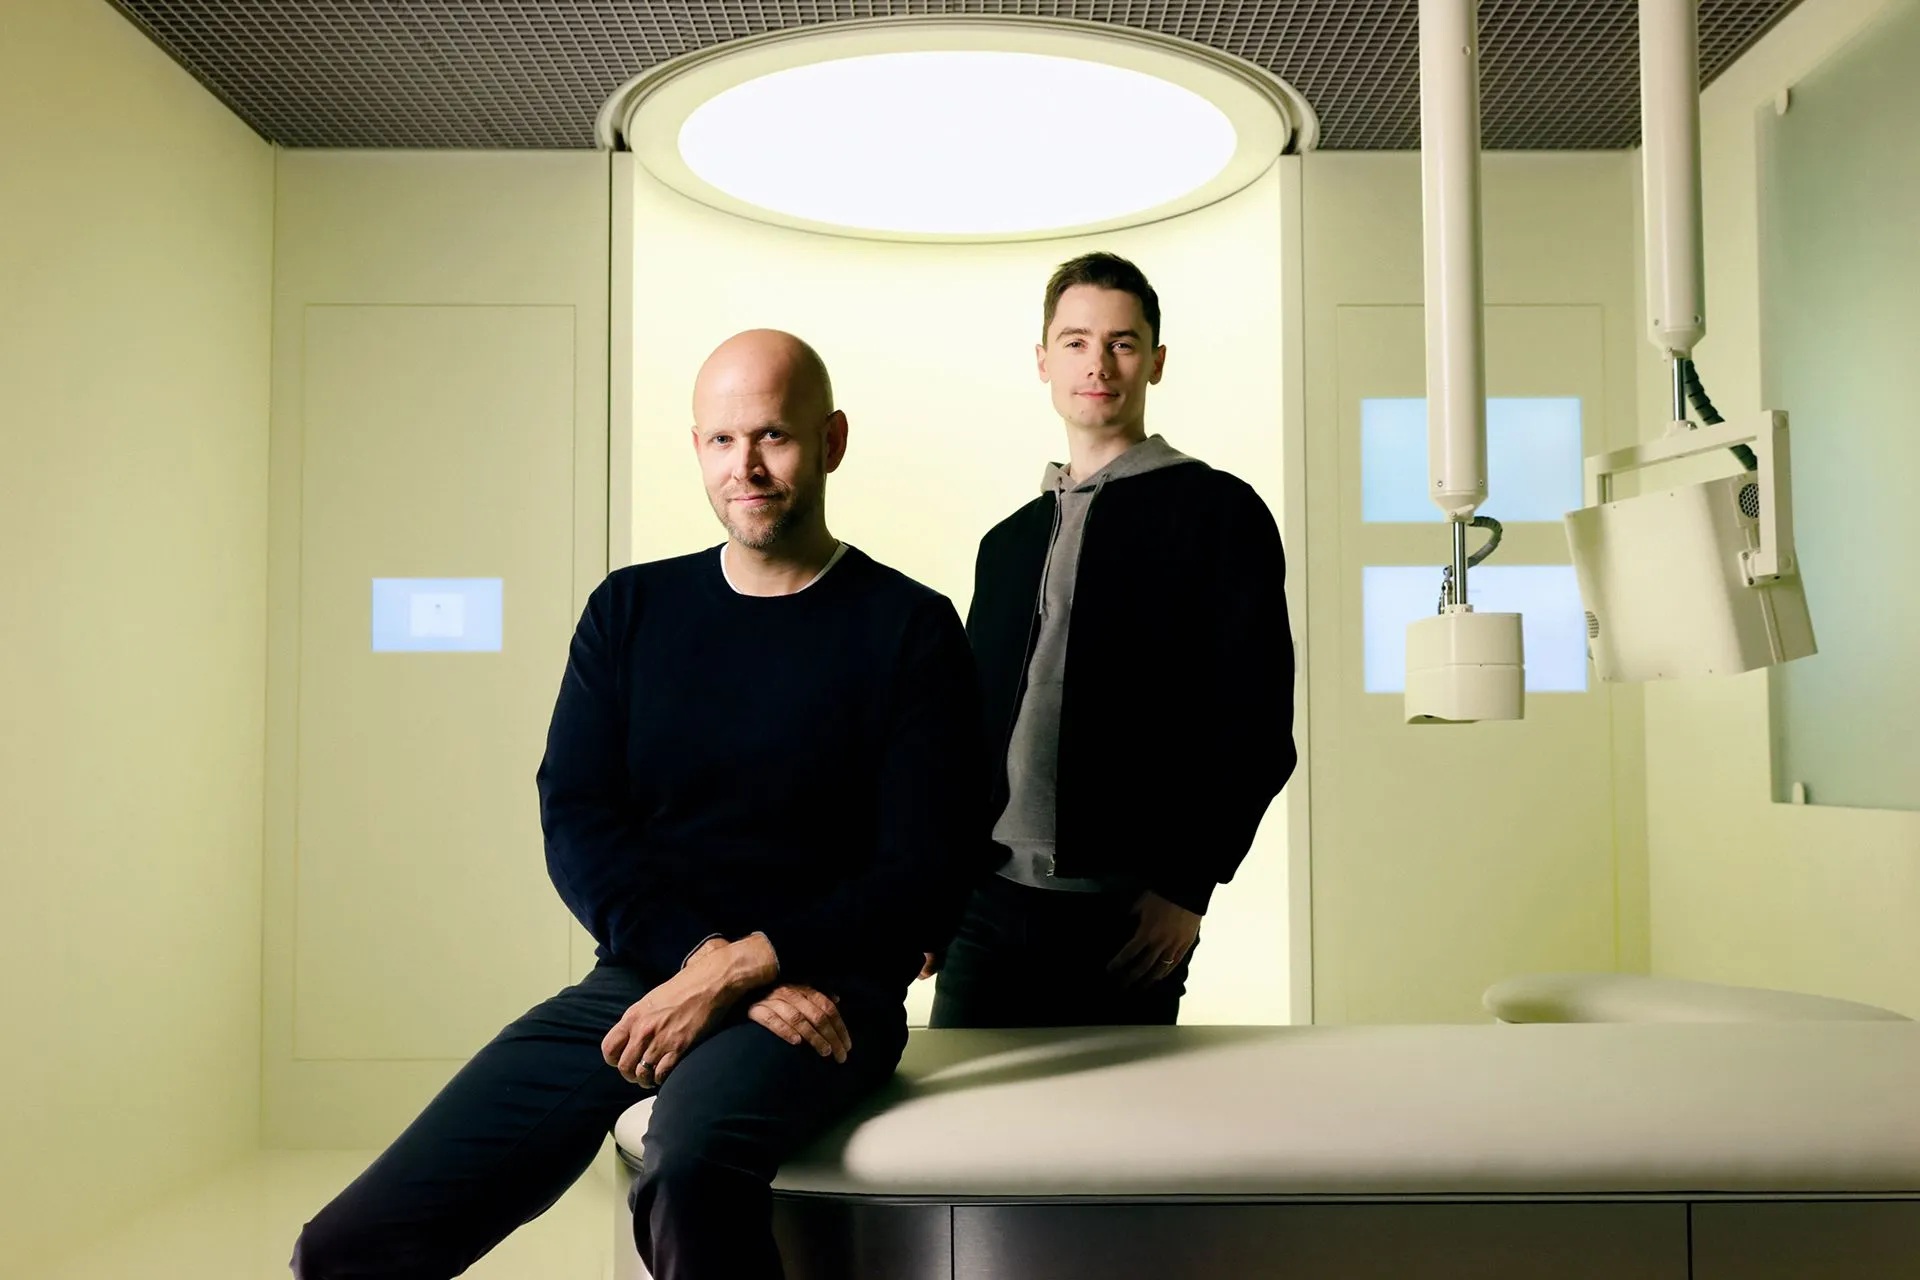
The Swedish health-tech company, co-founded by Spotify creator Daniel Ek, opened its first U.S. clinic in Manhattan’s SoHo neighborhood this week. The company had already accumulated a waitlist of roughly 25,000 New Yorkers, illustrating the appetite for consumer-focused preventive medicine.

Neko previously operated in Sweden and the United Kingdom, where more than 100,000 Europeans have reportedly used its services. The centerpiece is a full-body scan that uses cameras and other sensors to examine the skin and collect information about body composition.

Rather than simply taking a photograph, the system is designed to document thousands of images and track marks on the body that could warrant further investigation. That feature may be particularly relevant for people concerned about melanoma and other skin cancers.

But Neko’s examination goes beyond skin. Patients undergo blood-pressure measurements on all four limbs, blood tests covering markers such as cholesterol and blood sugar, an electrocardiogram, grip-strength testing and an eye-pressure examination.

The visit is designed to take roughly an hour, with results discussed with a clinician during the same appointment. That speed is arguably one of Neko’s biggest selling points. Traditional healthcare can involve separate appointments, laboratory visits, waiting periods and follow-ups.

Neko packages several measurements into one consumer-oriented experience and attempts to make the resulting data understandable rather than leaving patients to interpret a collection of numbers. There is also evidence that the technology can generate useful follow-up.

In a recent test of the New York service, a reviewer was contacted after the appointment because a mole on the torso was considered worthy of additional dermatological investigation. Neko says fewer than one in 10 customers are referred externally for follow-up.

Yet the $499 price raises an important question: how much of this is genuinely new medicine, and how much is better packaging? Several components of the examination are already available through conventional primary care.

Preventive examinations and many basic measurements can be covered by insurance for eligible patients, while dedicated skin-cancer screening may cost considerably less than $499. Neko therefore is not necessarily selling access to tests that cannot be obtained elsewhere.

It is selling convenience, speed, integration and a highly designed healthcare experience. That distinction matters because more data does not automatically mean better healthcare. A scan can identify something worth investigating.

But follow-up with specialists remains essential. Neko itself says its service is not intended to replace traditional hospital care. Its screening should therefore be viewed as an additional layer of preventive monitoring, rather than a universal substitute for established diagnostic medicine.

For $499, Neko is essentially betting that consumers will pay for a frictionless health checkup. For some people, especially those who value rapid information and structured monitoring, that convenience may have significant value.

For others, the same money could be directed toward conventional preventive care, exercise, specialist consultations or other established health services. The larger significance of Neko may therefore extend beyond the scanner itself.

Healthcare is increasingly becoming a consumer technology market, where speed, data visualization and user experience compete alongside clinical capability. Whether $499 represents good value depends less on how futuristic the machine looks and more on whether the information it produces leads to meaningful medical action.

Starbucks’ 250-Store Closure Signals a More Selective Turnaround

0

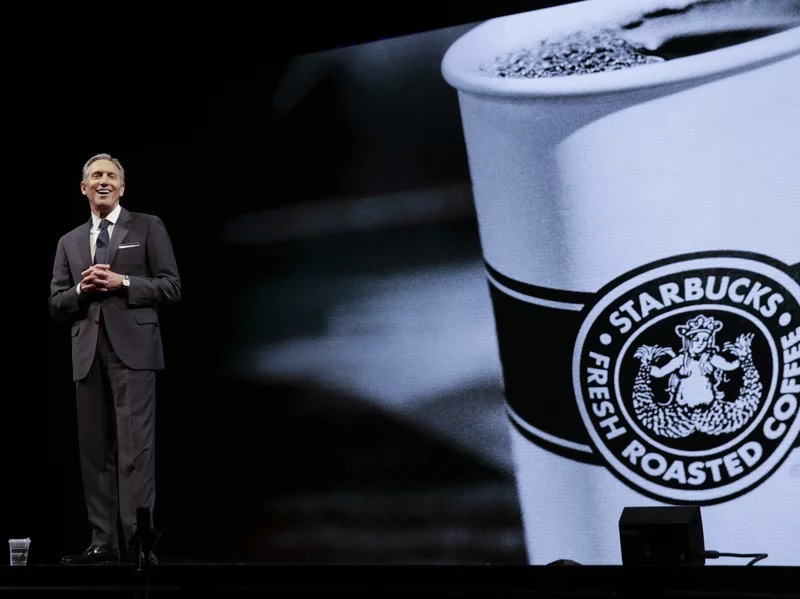
Starbucks is closing approximately 250 coffeehouses across North America, a move that shows how aggressively the company is reshaping its physical footprint while pursuing its broader “Back to Starbucks” turnaround strategy.

The closures represent roughly 1% of the company’s more than 18,000 North American coffeehouses, according to a September 24 memo from Chief Operating Officer Mike Grams.

The decision followed a review of Starbucks’ coffeehouse portfolio. According to Grams, the company identified locations where it could not consistently deliver the customer and employee experience it wanted or where there was no clear path to acceptable financial performance.

The closures therefore reflect not simply a reduction in stores, but an effort to concentrate resources on locations that management believes can better support the company’s strategy.

For employees, the corporate logic does not remove the immediate consequences. Starbucks said it is speaking directly with workers at affected locations and will seek transfer opportunities wherever possible.

Employees who cannot be placed in another coffeehouse will receive severance support, according to the memo. The timing is significant because Starbucks is simultaneously arguing that its North American business is improving.

Grams said customers are experiencing faster service, greater consistency and more welcoming coffeehouses. The company is also accelerating its program of coffeehouse uplifts, with more than 1,000 locations already redesigned across the United States and Canada since late 2025.

That creates an important distinction: Starbucks is not presenting the 250 closures as a retreat from North America. Instead, management describes them as part of portfolio management while maintaining a pipeline for new coffeehouses.

The company has repeatedly said that it expects long-term growth in the region. This approach fits the philosophy behind CEO Brian Niccol’s “Back to Starbucks” initiative.

The strategy is designed to return the company to a more traditional coffeehouse experience, emphasizing warmer stores, better service, operational simplicity and stronger connections between baristas and customers.

Two years into the strategy, Starbucks says it has made substantial progress in improving the customer experience while continuing to invest in its stores. The closures nevertheless highlight the difficult economics of operating a large retail network.

A recognizable brand can generate enormous value from scale, but scale also creates exposure to locations with different levels of traffic, rent, labor costs and local demand. A store that once made sense can become difficult to justify when customer behavior changes or operating expenses rise.

For Starbucks, the challenge is therefore to determine where physical presence strengthens the brand and where it becomes a drag on performance. Closing a location can reduce costs, but it can also disrupt employees, customers and communities that have built routines around a neighborhood coffeehouse.

The company’s next phase will reveal whether resources freed from weaker locations can translate into stronger stores, better service and sustainable growth. Starbucks says the objective is straightforward: every coffeehouse should be a place customers want to visit and employees are proud to work.

The 250 closures are consequently less about abandoning the coffeehouse model than redefining where that model should operate. Starbucks is shrinking selectively while simultaneously investing elsewhere. Its turnaround now depends on whether that sharper portfolio can deliver the consistency and financial performance management is seeking.