DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog

Dangote Refinery Opens Africa’s Biggest IPO as Investors Question $47 Billion Valuation

0

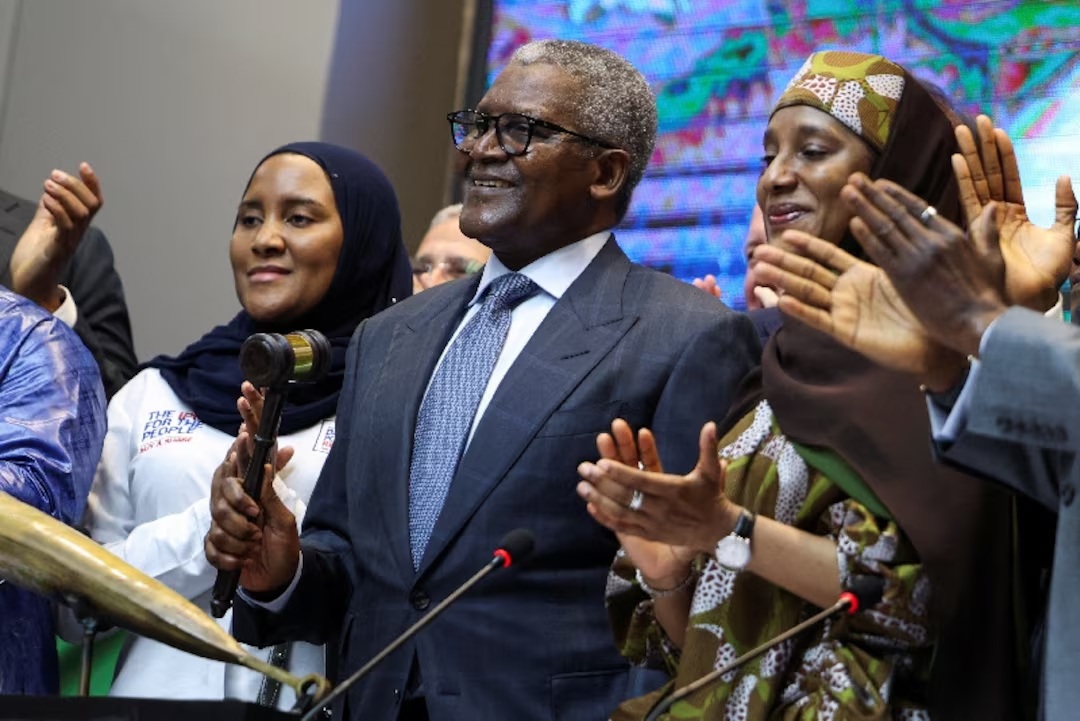
Nigerian billionaire Aliko Dangote on Monday opened Africa’s largest share offering to date, giving retail investors an opportunity to own part of his landmark oil refinery while raising as much as 2.15 trillion naira ($1.6 billion) to finance the plant’s expansion.

The initial public offering of Dangote Refinery opened at 8 a.m. local time and will run until October 13. The company is offering 4.1 billion ordinary shares at 525 naira each. If fully subscribed, the offer will raise 2.15 trillion naira, although proceeds could increase to about $2.1 billion if the offering is oversubscribed and the company exercises a greenshoe option to sell additional shares.

The scale of the offering is significant for Nigeria’s capital market, but the excitement surrounding the listing is being tempered by a fundamental question: how much future growth has already been priced into Dangote Refinery?

The offer values the refinery at about $47 billion, according to Reuters calculations, placing a substantial premium on its ability to expand production and earnings over the coming years.

For some Nigerian retail investors, however, the refinery’s size and Dangote’s reputation have been enough to outweigh concerns over the price.

Chris Chijioke, a Lagos-based business owner, said he planned to buy 2,000 shares, citing the scale of the refinery and Dangote’s track record.

But he also questioned the valuation.

“I personally think it is overvalued,” Chijioke told Reuters, adding that a delay in plans to double the refinery’s capacity could make the offer price difficult to justify.

That concern goes to the heart of the IPO. Investors are not simply buying into the refinery’s current earnings. They are paying for expectations that it will become substantially larger and more profitable.

Dangote Refinery currently processes about 700,000 barrels of crude oil a day and plans to increase capacity to 1.4 million barrels by 2029. The expansion is therefore central to the investment case underpinning the offering.

Refinery’s Importance Is Not the Same as Its Valuation

Built at a cost of about $20 billion on the outskirts of Lagos, the refinery has fundamentally altered Nigeria’s fuel market since beginning operations in 2024. It supplies most of the gasoline produced domestically and has become an increasingly important source of refined petroleum products for Nigeria and other markets.

The refinery has also benefited from disruptions to global energy supplies linked to the Iran war. Those disruptions increased demand for Dangote’s jet fuel in African and European markets, providing an additional boost to the company’s commercial prospects.

That position has helped make the refinery an unusually prominent Nigerian corporate asset. Dangote has also deliberately designed the IPO to bring ordinary Nigerians into its ownership structure, with investors able to buy as few as 10 shares through fintech companies and other digital investment platforms.

The response has been intense. Investment platforms including Bamboo experienced disruptions as investors rushed to participate in the offering.

Ibrahim Abubakar, a journalist, told Reuters he intended to buy about 2,850 shares because he considered the refinery “too big to fail.”

That sentiment captures part of the appeal of the IPO. Dangote Refinery is not simply another listed company. It sits at the center of Nigeria’s effort to reduce its dependence on imported refined petroleum products, giving it an economic and political importance that extends beyond conventional financial metrics.

But an asset can be economically important and still be overpriced. That possibility has been brought to the fore as analysts examine the assumptions embedded in the IPO valuation.

Financial analyst Feyi Fawehinmi said that the refinery’s earnings would need to rise substantially for the valuation to look comparable with companies in its peer group.

“If Dangote repeated its first-half performance for the rest of 2026, its annual earnings would be about $5.3 billion,” Fawehinmi wrote in a Substack post. “At the valuation implied in this IPO, those annual earnings would need to rise to about $8.4 billion for investors to be paying the same amount for each dollar of earnings as they do for the typical company in this peer group.”

That implies that earnings would need to increase by roughly 60% simply to bring the valuation into line with its peers, he said.

The argument highlights the risk facing retail investors drawn to the refinery’s scale and reputation. A company can continue growing rapidly while its stock produces disappointing returns if investors paid too much at the beginning.

Dangote has indicated that it expects demand for the IPO to resemble the strong reception for a private placement in July, which was 3.7 times oversubscribed. But demand for shares does not necessarily resolve the valuation question. An oversubscribed offering can demonstrate strong appetite without proving that the underlying price represents good value.

The refinery’s expansion plans are therefore crucial. Doubling capacity would give Dangote a much larger position in regional refined-product markets and potentially create substantial additional earnings capacity. But that growth also requires capital, reliable crude supplies, stable operations and continued demand for its products.

The IPO gives Dangote access to public-market capital at a scale that can help fund that expansion while broadening ownership beyond the billionaire and existing institutional investors. For Nigeria’s capital market, it also provides a rare opportunity to test whether retail investors will commit substantial savings to a large industrial asset rather than predominantly financial or consumer stocks.

For investors, however, the focal calculation is more demanding.

The refinery’s track record, its importance to Nigeria’s fuel supply and the disruptions in global energy markets may support a strong business outlook. But at an implied valuation of roughly $47 billion, much of the expected future success appears to be embedded in the price already.

The IPO therefore presents two different propositions at once. Dangote Refinery may be becoming one of Africa’s most consequential industrial companies, while its shares may still offer a less compelling investment if the projected expansion and earnings growth fail to arrive quickly enough.

That is the risk behind the enthusiasm. The refinery may be “too big to fail” in economic terms, but that does not mean its shares are too expensive to disappoint.
Saudi Stocks Extend Losses As Attacks On Oil Infrastructure And Shipping Routes Rattle Investors

0

Saudi Arabian stocks fell for a second straight session on Monday as escalating attacks on the kingdom’s energy infrastructure and shipping routes heightened concerns over the security of oil exports and broader economic activity in the Gulf.

Saudi Arabia’s benchmark TASI index slipped 0.3%, extending the previous session’s sharp decline. Oil giant Saudi Aramco fell 0.5%, while Saudi Arabian Mining Company and Saudi Basic Industries Corp declined 1% and 0.5%, respectively.

The selling pressure came after a drone strike temporarily disrupted Saudi Arabia’s East-West oil pipeline, an important route that allows the kingdom to transport crude without passing through the Strait of Hormuz.

The pipeline can carry as much as 4% of global oil supply, making any prolonged disruption a concern for energy markets. Sources said inventories at Yanbu port could support exports for only five to seven days if the disruption persists.

That prospect added to already elevated concerns over the security of Gulf energy infrastructure and maritime trade. Investors have been particularly sensitive to disruptions around the Strait of Hormuz, through which a significant share of global oil shipments passes.

Tensions also increased after reported Houthi attacks in southern Saudi Arabia and fresh incidents involving vessels near the strait.

Saudi state media on Sunday released footage showing damage to homes and a mosque in Jazan province, which it attributed to a Houthi attack. The Houthis separately said they had targeted a Saudi military base in a neighboring region.

The maritime risks intensified when a vessel in the Strait of Hormuz was struck by a projectile, causing a fire and forcing its crew to abandon ship, according to the UK Maritime Trade Operations agency.

The combination of attacks on Saudi infrastructure and shipping routes has created a fresh source of uncertainty for investors. Saudi Arabia has invested heavily in expanding and diversifying its economy, but the kingdom remains highly exposed to disruptions in the energy sector because of the importance of oil revenues to its economy and financial markets.

Geopolitical pressure also showed up in regional diplomacy. Iran’s foreign ministry said Saudi Arabia had requested that a planned meeting between Iran and Gulf states in Oman be postponed.

Gulf Markets Diverge As Investors Assess Risks

The selloff was not uniform across the Gulf.

Qatar’s benchmark index slipped 0.1%, while Dubai’s main share index rose 0.4%, supported by a 3.1% gain in blue-chip developer Emaar Properties.

Abu Dhabi’s benchmark also gained 0.4%, helped by a sharp rally in Space42.

Space42 jumped 10% after the company and California-based Viasat agreed to establish Equatys, a direct-to-device satellite communications platform. The companies have committed up to $1 billion to the venture.

The move put Space42 on track for its biggest single-day gain since July 4 last year.

The gap between Saudi Arabia and some of its Gulf neighbors shows that investors are differentiating between direct exposure to the latest security risks and companies positioned to benefit from other regional investment themes.

In Saudi Arabia, the immediate focus remained on energy infrastructure and the potential consequences of a prolonged disruption. Riyadh Cement was the biggest decliner on the benchmark, falling 5.8% after trading ex-dividend, while Arabian Drilling provided a notable counterpoint.

Arabian Drilling gained 2.2% after securing a five-year gas-drilling contract worth about 2 billion riyals ($532.5 million). The contract provided some support to the stock even as broader market sentiment weakened.

For Saudi equities, however, the more consequential question is how long the disruption to energy infrastructure and shipping can last. A temporary incident may have limited economic consequences if pipelines and ports quickly return to normal operations. A sustained disruption would be more significant, potentially affecting crude flows, inventories, shipping costs and investor confidence.

The East-West pipeline is especially important because it provides Saudi Arabia with an alternative route for moving oil when shipping through Hormuz becomes difficult. Any impairment therefore removes part of the kingdom’s ability to insulate its exports from disruptions around the strategically important waterway.

That makes the latest attacks a market issue beyond the immediate damage to individual facilities. Investors are now assessing whether repeated strikes could turn a geopolitical security problem into a sustained disruption to the Gulf’s energy and trade infrastructure.

For now, the contrasting performances across Riyadh, Dubai and Abu Dhabi show that investors have not treated the escalation as a uniform regional selloff. But with attacks affecting both oil infrastructure and commercial shipping, the risks facing Gulf markets are becoming increasingly tied to the duration and geographic spread of the conflict.

Zambia’s Democracy Under Scrutiny After Controversial Election Count

0

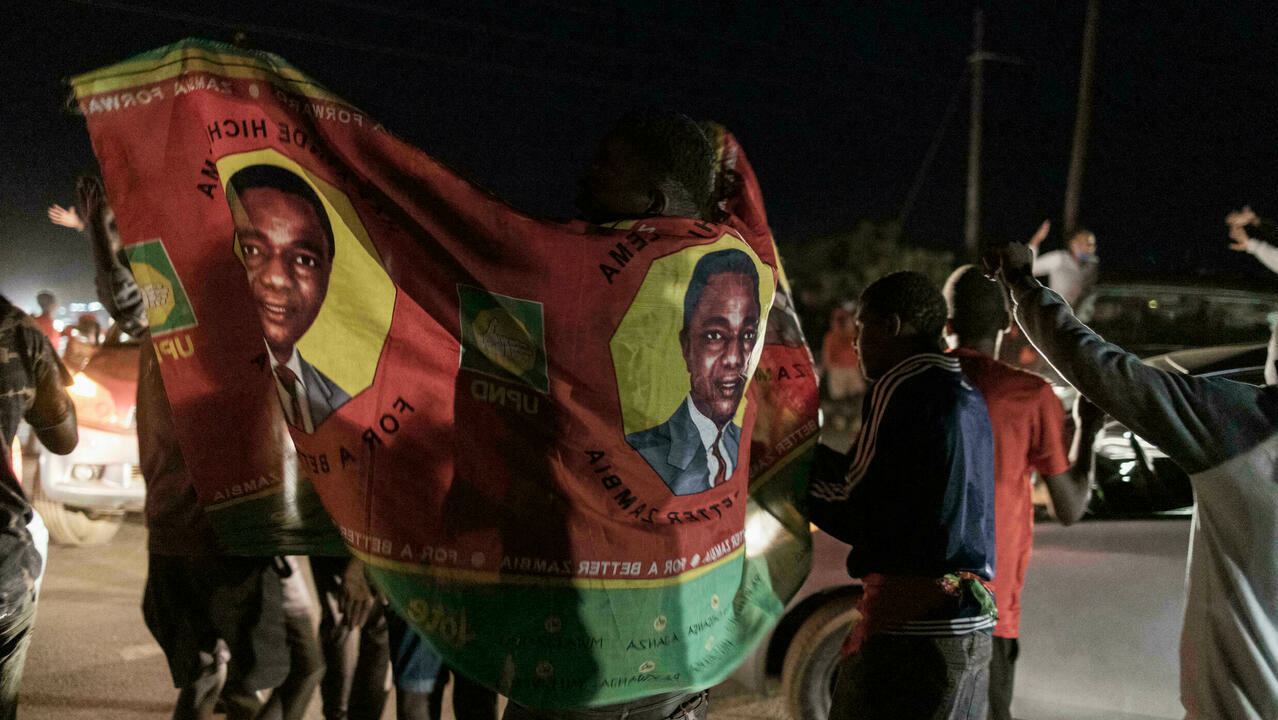
Zambia’s political landscape is entering another important phase after President Hakainde Hichilema was declared the winner of the presidential election with 60 per cent of the vote, securing a second term in office.

While polling day was largely peaceful, the period following the vote has been marked by controversy over the counting process, reported discrepancies in turnout figures and growing questions about the credibility of the electoral process.

The announcement by Zambia’s Electoral Commission was expected to provide political certainty after a closely watched election.

Hichilema’s victory gives his administration another mandate to pursue its economic programme, strengthen international partnerships and address some of the country’s longstanding fiscal and development challenges.

However, the dispute surrounding the vote count could complicate that mandate if opposition forces succeed in challenging the result. One of the central concerns involves reported differences between presidential and parliamentary turnout figures.

Such discrepancies can occur for legitimate administrative reasons, but they can also generate suspicion when electoral authorities do not provide sufficiently clear explanations.

For opposition supporters, the figures have become part of a broader argument that the election requires greater scrutiny before the result can be fully accepted.

Leading opposition candidate Brian Mundubile is considering a legal challenge, potentially shifting the dispute from the political arena into the courts. That development would place considerable importance on the independence and accessibility of Zambia’s judicial institutions.

Reports concerning court closures and the arrests of opposition figures have added another layer of controversy, raising concerns about whether political actors will have equal opportunities to contest the outcome through established legal channels.

The aftermath therefore matters almost as much as the election itself. Zambia has previously benefited from a reputation for relatively peaceful political transitions compared with some other countries in the region.

Maintaining that reputation depends not only on avoiding violence on election day but also on ensuring that electoral disputes are handled transparently, constitutionally and peacefully. For Hichilema, the second term presents both an opportunity and a challenge.

His government must translate electoral legitimacy into tangible economic improvements. Zambia continues to face pressure from debt obligations, inflationary concerns, unemployment and the need to attract investment.

Economic stability requires confidence from domestic businesses as well as international investors, and political uncertainty can influence investment decisions.

Investor confidence is particularly important because Zambia needs capital to support infrastructure, mining, energy and other productive sectors.

The country’s copper industry remains strategically significant, while the global transition toward electric vehicles and renewable energy has increased attention on copper and other critical minerals. A stable political environment could help Zambia capitalize on these opportunities.

Economic reforms can become politically difficult when they involve fiscal discipline, subsidy changes or measures that impose short-term costs on citizens. Hichilema’s second term will therefore require a balance between maintaining macroeconomic credibility and responding to public expectations for improved living standards.

Zambia’s political trajectory will depend on how the election dispute is managed. If concerns are addressed through credible institutions and transparent legal processes, the country can emerge from the controversy with its democratic reputation intact. If allegations are ignored or opposition participation is restricted, distrust could deepen.

The election has given Hichilema another mandate, but the legitimacy of that mandate will be shaped by what happens next. Zambia now faces a crucial test: whether its institutions can demonstrate that political competition, judicial independence and economic stability can coexist.

How that test is handled will influence not only the country’s democracy but also its attractiveness to investors and its position within Africa’s evolving political and economic landscape.

Meta Wants Its Managers Back As Andrew Tulloch Moves to Anthropic

0

The competition for artificial-intelligence talent is becoming as intense as the competition to build the technology itself.

Meta’s reported desire to bring some of its managers back comes at a moment when one of its notable AI researchers, Andrew Tulloch, has moved in the opposite direction, leaving Meta to join Anthropic and work on training and inference.

Tulloch’s departure is significant because the modern AI race is no longer determined solely by computing power, data centers or access to capital.

The people designing training systems, improving model performance and building inference infrastructure have become strategic assets. Companies can purchase GPUs and expand their data-center footprints, but experienced researchers and engineering leaders are considerably harder to replace.

Anthropic has emerged as one of the most formidable competitors in the frontier-AI industry. Its emphasis on advanced model development, enterprise applications and AI safety has attracted substantial investment and commercial interest.

Bringing in talent from Meta strengthens that position, particularly as Anthropic continues to push the boundaries of model training and inference. Training and inference represent two complementary sides of the AI infrastructure equation.

Training involves teaching increasingly capable models using enormous quantities of computational resources, while inference is the process through which those models generate responses and perform tasks for users.

Improvements in either area can have enormous commercial consequences, particularly as AI applications move from experimentation toward large-scale deployment.

For Meta, Tulloch’s move illustrates the broader challenge facing its AI ambitions. The company has invested aggressively in artificial intelligence, including substantial spending on infrastructure and the development of its Llama family of models.

Meta has also sought to recruit leading researchers and engineers as it attempts to compete with companies such as Anthropic, OpenAI and Google in frontier AI.

The irony is that while Meta is reportedly interested in bringing some managers back, its talent strategy remains part of a much larger industry churn. Employees are moving between major AI laboratories, startups and technology giants with unusual frequency.

Compensation packages have become extraordinarily competitive, but money alone does not determine where elite researchers choose to work. Access to cutting-edge compute, research freedom, leadership, company culture and the opportunity to influence the next generation of AI systems can be equally important.

Tulloch’s move therefore carries a message beyond one executive or researcher changing employers. It demonstrates how fluid the AI talent market has become. A leading scientist can move from one technological powerhouse to another and immediately become part of a different strategic effort.

For investors and technology watchers, the movement of AI personnel may increasingly deserve the same attention as chip purchases, model benchmarks and capital expenditure announcements. Talent can determine how effectively billions of dollars in infrastructure are converted into useful AI products.

Meta may be able to recruit managers back, expand its laboratories and deploy more computing capacity. But the departure of researchers such as Tulloch underscores an uncomfortable reality: in the frontier-AI race, companies are not merely competing to build the most powerful machines.

They are competing to retain the people capable of making those machines useful. Anthropic’s gain is consequently more than a personnel announcement. It is another indication that the AI arms race is becoming a battle for expertise—and that the most valuable asset in the industry may still be human intelligence.

Why Tech Billionaires Fear an AI Apocalypse—and Are Preparing for Societal Collapse

0

The artificial intelligence boom has produced extraordinary fortunes, but it has also created an unusual contradiction among technology’s most powerful executives: some of the people building the future are quietly preparing for the possibility that it could become dangerous.

Reports of underground bunkers, remote properties, private security and weapons stockpiles have transformed AI doomsday preparation into a symbol of Silicon Valley’s deepest anxieties.

These precautions are not evidence that catastrophe is inevitable. Rather, they reveal how seriously some wealthy technology leaders take the possibility of social disorder, technological accidents or a breakdown in the systems that sustain modern life.

The concern is rooted in AI’s extraordinary potential. Advanced systems could accelerate scientific discovery, automate complex work and reshape entire industries. Yet the same capabilities could also be misused, produce unpredictable outcomes or amplify existing political and economic tensions.

For executives whose fortunes depend on technological progress, the prospect of an AI-driven crisis is not merely a science-fiction scenario. It is a question of risk management. Some preparations reportedly resemble conventional disaster planning.

Wealthy individuals have invested in secure residences, remote land, backup power, food supplies and communications equipment. Underground shelters offer protection from civil unrest, extreme weather or other emergencies.

While isolation provides a degree of independence from crowded urban environments. In this sense, the bunker is less a prediction of the future than an insurance policy against uncertainty. More controversial are reports of firearms and ammunition stockpiles.

Such preparations reflect a belief that a severe crisis could weaken public institutions or create competition over scarce resources. But they also raise difficult questions about inequality and accountability.

A society in which the richest can purchase private security and fortified retreats is not necessarily a society that has become safer. It may instead be one in which access to safety is increasingly determined by wealth.

The psychology behind these preparations is equally important. Technology leaders are accustomed to thinking in terms of low-probability, high-impact events.

Entrepreneurs routinely invest in projects that may fail, while investors diversify portfolios against market shocks. Preparing for an AI catastrophe can therefore appear to be an extension of the same mindset: identify an extreme risk, estimate its consequences and build a contingency plan.

However, private survival strategies cannot substitute for public safeguards. If AI systems create serious risks, the consequences would extend far beyond the people who own them. Workers, consumers, governments and vulnerable communities would all be affected.

Effective preparation must therefore include robust testing, transparency, cybersecurity, emergency planning and clear rules for deploying increasingly capable systems. There is also a danger in allowing doomsday narratives to dominate the conversation.

Fear can encourage responsible investment in safety, but it can also distract from more immediate challenges, including labor displacement, misinformation, surveillance and unequal access to technology. The most useful response is neither complacency nor panic. It is disciplined preparation based on evidence.

The image of a tech billionaire retreating into a bunker captures a broader tension in the AI era. The people with the greatest resources to shape the future are also among those most aware of what could go wrong.

Their private precautions may be understandable, but the real measure of technological responsibility is whether society can build systems that make such precautions less necessary. The future of AI should not be defined by who can afford to escape it.

It should be defined by whether humanity can govern it wisely enough to ensure that technological progress remains a public benefit rather than a private gamble.