

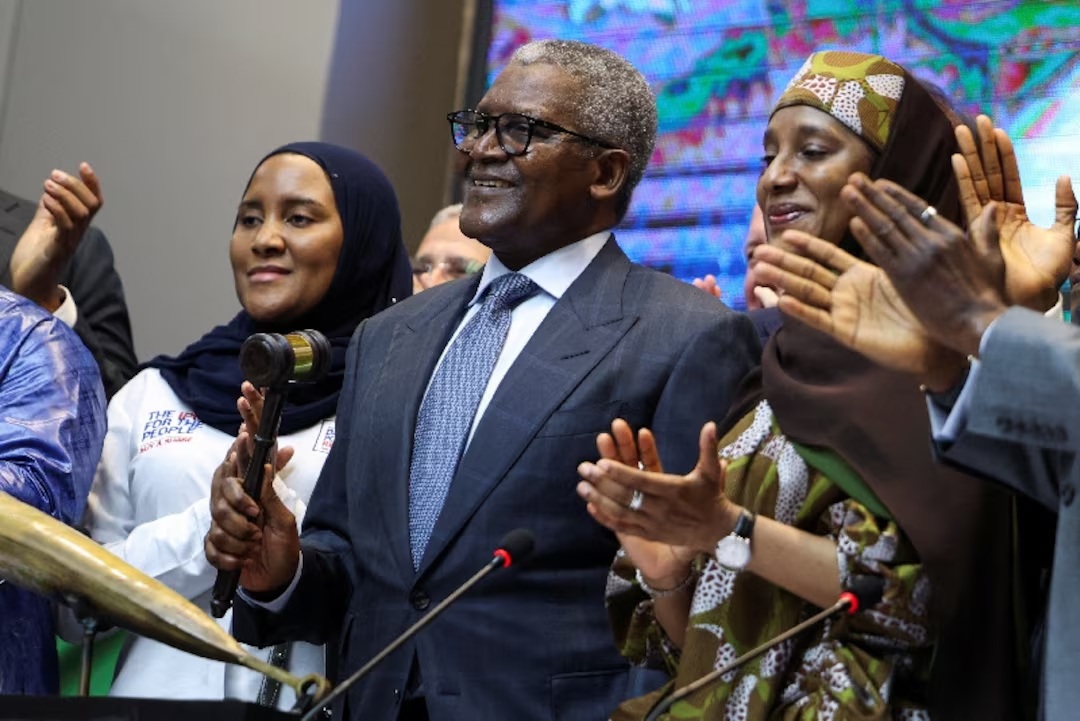
Nigerian billionaire Aliko Dangote on Monday opened Africa’s largest share offering to date, giving retail investors an opportunity to own part of his landmark oil refinery while raising as much as 2.15 trillion naira ($1.6 billion) to finance the plant’s expansion.
The initial public offering of Dangote Refinery opened at 8 a.m. local time and will run until October 13. The company is offering 4.1 billion ordinary shares at 525 naira each. If fully subscribed, the offer will raise 2.15 trillion naira, although proceeds could increase to about $2.1 billion if the offering is oversubscribed and the company exercises a greenshoe option to sell additional shares.
The scale of the offering is significant for Nigeria’s capital market, but the excitement surrounding the listing is being tempered by a fundamental question: how much future growth has already been priced into Dangote Refinery?
Register for the next Tekedia Mini-MBA.
Register for Tekedia AI in Business Masterclass.
Join Tekedia Capital Syndicate and co-invest in great global startups.
The offer values the refinery at about $47 billion, according to Reuters calculations, placing a substantial premium on its ability to expand production and earnings over the coming years.
For some Nigerian retail investors, however, the refinery’s size and Dangote’s reputation have been enough to outweigh concerns over the price.
Chris Chijioke, a Lagos-based business owner, said he planned to buy 2,000 shares, citing the scale of the refinery and Dangote’s track record.

But he also questioned the valuation.
“I personally think it is overvalued,” Chijioke told Reuters, adding that a delay in plans to double the refinery’s capacity could make the offer price difficult to justify.
That concern goes to the heart of the IPO. Investors are not simply buying into the refinery’s current earnings. They are paying for expectations that it will become substantially larger and more profitable.

Dangote Refinery currently processes about 700,000 barrels of crude oil a day and plans to increase capacity to 1.4 million barrels by 2029. The expansion is therefore central to the investment case underpinning the offering.
Refinery’s Importance Is Not the Same as Its Valuation
Built at a cost of about $20 billion on the outskirts of Lagos, the refinery has fundamentally altered Nigeria’s fuel market since beginning operations in 2024. It supplies most of the gasoline produced domestically and has become an increasingly important source of refined petroleum products for Nigeria and other markets.
The refinery has also benefited from disruptions to global energy supplies linked to the Iran war. Those disruptions increased demand for Dangote’s jet fuel in African and European markets, providing an additional boost to the company’s commercial prospects.
That position has helped make the refinery an unusually prominent Nigerian corporate asset. Dangote has also deliberately designed the IPO to bring ordinary Nigerians into its ownership structure, with investors able to buy as few as 10 shares through fintech companies and other digital investment platforms.
The response has been intense. Investment platforms including Bamboo experienced disruptions as investors rushed to participate in the offering.
Ibrahim Abubakar, a journalist, told Reuters he intended to buy about 2,850 shares because he considered the refinery “too big to fail.”
That sentiment captures part of the appeal of the IPO. Dangote Refinery is not simply another listed company. It sits at the center of Nigeria’s effort to reduce its dependence on imported refined petroleum products, giving it an economic and political importance that extends beyond conventional financial metrics.
But an asset can be economically important and still be overpriced. That possibility has been brought to the fore as analysts examine the assumptions embedded in the IPO valuation.
Financial analyst Feyi Fawehinmi said that the refinery’s earnings would need to rise substantially for the valuation to look comparable with companies in its peer group.
“If Dangote repeated its first-half performance for the rest of 2026, its annual earnings would be about $5.3 billion,” Fawehinmi wrote in a Substack post. “At the valuation implied in this IPO, those annual earnings would need to rise to about $8.4 billion for investors to be paying the same amount for each dollar of earnings as they do for the typical company in this peer group.”
That implies that earnings would need to increase by roughly 60% simply to bring the valuation into line with its peers, he said.
The argument highlights the risk facing retail investors drawn to the refinery’s scale and reputation. A company can continue growing rapidly while its stock produces disappointing returns if investors paid too much at the beginning.
Dangote has indicated that it expects demand for the IPO to resemble the strong reception for a private placement in July, which was 3.7 times oversubscribed. But demand for shares does not necessarily resolve the valuation question. An oversubscribed offering can demonstrate strong appetite without proving that the underlying price represents good value.
The refinery’s expansion plans are therefore crucial. Doubling capacity would give Dangote a much larger position in regional refined-product markets and potentially create substantial additional earnings capacity. But that growth also requires capital, reliable crude supplies, stable operations and continued demand for its products.
The IPO gives Dangote access to public-market capital at a scale that can help fund that expansion while broadening ownership beyond the billionaire and existing institutional investors. For Nigeria’s capital market, it also provides a rare opportunity to test whether retail investors will commit substantial savings to a large industrial asset rather than predominantly financial or consumer stocks.
For investors, however, the focal calculation is more demanding.
The refinery’s track record, its importance to Nigeria’s fuel supply and the disruptions in global energy markets may support a strong business outlook. But at an implied valuation of roughly $47 billion, much of the expected future success appears to be embedded in the price already.
The IPO therefore presents two different propositions at once. Dangote Refinery may be becoming one of Africa’s most consequential industrial companies, while its shares may still offer a less compelling investment if the projected expansion and earnings growth fail to arrive quickly enough.
That is the risk behind the enthusiasm. The refinery may be “too big to fail” in economic terms, but that does not mean its shares are too expensive to disappoint.