DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 21

ByteDance AI Drugmaking Unit Raises $290 Million at $1.5 Billion Valuation

0

ByteDance has raised $290 million for its artificial intelligence drug-discovery business after spinning the unit out of the Chinese internet giant, giving the fledgling company a $1.5 billion valuation and providing fresh capital for its expansion.

Shanghai-based Anew Labs completed its first external fundraising round, two people familiar with the matter told Reuters. The financing was led by HSG, formerly known as Sequoia China, IDG Capital and Hillhouse Investment, alongside 5Y Capital as a co-lead investor.

Other investors included Gaorong Ventures, Primavera Venture Partners and Boyu Capital, as well as strategic investor SBP Group and the state-backed Shanghai Future Industries Fund, the sources said. They spoke on condition of anonymity because the information has not been made public.

The financing marks a significant step for a company that was only recently separated from one of China’s largest technology groups. Anew Labs uses AI in drug discovery, a field where technology companies and investors are increasingly betting that machine learning can accelerate the identification of drug candidates and reduce some of the time and cost associated with conventional pharmaceutical research.

Anew Labs’ $1.5 billion valuation gives the business a substantial standalone market value despite its short history as an externally financed company. The fundraising also provides a new ownership structure under which ByteDance will retain a 56% stake, according to one of the sources.

The decision to spin out the unit reflects the different economics and operating requirements of AI drug discovery compared with ByteDance’s core internet businesses.

One source said ByteDance separated the AI drugmaker to better support its long-term development because AI-driven drug discovery follows a different industry logic and requires a different management approach from the group’s core operations.

Consumer internet businesses can often scale software products rapidly once they gain users, while drug discovery operates on a much longer development cycle and requires significant investment before commercial returns can emerge.

AI drug discovery also sits at the intersection of two capital-intensive industries. The technology requires substantial computing resources and specialized scientific talent, while successful drug development ultimately requires laboratory research, validation and, depending on the program, lengthy clinical development.

The new funding therefore gives Anew Labs the financial runway to develop its technology independently while retaining ByteDance as a majority shareholder.

ByteDance Builds an AI Portfolio Beyond Consumer Internet

The deal illustrates how Chinese technology companies are increasingly exploring AI applications outside the consumer products that made them global businesses.

ByteDance remains best known for TikTok and its Chinese counterpart Douyin, but the company has invested heavily in artificial intelligence across areas including foundation models, applications and infrastructure. Spinning out Anew Labs allows it to maintain exposure to another potentially valuable AI market while giving the drug-discovery business access to outside investors with expertise and capital specific to the sector.

The investor lineup is notable because it combines major Chinese venture and private-equity firms with a state-backed fund and a strategic investor.

That mix could provide Anew Labs with access to both financial resources and industry networks as it develops its technology. It also highlights the broader interest in AI as China seeks applications that extend beyond consumer-facing chatbots and into scientific research and industrial sectors.

The $1.5 billion valuation, however, should not be interpreted as evidence that AI has already transformed the economics of drug development. Drug discovery remains a high-risk business in which technical advances do not necessarily translate into successful medicines.

The value of an AI drug-discovery company ultimately depends on whether its models can identify promising compounds more efficiently, improve the probability of successful development, and translate those discoveries into commercially viable treatments. That makes the distinction between AI capability and pharmaceutical outcomes particularly important.

Anew Labs is entering a market where the potential payoff from successful drug candidates can be substantial, but where timelines are measured in years rather than the rapid product cycles common in consumer technology. The company’s ability to turn its AI capabilities into validated drug candidates will therefore matter more than the size of its initial funding round.

For ByteDance, retaining 56% means the company continues to have significant exposure to that upside while sharing the financing burden and bringing external investors into the business.

The structure could also give Anew Labs greater independence in attracting talent and capital. AI drug discovery requires expertise spanning machine learning, computational biology, chemistry, and pharmaceutical development, making it different from the engineering and product-management structures associated with ByteDance’s core platforms.

The fundraising is therefore as much about corporate structure as it is about capital.

ByteDance has effectively created a standalone vehicle through which investors can finance an AI application with a distinct development cycle, while the parent company preserves majority control.

For the wider Chinese AI industry, the deal adds to evidence that investment is moving beyond general-purpose models toward specialized applications where AI can potentially create value in sectors with high research costs.
Meta Unveils Meta One Subscriptions as It Looks to Monetize AI and Expand Beyond Advertising

0

Meta is expanding its subscription business across Facebook, Instagram and WhatsApp as the company looks to turn its growing investment in artificial intelligence into a new source of recurring revenue.

The company on Tuesday introduced Meta One, a collection of subscription plans offering expanded access to AI tools and premium features across its major social platforms. The plans give users greater access to tools for generating and editing images and videos, along with AI-powered features such as Instagram’s Restyle editing tool.

The move represents a broader monetization push for Meta’s AI ambitions. Rather than relying solely on advertising to recover the cost of developing expensive AI models and infrastructure, the company is now asking users, creators, and businesses to pay directly for greater access to those capabilities.

Meta’s AI strategy has expanded substantially since its $14.3 billion investment in Scale AI in 2025, which brought Scale AI CEO Alexandr Wang into Meta to lead its AI efforts. The new subscriptions provide a potential commercial channel for those investments by putting Meta’s Muse AI models directly behind paid tiers.

The announcement follows Meta’s introduction of separate subscription offerings for its social platforms in March. Instagram Plus and Facebook Plus cost $3.99 a month, while WhatsApp Plus costs $2.99, giving subscribers features such as profile customization, super reactions and story insights.

Early revenue data suggests those lower-priced offerings are gaining traction.

Market intelligence firm Appfigures estimates that Instagram’s average daily worldwide revenue reached $1.2 million during the week of Sept. 9, up 475% from the previous week. Facebook’s daily revenue reached $528,000, representing a 143% increase over the same period.

The figures suggest Meta may have found a potentially significant new monetization channel outside its advertising business, although the sharp week-to-week increases also reflect the relatively recent introduction of the subscriptions.

Meta targets AI power users, creators and businesses

Meta One’s consumer offerings are centered on two plans: Core at $7.99 a month and Premium at $19.99.

Both include the existing Facebook Plus, Instagram Plus, and WhatsApp Plus benefits, while their main differentiator is expanded access to Meta’s AI tools. Premium subscribers receive more AI usage than Core subscribers, allowing them to make greater use of features including Muse Image and Muse Video.

Subscribers can also use AI to edit Instagram Stories through Restyle and gain increased access to voice effects and other creative tools. The structure effectively creates a new premium layer around Meta’s social platforms. Users who want to use AI occasionally can continue with free tools, while those generating images, videos, or other content more frequently have an incentive to move to paid plans.

Meta is also targeting businesses and creators with substantially more expensive subscriptions.

Its business and creator lineup begins with Essential at $14.99 a month and rises through Advanced, starting at $49.99, Expert at $149, and Max at $499. Essential provides tools for managing a creator or business presence, expanded access to Meta Business Agent for responding to customers, a verified badge and channel on WhatsApp Business, as well as impersonation detection.

Advanced adds scheduling for Stories up to 30 days in advance, links in organic posts and Reels, exportable analytics, deeper audience insights, team-member access, additional linked devices, more business broadcast credits, and greater access to Meta Business Agent responses.

Meta is also introducing enhanced profiles for Essential and Advanced users that can highlight websites, locations and reviews. Reels will receive a more prominent follow button, while people who interact with content can automatically receive follow invitations.

The company plans to add more agent capabilities over time, including tools designed around marketing, business operations, content creation, and optimization. It will also introduce Edits Plus for Meta’s Edits content-creation app. The subscription will provide additional cloud storage for syncing projects across devices and increased access to the Edits AI assistant.

Expert and Max customers will receive the highest levels of feature access and Meta Business Agent capacity.

While the complex collection of plans could make Meta’s subscription strategy difficult for consumers to navigate, the underlying commercial objective is to create multiple payment tiers based on how heavily users depend on Meta’s platforms and AI services.

Subscription Push Could Become A Meaningful Revenue Stream

The early performance of Meta’s cheaper social subscriptions is giving investors a reason to take the strategy seriously.

Appfigures said U.S. users accounted for 32% of Instagram’s revenue and 39% of Facebook’s revenue after the subscriptions gained traction on Sept. 9, roughly 10% above each platform’s historical U.S. baseline.

The potential revenue opportunity becomes much larger if Meta can persuade users to pay not merely for cosmetic social features but for access to increasingly valuable AI capabilities.

BNP Paribas forecasts that Meta’s subscription push could add $13.5 billion in revenue by 2028, while Truist estimates the company could generate an additional $20 billion by 2030.

Those forecasts would still represent only a portion of Meta’s overall business, but they point to an important shift in the company’s monetization model. Advertising remains the economic engine of Facebook and Instagram, yet subscriptions could give Meta a second recurring revenue stream while simultaneously helping it monetize the costly AI systems it is building.

The approach is needed because AI infrastructure requires significant ongoing spending rather than a one-time investment. Meta therefore needs its AI capabilities to generate economic value, either by improving advertising, increasing engagement, or creating direct revenue.

Meta One addresses the third option.

The bigger test will be whether consumers see enough value in AI-generated content and productivity features to pay monthly fees when many competing AI tools are available separately. For businesses and creators, the calculation may be easier if Meta’s agents can demonstrably save time, improve customer response rates, or generate more revenue.

However, Meta’s subscription expansion is seen as an attempt to turn the company’s AI infrastructure from a largely cost-intensive investment into a direct consumer and business product, while deepening the commercial relationship between Meta and the users who already spend much of their time inside its ecosystem.

Strive Reaches 25,000 BTC as Corporate Bitcoin Treasuries as Noun Digital Business Finance Expand

0

The convergence of corporate Bitcoin accumulation and new forms of shared financial infrastructure is becoming one of the more revealing themes in the digital-asset economy. Strive’s Bitcoin treasury has reached an even 25,000 BTC following a $36.6 million purchase, while Nous has introduced Hermes Business team accounts with shared balances.

On the surface, the announcements belong to different categories. One concerns corporate exposure to Bitcoin; the other concerns how businesses manage money. Together, however, they point toward a financial system increasingly shaped by programmable assets, collective ownership and digital-native treasury management.

Strive’s latest acquisition takes its Bitcoin strategy into a psychologically important milestone. Holding 25,000 BTC places the company among the growing group of institutions treating Bitcoin not merely as a speculative asset, but as a strategic treasury reserve.

The $36.6 million purchase also demonstrates how corporate Bitcoin strategies can be executed incrementally, allowing a company to build substantial exposure through repeated acquisitions rather than relying on a single large transaction.

The significance of the 25,000-BTC threshold extends beyond the headline figure. Bitcoin treasuries are increasingly becoming a corporate-finance strategy in which companies seek exposure to an asset with a fixed maximum supply while maintaining an operating business around it.

For shareholders, this creates a different way of evaluating corporate value. Investors must consider not only revenue, cash flow and profitability, but also the size, acquisition cost and financing structure of a company’s digital-asset holdings. Yet Bitcoin treasury strategies carry their own risks.

Bitcoin remains volatile, and a company accumulating thousands of coins can experience substantial changes in the value of its balance sheet. Financing costs, dilution, liquidity requirements and market conditions can also influence whether aggressive accumulation creates or destroys shareholder value.

The strategy therefore depends not simply on owning Bitcoin, but on managing the relationship between the asset, corporate capital and long-term business objectives.

Meanwhile, Nous’s Hermes Business team accounts approach finance from a different direction. Shared balances are designed around the reality that modern businesses rarely operate through a single individual.

Founders, executives, finance teams and operational staff often need coordinated access to funds while maintaining organizational controls. A team-oriented account structure can make financial management more collaborative and potentially reduce the friction associated with traditional business banking.

The connection between the two developments becomes clearer when viewed through the lens of financial infrastructure. Bitcoin is challenging assumptions about what can serve as corporate money, while products such as Hermes Business challenge assumptions about how corporate money should be administered.

Both trends move financial activity toward software-driven systems in which assets, permissions and transactions can be managed digitally. This evolution could become particularly important as companies increasingly operate across borders and interact with digital assets, stablecoins and tokenized financial instruments.

Businesses will require infrastructure capable of supporting multiple participants without sacrificing visibility or control. Shared balances are one piece of that puzzle; corporate digital-asset treasuries are another.

Strive’s 25,000 BTC milestone therefore represents more than another corporate purchase. Nous’s Hermes Business accounts represent more than another fintech feature. They illustrate a financial landscape in which companies are experimenting simultaneously with what they hold and how they coordinate it.

The emerging corporate treasury may become more digital, more programmable and more closely connected to blockchain-based assets than the traditional balance sheet ever was.

BMW iX3 Nears 100,000 European Orders One Year After Launch, Signaling Strong Demand for New-Generation EVs

0

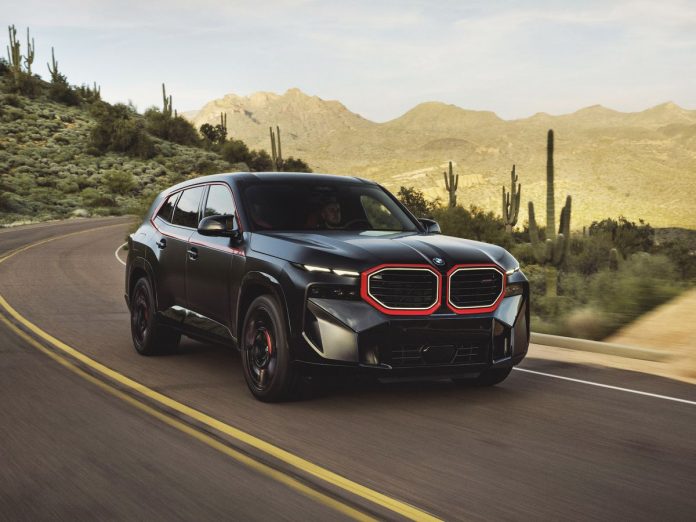
The BMW iX3 is emerging as a significant milestone in the German automaker’s transition toward a new generation of electric mobility. Roughly a year after the vehicle’s world premiere, BMW says it is approaching 100,000 orders in Europe.

Highlighting strong customer interest in the first model built around its Neue Klasse technology platform. The new iX3 was unveiled at the IAA Mobility show in Munich in September 2025 as the first production model of BMW’s Neue Klasse.

Rather than treating the vehicle as simply another electric SUV, BMW positioned it as the beginning of a broader technological and design transformation that will extend across its portfolio.

The company plans to introduce more than 40 new or updated models by 2027, with Neue Klasse technologies gradually spreading throughout the range.

The speed of the iX3’s order intake is particularly notable. By the end of March 2026, BMW had already recorded more than 50,000 European orders. By mid-2026, the company said it was on course to reach the 100,000-order milestone.

BMW’s latest announcement indicates that the vehicle is now nearing that level, demonstrating that demand has remained strong beyond the initial excitement surrounding its launch. The figures provide an important indication of how BMW’s electric strategy is developing in its home region.

In the second quarter of 2026, BMW Group deliveries of fully electric vehicles in Europe reached 81,445 units, representing growth of about 38% from the previous year. During the first half of the year, fully electric vehicles represented around 28% of BMW Group sales in Europe.

The iX3 has become a particularly important component of that expansion. BMW says that since the model’s world premiere, approximately one in three fully electric BMW vehicles ordered in Europe has been an iX3. Within the broader X3 family, one out of every two orders is now for the fully electric version.

Those figures suggest that electrification is increasingly penetrating one of BMW’s most important vehicle segments.  Production has had to respond to the strength of demand.

BMW manufactures the new iX3 at its Debrecen plant in Hungary, where the company introduced a second shift earlier than originally planned. BMW has described the production ramp-up as exceptionally fast, with the plant reaching 50,000 iX3 vehicles produced since the start of series production.

The vehicle represents a technological statement from BMW. The company says the iX3 can achieve up to 805 kilometres of range under the WLTP testing cycle, while its Neue Klasse architecture introduces new technology clusters and an updated design language.

More broadly, the iX3’s reception arrives at an important moment for the European automotive industry. Automakers are balancing the transition toward electric vehicles with varying consumer demand, charging infrastructure, pricing pressures and competition from established and emerging manufacturers.

BMW’s strategy has been to maintain a broad drivetrain portfolio while expanding its battery-electric range. The approaching 100,000-order milestone therefore carries significance beyond one vehicle. It provides BMW with evidence that its Neue Klasse strategy can generate substantial demand in Europe.

The next challenge will be translating orders into efficient production, timely deliveries and sustained demand as more Neue Klasse models reach customers. The iX3 has moved from being the opening chapter of its electric transformation to becoming one of its clearest early indicators of how customers may respond to the company’s next generation of vehicles.

Why Foreign Investors Keep Buying US Corporate Bonds Despite 5% Treasury Yields

0

Foreign investors have continued pouring money into U.S. corporate bonds even as Treasury yields have surged to their highest levels in years, challenging expectations that higher borrowing costs and currency-hedging expenses would push overseas investors away from American credit markets.

Net foreign purchases of U.S. corporate bonds reached $251 billion through the end of June, putting 2026 on track to approach last year’s record $392 billion, according to an analysis by Goldman Sachs chief credit strategist Amanda Lynam.

The resilience of overseas demand is notable because the benchmark 10-year Treasury yield closed at 5% on Tuesday after reaching its highest level since 2007. The move has intensified concerns about how much further yields could rise and whether expensive U.S. borrowing costs could weaken demand for dollar-denominated assets.

So far, foreign investors have continued buying.

“This is notable as the foreign appetite for US credit has persisted despite a range of headwinds in recent years, including fluctuations in the strength of the dollar and the cost of hedging,” Lynam wrote in a Tuesday note.

Foreign investors own roughly 29% of the U.S. corporate bond market, giving them an important role in determining demand and financing conditions for American companies.

Their continued participation suggests that higher Treasury yields have not yet fundamentally altered the relative attractiveness of U.S. corporate credit. Instead, overseas investors appear willing to absorb higher rates in exchange for the income and liquidity available in the world’s largest corporate bond market.

Higher Yields Have Not Broken Foreign Demand

The resilience of foreign demand comes at a critical point for U.S. fixed-income markets. Investors are assessing whether higher borrowing costs will put additional pressure on corporate bonds and other risk assets as they await the Federal Reserve’s policy decision on Wednesday. The rise in Treasury yields has already increased the benchmark against which corporate borrowing costs are priced.

Normally, a sharp increase in domestic yields can create several obstacles for foreign investors. Higher Treasury rates can make other markets relatively more attractive, while a stronger or more volatile dollar can alter returns for investors whose portfolios are denominated in other currencies. Currency hedging can further reduce the effective yield earned by overseas buyers.

Those forces have generated repeated predictions that foreign investors would eventually reduce their exposure to U.S. assets.

The data have not yet supported that outcome.

Europe has been the biggest source of foreign demand for U.S. corporate bonds since early 2022, accounting for 52% of net foreign purchases, according to Goldman. Asia accounted for 21%.

The figures also put the focus on Japan, where domestic bond yields have risen as policymakers have moved away from the ultra-loose monetary conditions that for years encouraged Japanese institutions to invest abroad.

A sustained increase in Japanese government bond yields could make domestic assets more competitive and encourage insurers, pension funds and other institutions to repatriate capital. That possibility has been closely watched by U.S. bond investors because Japanese institutions have historically been major participants in global fixed-income markets.

Goldman, however, expects any further decline in Japanese holdings of U.S. investment-grade and high-yield corporate bonds to remain manageable relative to the overall market. That assessment rests partly on the sheer scale and liquidity of the U.S. corporate bond market.

Few Alternatives Match the U.S. Market

For international investors, the decision is not simply whether U.S. yields have become more expensive. It is also what assets can replace them.

The U.S. corporate bond market offers a combination of scale, liquidity, credit diversity, and tradability that is difficult to reproduce elsewhere. Large institutional investors can deploy substantial amounts of capital across investment-grade and high-yield securities without necessarily sacrificing the ability to trade.

That market depth comes to the fore when investors are managing large portfolios. A modest improvement in the relative attractiveness of domestic bonds may not be sufficient to justify moving hundreds of billions of dollars out of a market that offers a much broader pool of issuers and securities.

Goldman therefore expects a floor to remain under foreign purchases of U.S.-domiciled credit and considers a broad repatriation of overseas capital unlikely.

“We continue to expect a floor to remain under foreign purchases of US-domiciled credit, and view a broader repatriation of flows as unlikely,” Lynam wrote.

The distinction between foreign demand for Treasuries and demand for corporate credit is also important. Corporate bonds offer investors additional compensation for taking credit risk, meaning that higher Treasury yields can actually provide a larger overall income opportunity when corporate spreads remain contained.

That does not make the market immune to a further rise in rates. If Treasury yields remain elevated, companies refinancing debt will face higher interest expenses, while existing bonds can suffer price declines as newly issued securities offer higher coupons. A deterioration in economic conditions could also widen corporate credit spreads and increase losses for investors.

But the foreign-flow data suggest that those risks have not yet been sufficient to trigger a broad withdrawal.

The bigger test may come if high Treasury yields persist rather than simply rise temporarily. A 5% 10-year yield changes the economics of global portfolios more substantially when investors believe rates will remain elevated for years. It can also alter corporate financing decisions, equity valuations and the relative appeal of other developed-market bonds.

For now, however, foreign investors appear to be treating the higher U.S. yield environment as an opportunity rather than a reason to abandon the market. That leaves U.S. corporate borrowers with an important source of external demand even as domestic financial conditions tighten. It also suggests that the long-running concern over foreign investors turning away from U.S. assets may be more complicated than a simple comparison of Treasury yields.

The dollar, hedging costs, domestic yields, and geopolitical considerations all matter. But so does market structure. Until another market can offer comparable scale and liquidity, Goldman expects foreign capital to keep finding its way into U.S. corporate credit.