DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 25

BMW iX3 Nears 100,000 European Orders One Year After Launch, Signaling Strong Demand for New-Generation EVs

0

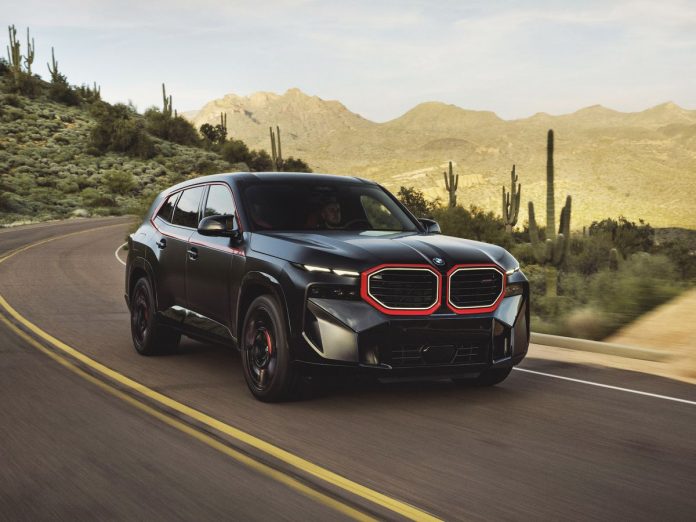
The BMW iX3 is emerging as a significant milestone in the German automaker’s transition toward a new generation of electric mobility. Roughly a year after the vehicle’s world premiere, BMW says it is approaching 100,000 orders in Europe.

Highlighting strong customer interest in the first model built around its Neue Klasse technology platform. The new iX3 was unveiled at the IAA Mobility show in Munich in September 2025 as the first production model of BMW’s Neue Klasse.

Rather than treating the vehicle as simply another electric SUV, BMW positioned it as the beginning of a broader technological and design transformation that will extend across its portfolio.

The company plans to introduce more than 40 new or updated models by 2027, with Neue Klasse technologies gradually spreading throughout the range.

The speed of the iX3’s order intake is particularly notable. By the end of March 2026, BMW had already recorded more than 50,000 European orders. By mid-2026, the company said it was on course to reach the 100,000-order milestone.

BMW’s latest announcement indicates that the vehicle is now nearing that level, demonstrating that demand has remained strong beyond the initial excitement surrounding its launch. The figures provide an important indication of how BMW’s electric strategy is developing in its home region.

In the second quarter of 2026, BMW Group deliveries of fully electric vehicles in Europe reached 81,445 units, representing growth of about 38% from the previous year. During the first half of the year, fully electric vehicles represented around 28% of BMW Group sales in Europe.

The iX3 has become a particularly important component of that expansion. BMW says that since the model’s world premiere, approximately one in three fully electric BMW vehicles ordered in Europe has been an iX3. Within the broader X3 family, one out of every two orders is now for the fully electric version.

Those figures suggest that electrification is increasingly penetrating one of BMW’s most important vehicle segments.  Production has had to respond to the strength of demand.

BMW manufactures the new iX3 at its Debrecen plant in Hungary, where the company introduced a second shift earlier than originally planned. BMW has described the production ramp-up as exceptionally fast, with the plant reaching 50,000 iX3 vehicles produced since the start of series production.

The vehicle represents a technological statement from BMW. The company says the iX3 can achieve up to 805 kilometres of range under the WLTP testing cycle, while its Neue Klasse architecture introduces new technology clusters and an updated design language.

More broadly, the iX3’s reception arrives at an important moment for the European automotive industry. Automakers are balancing the transition toward electric vehicles with varying consumer demand, charging infrastructure, pricing pressures and competition from established and emerging manufacturers.

BMW’s strategy has been to maintain a broad drivetrain portfolio while expanding its battery-electric range. The approaching 100,000-order milestone therefore carries significance beyond one vehicle. It provides BMW with evidence that its Neue Klasse strategy can generate substantial demand in Europe.

The next challenge will be translating orders into efficient production, timely deliveries and sustained demand as more Neue Klasse models reach customers. The iX3 has moved from being the opening chapter of its electric transformation to becoming one of its clearest early indicators of how customers may respond to the company’s next generation of vehicles.

Why Foreign Investors Keep Buying US Corporate Bonds Despite 5% Treasury Yields

0

Foreign investors have continued pouring money into U.S. corporate bonds even as Treasury yields have surged to their highest levels in years, challenging expectations that higher borrowing costs and currency-hedging expenses would push overseas investors away from American credit markets.

Net foreign purchases of U.S. corporate bonds reached $251 billion through the end of June, putting 2026 on track to approach last year’s record $392 billion, according to an analysis by Goldman Sachs chief credit strategist Amanda Lynam.

The resilience of overseas demand is notable because the benchmark 10-year Treasury yield closed at 5% on Tuesday after reaching its highest level since 2007. The move has intensified concerns about how much further yields could rise and whether expensive U.S. borrowing costs could weaken demand for dollar-denominated assets.

So far, foreign investors have continued buying.

“This is notable as the foreign appetite for US credit has persisted despite a range of headwinds in recent years, including fluctuations in the strength of the dollar and the cost of hedging,” Lynam wrote in a Tuesday note.

Foreign investors own roughly 29% of the U.S. corporate bond market, giving them an important role in determining demand and financing conditions for American companies.

Their continued participation suggests that higher Treasury yields have not yet fundamentally altered the relative attractiveness of U.S. corporate credit. Instead, overseas investors appear willing to absorb higher rates in exchange for the income and liquidity available in the world’s largest corporate bond market.

Higher Yields Have Not Broken Foreign Demand

The resilience of foreign demand comes at a critical point for U.S. fixed-income markets. Investors are assessing whether higher borrowing costs will put additional pressure on corporate bonds and other risk assets as they await the Federal Reserve’s policy decision on Wednesday. The rise in Treasury yields has already increased the benchmark against which corporate borrowing costs are priced.

Normally, a sharp increase in domestic yields can create several obstacles for foreign investors. Higher Treasury rates can make other markets relatively more attractive, while a stronger or more volatile dollar can alter returns for investors whose portfolios are denominated in other currencies. Currency hedging can further reduce the effective yield earned by overseas buyers.

Those forces have generated repeated predictions that foreign investors would eventually reduce their exposure to U.S. assets.

The data have not yet supported that outcome.

Europe has been the biggest source of foreign demand for U.S. corporate bonds since early 2022, accounting for 52% of net foreign purchases, according to Goldman. Asia accounted for 21%.

The figures also put the focus on Japan, where domestic bond yields have risen as policymakers have moved away from the ultra-loose monetary conditions that for years encouraged Japanese institutions to invest abroad.

A sustained increase in Japanese government bond yields could make domestic assets more competitive and encourage insurers, pension funds and other institutions to repatriate capital. That possibility has been closely watched by U.S. bond investors because Japanese institutions have historically been major participants in global fixed-income markets.

Goldman, however, expects any further decline in Japanese holdings of U.S. investment-grade and high-yield corporate bonds to remain manageable relative to the overall market. That assessment rests partly on the sheer scale and liquidity of the U.S. corporate bond market.

Few Alternatives Match the U.S. Market

For international investors, the decision is not simply whether U.S. yields have become more expensive. It is also what assets can replace them.

The U.S. corporate bond market offers a combination of scale, liquidity, credit diversity, and tradability that is difficult to reproduce elsewhere. Large institutional investors can deploy substantial amounts of capital across investment-grade and high-yield securities without necessarily sacrificing the ability to trade.

That market depth comes to the fore when investors are managing large portfolios. A modest improvement in the relative attractiveness of domestic bonds may not be sufficient to justify moving hundreds of billions of dollars out of a market that offers a much broader pool of issuers and securities.

Goldman therefore expects a floor to remain under foreign purchases of U.S.-domiciled credit and considers a broad repatriation of overseas capital unlikely.

“We continue to expect a floor to remain under foreign purchases of US-domiciled credit, and view a broader repatriation of flows as unlikely,” Lynam wrote.

The distinction between foreign demand for Treasuries and demand for corporate credit is also important. Corporate bonds offer investors additional compensation for taking credit risk, meaning that higher Treasury yields can actually provide a larger overall income opportunity when corporate spreads remain contained.

That does not make the market immune to a further rise in rates. If Treasury yields remain elevated, companies refinancing debt will face higher interest expenses, while existing bonds can suffer price declines as newly issued securities offer higher coupons. A deterioration in economic conditions could also widen corporate credit spreads and increase losses for investors.

But the foreign-flow data suggest that those risks have not yet been sufficient to trigger a broad withdrawal.

The bigger test may come if high Treasury yields persist rather than simply rise temporarily. A 5% 10-year yield changes the economics of global portfolios more substantially when investors believe rates will remain elevated for years. It can also alter corporate financing decisions, equity valuations and the relative appeal of other developed-market bonds.

For now, however, foreign investors appear to be treating the higher U.S. yield environment as an opportunity rather than a reason to abandon the market. That leaves U.S. corporate borrowers with an important source of external demand even as domestic financial conditions tighten. It also suggests that the long-running concern over foreign investors turning away from U.S. assets may be more complicated than a simple comparison of Treasury yields.

The dollar, hedging costs, domestic yields, and geopolitical considerations all matter. But so does market structure. Until another market can offer comparable scale and liquidity, Goldman expects foreign capital to keep finding its way into U.S. corporate credit.

SK Hynix in Talks With Intel to Make Memory Chips in U.S. for First Time

0

South Korea’s SK Hynix is in talks with Intel about a potential deal that could bring the memory-chip maker’s manufacturing operations to U.S. soil for the first time, three people familiar with the discussions told Reuters, in a move that could reshape part of the supply chain for chips critical to artificial intelligence and data centers.

One option under discussion would see SK Hynix lease part of Intel’s long-planned semiconductor manufacturing complex in Ohio, two of the people said. Another possibility is a joint venture involving Intel and major cloud companies that want to secure reliable supplies of memory chips as AI infrastructure investment drives demand and tightens availability.

The discussions remain exploratory, and no agreement has been reached. One source said SK Hynix is considering multiple structures and that the company could ultimately pursue a different arrangement.

The talks nevertheless illustrate the growing pressure on memory-chip manufacturers to establish production capacity closer to their biggest customers. They also offer Intel a potential way to put its underused or delayed Ohio investment to work while sharing some of the enormous cost of building semiconductor manufacturing capacity in the United States.

For the Trump administration, an SK Hynix commitment would provide another high-profile example of a major Asian semiconductor company expanding manufacturing in the United States. Washington has been pushing chipmakers to invest domestically as it seeks to reduce dependence on Asian supply chains and capitalize on the rapid expansion of AI computing and data centers.

The discussions could become more complicated if SK Hynix seeks to manufacture advanced memory technologies in Ohio.

Seoul Faces a Semiconductor Dilemma

SK Hynix produces a broad range of memory products, including DRAM used in servers, PCs, and smartphones and NAND flash used for data storage. It is also one of the world’s leading suppliers of high-bandwidth memory, or HBM, a critical component in AI processors because it allows chips to move large amounts of data rapidly.

The sources said any proposal involving advanced memory such as HBM, or potentially even certain DRAM technologies, could face scrutiny from the South Korean government because the technologies are considered sensitive.

SK Hynix told Reuters that it was “reviewing various measures, including establishing additional production bases, to strengthen the competitiveness of its memory business,” but said that “no matters have been determined at this stage.”

Intel declined to comment on what it called speculation, while saying it continues to invest in Ohio and prepare the site.

South Korea’s trade ministry said decisions about overseas investment would be up to the company, but projects involving a designated “national core technology” would be subject to review under the country’s Industrial Technology Protection Act.

The situation has resulted in a difficult policy balancing act for Seoul. SK Hynix is under pressure to serve rapidly expanding global demand, particularly from U.S. technology companies, but South Korea also wants to preserve semiconductor manufacturing and technological capabilities domestically.

The issue has become sensitive because the government has been encouraging SK Hynix and rival Samsung Electronics to accelerate construction of a semiconductor manufacturing cluster in southwestern South Korea. Moving some advanced production to the United States could therefore satisfy Washington while potentially complicating Seoul’s efforts to deepen its domestic semiconductor base.

There are also significant economic disadvantages to U.S. production. Manufacturing chips in America is considerably more expensive than in South Korea because of higher labor and construction costs, according to two of the sources. Much of the semiconductor supply chain, including equipment, materials, and specialized suppliers, is concentrated in Asia, adding further costs to U.S. operations.

The commercial case for expanding in America therefore depends on more than manufacturing economics. Customer commitments, government incentives, supply security and the political risks associated with remaining heavily concentrated in Asia could all become part of the calculation.

SK Hynix already has a U.S. footprint under construction. The company completed a secondary Nasdaq listing in July and is building a chip-packaging facility in Indiana, but it does not currently fabricate memory chips in the United States.

SK Group Chairman Chey Tae-won said in July that the company was facing “enormous pressure” and lobbying from both customers and governments to increase chip supplies.

“I think we need to build a factory in the United States. If possible, I believe we should build it,” he told reporters.

The comments suggest the question is now about when and how SK Hynix expands U.S. manufacturing rather than whether the company should establish a larger American presence.

An Opening for Intel as AI Reshapes Chip Manufacturing

For Intel, a partnership with SK Hynix could help address one of the biggest challenges surrounding its Ohio project: the sheer scale and cost of the investment.

Intel announced in 2022 that it planned to invest as much as $100 billion to develop what it described as potentially the world’s largest chipmaking complex in Ohio. Production was initially expected to begin in 2025, but construction schedules have since been pushed back, with the site’s two planned plants now expected to be completed in 2030 and 2031.

Bringing in an established memory producer could give Intel a potential tenant, partner, or source of capital for infrastructure that otherwise requires years of investment before generating meaningful returns. It could also diversify the economic purpose of the Ohio site beyond Intel’s own manufacturing ambitions.

The potential timing is significant because AI has transformed memory from a relatively standardized component of computing into a major constraint on the expansion of data-center capacity. HBM has become more relevant because advanced AI accelerators require large amounts of high-speed memory, while only a small number of companies have the technology and manufacturing scale to supply it.

That dynamic is giving memory makers unusual bargaining power, but it is also increasing pressure from customers to expand capacity. A joint venture involving cloud companies would make economic sense in that context: hyperscalers could provide long-term demand commitments or capital in exchange for greater certainty over future memory supplies.

The proposal would also fit a broader shift in semiconductor manufacturing economics. Companies are now being asked to build where customers and governments want capacity, even when those locations are not the lowest-cost manufacturing bases.

Washington is intensifying that pressure. U.S. Commerce Secretary Howard Lutnick has threatened tariffs of as much as 100% on South Korean and Taiwanese companies unless they commit to greater production in the United States.

At the same time, Washington and Seoul are still negotiating the implementation of a major investment commitment South Korea made in the United States last year in exchange for lower U.S. tariffs. Of the proposed $350 billion commitment, about $150 billion has been earmarked for shipbuilding, while the remaining $200 billion has yet to be allocated.

Two of the sources said the unresolved investment discussions have complicated SK Hynix’s position. Seoul wants to use potential U.S. investment by its companies as leverage in broader negotiations with Washington, while the Trump administration is pressing SK Hynix to make a rapid commitment to expand its American manufacturing base.

The result is a semiconductor investment decision caught between three competing forces: the economics of manufacturing, the strategic demands of governments and the increasingly urgent needs of AI customers.

If SK Hynix ultimately manufactures memory in Ohio, the significance would extend beyond the individual deal. Analysts believe it would mark a step toward moving a portion of the world’s most important memory supply chain closer to U.S. data centers and technology companies. But the cost of that localization, and the question of which technologies Seoul is willing to see produced abroad, will determine how far that shift can realistically go.

Solana Expands Its Transaction Capacity as BitMine Nears 5% Supply Target

0

Solana is entering another phase of network expansion as its mainnet transaction-size limit rises from 1,232 bytes to 4,096 bytes, more than tripling the amount of data that can be carried in a single transaction.

At the same time, BitMine’s continued accumulation of Solana has pushed its holdings to approximately 4.9% of the cryptocurrency’s total supply, leaving roughly $359 million in purchases between the company and its stated 5% target.

The developments highlight two different but increasingly connected dimensions of Solana’s evolution: improving the blockchain’s technical capacity and deepening institutional exposure to its native asset.

The larger transaction ceiling is significant because blockchain applications increasingly require more information to be processed within individual transactions. Solana’s previous 1,232-byte limit could constrain transactions involving complex cryptographic operations, particularly as decentralized applications become more sophisticated.

Raising the limit to 4,096 bytes creates additional room for larger zero-knowledge proofs, multisignature transactions and other data-intensive instructions. Zero-knowledge technology is particularly relevant. ZK proofs allow one party to demonstrate that a statement is valid without revealing all of the underlying information.

As these systems become more prevalent across privacy applications, scaling solutions and decentralized finance, larger proofs can create additional transaction-data requirements. Solana’s expanded capacity therefore gives developers greater flexibility to construct applications around increasingly sophisticated cryptographic infrastructure.

The upgrade does not mean that every Solana transaction will suddenly become larger. Rather, it increases the upper boundary available to developers and applications that need it. That distinction matters because blockchain performance depends on more than transaction size. Validator resources, bandwidth, execution efficiency and network propagation remain important considerations.

A larger maximum can provide greater functionality, but it also requires careful engineering to ensure that the network retains its performance characteristics.

Meanwhile, BitMine’s accumulation introduces a different signal about Solana’s investment narrative. With its holdings approaching 5% of total supply, the company is positioning itself as a major institutional holder of SOL.

The remaining $359 million required to reach the target is relatively small compared with the scale of its existing position, making the 5% milestone increasingly visible to the market. Such accumulation can influence perceptions of supply dynamics.

When a large holder steadily removes tokens from liquid circulation, market participants may begin to reassess the available supply, particularly if the purchases are viewed as part of a long-term strategy rather than short-term trading.

However, concentration also creates a potential risk: a significant holder can become an important source of market liquidity or volatility if its strategy changes. The two developments reinforce Solana’s broader transition from a high-performance blockchain into an infrastructure platform supporting increasingly complex financial and cryptographic applications.

Larger transactions expand what can be built, while BitMine’s accumulation demonstrates growing conviction around SOL as an institutional asset. The more important question is whether technical expansion and institutional demand can develop together sustainably.

Solana’s challenge will be to preserve reliability and decentralization as transaction requirements grow, while investors will need to distinguish genuine network adoption from capital concentration.

If both trends continue, Solana could find itself at an important intersection between blockchain infrastructure and institutional digital-asset strategy—where improvements in network capability increasingly shape the investment case for SOL itself.

5% Treasury Yield Raises New Risks for U.S. Stocks, Corporate Debt and Bitcoin

0

The U.S. bond market has once again become the center of attention for investors, with the 10-year Treasury yield climbing above 5% on Monday for the first time in three years.

The move represents more than another milestone in the fixed-income market. It signals a broader repricing of risk that could increasingly shape the direction of stocks, corporate borrowing and digital assets.

The latest bond selloff also highlights the difficulty facing the Trump administration as it attempts to stabilize financial markets.

Efforts to calm investors have so far failed to prevent yields from pushing higher, suggesting that market forces are becoming more powerful than political reassurance.

Investors appear increasingly focused on inflation, government borrowing requirements, economic resilience and the supply of Treasury debt rather than simply waiting for policy signals from Washington.

For equity investors, the 5% threshold carries particular significance. Antony Ghee of Merrill and Bank of America identified a sustained break above that level as the biggest near-term threat to stocks.

The concern is straightforward: when government bonds offer increasingly attractive yields, investors have less incentive to accept the additional risk associated with equities. Higher Treasury yields also affect companies directly.

Rising benchmark rates increase financing costs for businesses that rely on debt to fund expansion, acquisitions, capital expenditure or refinancing. Companies with weaker balance sheets can face an even greater burden.

At the same time, higher discount rates reduce the present value investors assign to future corporate earnings, creating particular pressure for growth stocks whose valuations depend heavily on profits expected years into the future.

The consequences extend beyond Wall Street. Government borrowing becomes more expensive when Treasury yields rise, potentially increasing the cost of servicing the U.S. national debt. That can create a difficult feedback loop: larger interest expenses require greater government financing.

While increased Treasury issuance can place additional pressure on bond prices and yields if demand fails to keep pace. The shift is also relevant to Bitcoin. The cryptocurrency was trading near $77,800 and showed relatively little reaction to the Treasury move ahead of Wednesday’s Federal Reserve decision.

That resilience is notable because Bitcoin has increasingly traded alongside broader macroeconomic liquidity conditions. Yet its muted response suggests that investors may currently be waiting for clearer signals before repositioning aggressively.

Bitcoin’s behavior also illustrates the changing character of digital assets. Rather than responding mechanically to every move in traditional markets, the cryptocurrency increasingly reflects a combination of liquidity expectations, institutional positioning, ETF flows, dollar conditions and investor appetite for risk.

The Federal Reserve’s upcoming decision therefore arrives at a delicate moment. Markets are confronting a bond market that is demanding higher compensation for holding long-duration government debt, while equities remain vulnerable to tighter financial conditions.

A sustained 5% Treasury yield could become a new reference point for asset allocation across stocks, bonds, real estate and crypto. The Treasury market is sending a message that investors cannot easily ignore. The era of treating government bonds as a low-yield alternative to risk assets has changed.

If the 10-year yield remains above 5%, capital markets may have to adjust to a world where safe assets once again compete aggressively for investment dollars.