DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 3

U.S. Inflation Reaccelerates in August as Gasoline Drives Consumer Prices Higher

0

U.S. consumer prices accelerated in August, adding another layer of uncertainty to the country’s inflation outlook as households confronted sharply higher gasoline costs.

The Consumer Price Index (CPI) rose 0.4% in August, following a 0.1% increase in July, while prices were 3.4% higher than a year earlier, according to the U.S. Bureau of Labor Statistics.

The headline figure is notable not simply because inflation remains above the Federal Reserve’s 2% target, but because gasoline accounted for more than one-third of the monthly increase.

Gasoline prices rose 3.9% during August, reversing two consecutive monthly declines. Over the past year, gasoline prices have increased 27.4%, while the broader energy index has risen 16.3%.  Energy prices can have an influence far beyond the petrol station.

Higher gasoline costs immediately affect household transportation budgets, but they can also raise expenses for businesses that depend on road transportation, logistics and delivery services. When those costs persist, companies may attempt to pass part of the increase to consumers through higher prices.

Yet August’s inflation report was not entirely an energy story. Core CPI, which excludes food and energy, increased 0.3% during the month, compared with 0.2% in July. On an annual basis, core inflation eased to 2.4%, down from 2.5% in July. Shelter prices rose 0.3% in August, while food prices increased 0.1%.

That distinction matters for monetary policy. Energy prices can be volatile, meaning a gasoline-driven monthly increase does not necessarily indicate that inflationary pressure is spreading throughout the economy.

At the same time, the rise in core prices suggests that policymakers cannot simply dismiss the August increase as an isolated movement in fuel markets. The Federal Reserve therefore faces a complicated inflation environment.

Reuters reported that the August data strengthened market expectations for a further interest-rate increase, as investors assessed whether persistent price pressures could prevent inflation from returning smoothly toward the central bank’s target.

For consumers, the distinction between headline and core inflation is less abstract. A household filling its vehicle with gasoline, paying rent and buying food experiences the combined cost of those categories regardless of whether economists classify some prices as volatile.

The cumulative effect can place pressure on disposable income, particularly for households with limited room in their budgets. The August numbers also underline how quickly energy markets can reshape the inflation narrative.

Earlier declines in gasoline had provided some relief to the headline CPI. August reversed that benefit, demonstrating how movements in fuel markets can quickly change the monthly inflation picture.

The broader question is whether higher energy costs remain temporary or begin feeding into other parts of the economy. If transportation, production and operating expenses continue rising, businesses could face greater pressure to increase prices.

If those increases become persistent, the challenge for monetary policymakers becomes more difficult. For now, August presents a mixed picture: headline inflation remains at 3.4% annually, core inflation is considerably lower at 2.4%, but gasoline and energy prices are moving sharply higher.

The next several months will determine whether August represents a temporary energy-driven acceleration or another sign that the final stretch toward stable inflation will be more difficult than expected.

Oil, Trump and the New Treasury Yield Equation

The outlook for U.S. Treasury yields is becoming increasingly difficult to frame around the Federal Reserve alone.

iCapital has raised its forecast for the 10-year Treasury yield to a range of 4.5% to 5.3%, with global strategist Dan Suzuki arguing that energy prices and President Donald Trump could have a greater influence on where long-term borrowing costs ultimately settle than the Federal Reserve’s projections.

Suzuki’s argument reflects a broader shift in how investors are interpreting the bond market.

While monetary policy remains important, the 10-year Treasury yield is ultimately shaped by a much wider combination of inflation expectations, economic growth, fiscal conditions, investor demand and global risk. The Federal Reserve can influence short-term rates.

But longer-dated yields can move independently when markets begin to price changes in inflation or the economy. “I don’t think you even care about the dot plots,” Suzuki told CNBC’s Fast Money, highlighting the growing importance of forces outside the central bank’s immediate control.

The comment comes as financial markets confront a more complicated backdrop involving geopolitical tensions, oil prices and uncertainty surrounding U.S. economic policy. Oil is particularly important because energy costs can feed directly into inflation.

A sustained rise in crude prices can increase transportation, manufacturing and consumer costs, potentially making it harder for inflation to return to the Federal Reserve’s target.

Higher inflation expectations can, in turn, place upward pressure on Treasury yields as investors demand greater compensation for holding longer-term government debt.

Trump’s economic policies could influence the trajectory. Changes involving tariffs, fiscal spending, regulation and energy policy can alter inflation expectations, economic growth and the supply of government debt.

The interaction between those forces could become increasingly important for investors trying to determine whether long-term yields remain elevated. At the same time, signs of stress are appearing across risk assets. The Nasdaq and small-cap stocks are roughly 6% below their recent highs.

While high-yield credit spreads have begun to widen. Neither development necessarily signals an economic downturn on its own, but together they suggest that investors are becoming more cautious about the relationship between economic growth, financing conditions and asset valuations.

For equities, the direction of Treasury yields is only part of the story. The reason yields decline could be more important than the decline itself. If yields fall because geopolitical tensions ease while economic growth remains resilient, lower borrowing costs could provide meaningful support for stocks.

Businesses could benefit from improved financial conditions without facing a severe deterioration in demand. A recessionary decline in yields would present a very different scenario. Falling Treasury yields caused by weakening economic activity could coincide with declining corporate earnings, tighter credit and greater investor risk aversion.

In that environment, cheaper money would not necessarily translate into stronger equity markets. Suzuki therefore favors a more defensive and diversified approach, pointing toward financials and healthcare, private infrastructure as a potential inflation hedge, and cash.

The broader message is that investors may need to look beyond the Federal Reserve when assessing the next phase of the bond market. The Treasury market is increasingly being shaped by the interaction between energy, geopolitics, fiscal policy and economic resilience.
Uber Layoffs Highlight Growing Concerns over AI’s Expanding Role in Daily Workflows

0

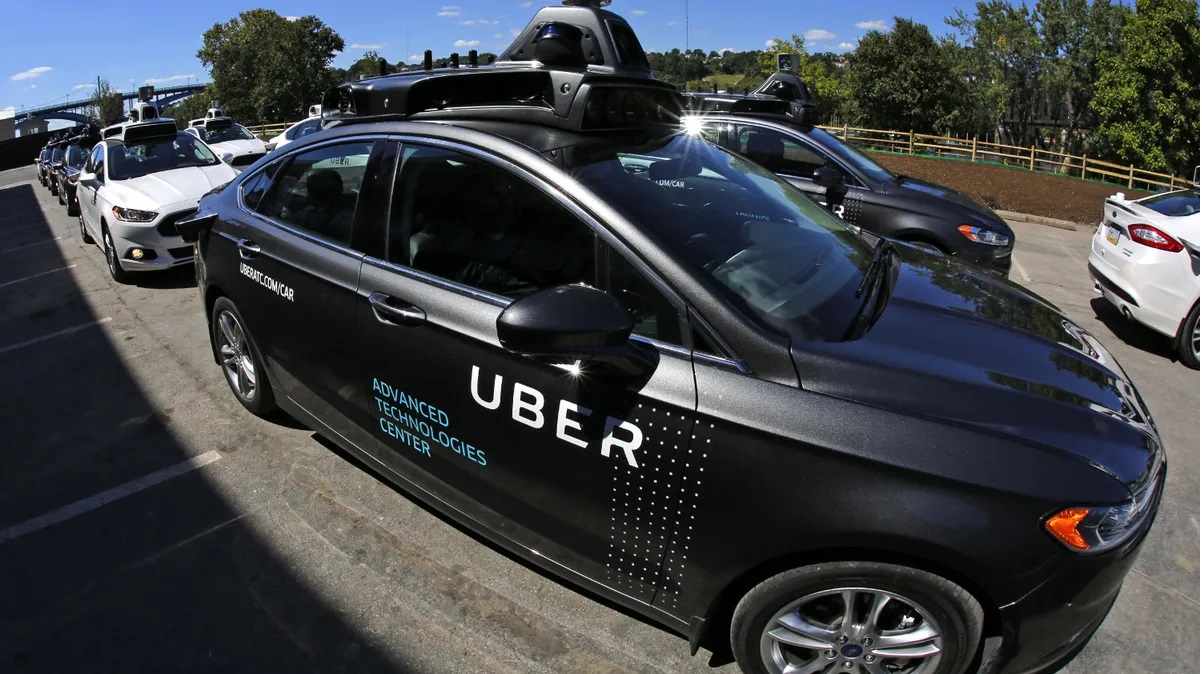
The layoffs at Uber are raising a broader question about the changing relationship between artificial intelligence and human work.

Some former employees say AI had already begun playing a larger role in their day-to-day responsibilities in the period leading up to the cuts, suggesting that the technology was not simply an experiment at the edges of the company but was becoming embedded in ordinary workplace processes.

That distinction matters. Companies have used software to automate repetitive tasks for decades, but generative AI can reach further into work traditionally associated with knowledge, judgment and communication.

At a company as large and operationally complex as Uber, AI can potentially assist with writing, data analysis, customer support, coding, internal research, planning and other functions that once required substantial employee time.

For workers, greater AI adoption can create an uncomfortable contradiction. The same tools that make an employee more productive can also reduce the amount of labor a company believes it needs. If one employee equipped with increasingly capable software can complete work that previously required several people.

Productivity gains may eventually become a workforce-reduction strategy. That does not necessarily mean AI caused Uber’s layoffs. Corporate restructuring rarely has a single explanation. Companies cut jobs for many reasons, including changes in demand, cost pressures, organizational redesign, strategic priorities and expectations about future growth.

AI can be one factor within that broader calculation without being the direct reason a particular employee loses a job.

Yet the experiences described by some laid-off workers are significant because they illustrate how automation can happen gradually.

Employees may initially encounter AI as an assistant: a tool that summarizes documents, generates drafts, analyzes information or speeds up routine processes. Over time, those capabilities can become part of standard workflows. What begins as optional technology can become an expectation of productivity.

For Uber, whose business already depends heavily on software, algorithms and data, this evolution is particularly notable. The company’s core operations rely on technology to match riders and drivers, estimate prices, optimize routes and manage enormous quantities of information.

Bringing increasingly capable AI into corporate functions extends that technological model beyond the platform itself and into the organization that operates it. The bigger economic question is whether AI will primarily eliminate jobs, transform them or create new categories of employment.

History offers evidence for all three outcomes. Automation has displaced particular tasks while creating demand for new skills and industries. The difference with modern AI is its potential reach across white-collar work, where employees may have previously assumed that their expertise provided greater protection from automation.

This makes reskilling increasingly important, but it also places pressure on employers to explain how AI will be deployed. Workers need to know whether new systems are designed to augment their responsibilities or eventually replace them. Investors and executives, meanwhile, have to balance efficiency gains against the organizational knowledge and creativity that experienced employees provide.

The Uber layoffs therefore represent more than another corporate workforce reduction. They offer a snapshot of a workplace in transition, where artificial intelligence is moving from an emerging productivity tool into the infrastructure of everyday work. The critical issue is no longer whether AI will enter the office. It already has.

The question is how companies, workers and policymakers will manage the consequences when greater technological efficiency changes the number and nature of jobs required.

OpenAI Astra for Law vs Claude Projects: How AI Is Evolving Into Professional Workflows

0

The latest moves from OpenAI and Anthropic point to a deeper shift in artificial intelligence: the leading AI companies are no longer competing only to build smarter chatbots. They are building systems designed to organize professional work, understand specialized domains and execute increasingly complex tasks.

OpenAI has launched Astra for Law, a legal-focused configuration of GPT-6 Astra aimed at law firms and legal technology companies.

The system combines GPT-6 Astra with a dedicated legal search index, specialized instructions and tools designed for professional legal research, analysis and drafting.

Its legal index covers U.S. case law, statutes, regulations, court rules and administrative decisions, with new sources added daily. That architecture matters because legal work depends heavily on authoritative source material.

A general-purpose chatbot may generate a persuasive answer, but lawyers need to know where an argument comes from, which authority supports it and what evidence could undermine it.

Astra for Law is therefore designed to search relevant legal materials and help users examine opposing arguments, develop legal positions and analyze contractual issues.

OpenAI is also positioning Astra for Law as infrastructure rather than simply another chatbot feature. Legal technology companies such as Harvey and Legora can build products and workflows on top of the model.

While integrations with platforms including Relativity, Clio, iManage and Intapp can connect AI capabilities with established legal systems. The initial rollout is focused on selected U.S. law firms through a controlled access program.

Anthropic is changing the meaning of a project inside Claude Code. Its redesigned Projects experience turns a project from essentially a container for work into a coordinated environment in which Claude can divide a large objective among multiple threads.

The system can scope a task, delegate work, coordinate parallel sessions, review results and assemble the finished output.

The implications are significant for software development. Instead of asking an AI to modify one file at a time, a developer can give Claude a broader engineering objective.

Different threads can investigate separate components, test changes or work on different repository branches, while a central coordination layer keeps the overall project aligned. Anthropic says users can continue steering the process, even from a phone, while the system continues working after they leave their computer.

The announcements approach professional AI from different directions. OpenAI is specializing intelligence around a regulated knowledge domain: law. Anthropic is specializing workflow around coordinated execution: software projects. Yet both reveal the same competitive direction.

The next phase of AI may therefore be defined less by the question, “Which model gives the best answer?” and more by, “Which system can complete the most valuable professional workflow?”

That distinction changes the economics of AI. A model that drafts a paragraph is useful. A system that can research authorities, analyze documents, identify counterarguments and integrate its findings into an existing legal workflow can become infrastructure.

Likewise, an AI that writes code is useful; an AI that can coordinate multiple engineering tasks toward a shared objective begins to resemble a digital project team.

OpenAI’s Astra for Law and Anthropic’s redesigned projects suggest that the AI race is moving steadily from conversation toward execution. The decisive advantage may increasingly belong to systems that combine intelligence, specialized knowledge, tools, memory and coordination into a single working environment.

SK Hynix Considers US NAND Factory as Trump Pushes Korean Chipmakers to Reshore Production

0

SK Hynix subsidiary Solidigm is considering building a NAND flash memory factory in the United States, with upstate New York emerging as a leading candidate, as pressure from the Trump administration pushes South Korean chipmakers to expand semiconductor production on American soil.

Three people familiar with the matter told Reuters that Solidigm is evaluating the potential project, which would be separate from discussions between SK Hynix and Intel over producing memory chips at Intel’s Ohio facility.

No final investment decision has been made, and key details of the proposed plant remain under discussion, one of the sources cautioned.

SK Hynix confirmed that Solidigm is examining options but said there was no specific project yet.

“Subsidiary Solidigm is reviewing various options to strengthen its business competitiveness, but no specific plans have been confirmed at this time,” SK Hynix said.

A U.S. manufacturing base would give Solidigm an alternative to its sole NAND production facility in Dalian, China. It could also reduce the company’s exposure to potential U.S. tariffs and restrictions on the export of semiconductor manufacturing equipment to China.

The potential investment comes as Washington intensifies efforts to bring semiconductor production back to the United States, particularly as the rapid expansion of AI data centers tightens global supplies of memory chips.

For SK Hynix, however, building in America presents a difficult cost calculation. Semiconductor production is generally more expensive in the United States than in South Korea, while Seoul and Washington are still negotiating the terms of South Korea’s broader investment commitments and trade relationship with the United States.

Solidigm Could Offer a Lower-Risk US Expansion

Solidigm’s NAND business is expected to provide SK Hynix with a politically easier path into U.S. manufacturing than relocating its most advanced memory technologies.

One of the sources said producing NAND through the U.S. subsidiary could encounter less resistance from Seoul because NAND is viewed as less strategically sensitive than advanced DRAM products, particularly high-bandwidth memory, or HBM, which has become a critical component of AI accelerators.

That has become a matter of interest as Washington and Seoul compete for semiconductor investment.

The South Korean government has been encouraging SK Hynix and Samsung to accelerate plans for a semiconductor manufacturing cluster in the country’s southwest, potentially involving investments worth hundreds of billions of dollars. At the same time, the Trump administration has been pressing Korean and Taiwanese semiconductor companies to expand U.S. manufacturing.

U.S. Commerce Secretary Howard Lutnick has threatened tariffs of up to 100% on South Korean and Taiwanese companies unless they commit to increasing production in the United States.

The pressure puts SK Hynix in the middle of competing industrial policies. Washington wants more chip manufacturing on American soil, while Seoul wants to preserve South Korea’s position as a global semiconductor manufacturing hub.

South Korean President Lee Jae Myung said Seoul would seek to “protect South Korea’s national interests while respecting the views of companies” when asked about pressure on Korean chipmakers to establish factories in the United States.

“It remains a matter of controversy,” Lee said Friday, without elaborating.

The issue is particularly sensitive because South Korea has already committed to a $350 billion investment package in the United States as part of an agreement aimed at securing lower U.S. tariffs.

China Is Expanding Its Memory Ambitions

The potential Solidigm investment also comes as Chinese semiconductor companies are moving deeper into the memory market.

Chinese chipmaker CXMT plans to establish an R&D production line for NAND flash memory at a new facility in Beijing, according to a Reuters report, as it seeks to enter a market dominated by Samsung, SK Hynix and Micron.

China’s push adds another layer of pressure on SK Hynix.

A U.S. plant could help Solidigm diversify its manufacturing footprint while providing some protection against geopolitical restrictions. But building capacity in America would take years and require substantial capital, making it difficult to know what the market will look like when the factory begins production.

That uncertainty is relevant for NAND, a market that has experienced prolonged cycles of oversupply, falling prices and weak profitability.

SK Hynix acquired Solidigm from Intel for $9 billion in 2020 and has since dealt with years of losses at the business following the extended downturn in NAND. The company is now looking for ways to improve Solidigm’s competitiveness. Last month, SK Hynix said it was considering measures to strengthen the unit after reports that Solidigm was exploring a pre-IPO fundraising of about 5 trillion won, or roughly $3.6 billion.

SK Hynix said at the time that no decisions had been made.

A U.S. factory could therefore serve several purposes at once: diversifying Solidigm’s manufacturing base, reducing its exposure to China-related trade restrictions, and giving SK Hynix a stronger position in the U.S. market.

But the economics remain uncertain.

Memory has become increasingly important to the AI infrastructure boom. DRAM provides the working memory used by processors, while NAND is primarily used to store data. The rapid construction of AI data centers has sharply increased demand for memory and put pressure on global supply chains.

SK Hynix has benefited heavily from the surge in demand for HBM, which is used alongside AI processors. That business is different from Solidigm’s NAND operation, but the broader AI infrastructure boom has created a more favorable environment for memory manufacturers.

However, there is concern about demand remaining strong enough to justify new U.S. capacity several years from now. The debate has become more complicated after concerns emerged over the pace of frontier AI development. Any meaningful slowdown in AI infrastructure investment could eventually affect demand for the memory and storage components used in data centers.

SK Hynix’s shares nevertheless rose 6.4% on Friday, compared with a 2.7% gain in the benchmark KOSPI index, as investors responded to broader semiconductor developments.

Sam Altman-Backed World Expands Stablecoin Payments With World Money

0

The launch of World Money marks another step in the evolution of stablecoins from crypto-native instruments into consumer-facing financial infrastructure.

World, the digital-identity project developed by Tools for Humanity, a company co-founded by Sam Altman and Alex Blania, has begun rolling out the self-custodial financial application across more than 150 countries.

The product combines stablecoin payments, transfers, trading, yield opportunities and virtual accounts in a single interface.

At the center of World Money is self-custody. Rather than functioning like a conventional bank account in which an institution controls the underlying funds, users retain control of their digital assets.

That architecture is significant because World is attempting to make a crypto wallet feel less like a specialist blockchain product and more like a general-purpose financial account. The application supports balances across eight currencies and allows users to send supported digital assets internationally through World usernames.

World is also incorporating portfolio tracking, transaction histories and price alerts, bringing several functions normally distributed across exchanges, wallets and payment applications into one environment.

Stripe provides one of the most important bridges between traditional payments and the new system. In the United States, users can fund World Money through Apple Pay and convert those funds into stablecoins, with World saying the process typically takes minutes.

The arrangement demonstrates how stablecoin adoption increasingly depends not only on blockchain infrastructure but also on familiar fiat-payment rails.  The application also connects users to decentralized finance and prediction markets.

Morpho powers selected Earn programs, allowing eligible users to deposit assets such as WLD and USDC into on-chain lending strategies. Kalshi is available through World Money’s Mini Apps, while other integrated services extend the application’s financial functionality.

This creates a model in which the wallet becomes an interface for multiple financial protocols rather than simply a place to store tokens. World’s identity infrastructure is another defining component.

World Money is now separated from the World ID App, with the latter focused on identity verification and credentials while World Money handles financial activities. Existing World users can carry their World ID status into the financial application.

Verified users can also receive promotional boosts on eligible Earn programs. That connection between identity and money reflects World’s broader thesis: digital financial systems need a mechanism for distinguishing people from automated or fraudulent accounts.

World argues that proof of human can add a layer of trust to transactions as artificial intelligence makes the creation of fake digital identities increasingly inexpensive. The claim is central to World’s product strategy, although the effectiveness and broader implications of its identity model remain subjects of debate.

The 150-plus-country rollout is therefore broader than a conventional wallet launch. It represents an attempt to combine stablecoins, decentralized finance, payment infrastructure and digital identity into a single consumer platform. Yet availability is not uniform.

World explicitly states that features, assets and eligibility vary by jurisdiction, meaning users in different countries may encounter substantially different versions of the product.  There are also material risks. World Money is not a bank, and stablecoins held through the application are not government-insured deposits.

Earn products can expose users to smart-contract, protocol and market risks, while self-custody transfers responsibility for account access and asset security to users. World Money represents a bet that the future financial application will not be separated into a bank, exchange, wallet and DeFi interface.

Instead, those functions could converge around stablecoins and portable digital identity. Its success will depend on whether World can turn that ambitious architecture into something ordinary users find simple, reliable and useful across borders.

ZachXBT Exposes Dormant RaidParty NFT Scam Account as Coinbase Announces $150K Singapore Trading Contest

Meanwhile, the crypto industry is once again confronting two very different sides of its rapidly maturing culture: the persistent problem of accountability in digital assets and the growing effort to turn trading into a mainstream entertainment experience.

Highlighting how blockchain markets increasingly operate at the intersection of investigation, speculation, social media and financial entertainment.

On the investigative side, blockchain sleuth ZachXBT has raised questions over wallet activity connected to the old RaidParty project.

According to reports citing his on-chain analysis, an address associated with the X account @7zarc received approximately 4,870 ETH, worth around $15 million, from addresses linked to what has been described as a roughly $70 million RaidParty exit scam.

The funds were subsequently transferred toward deposit addresses at several centralized exchanges. The detail that has attracted particular attention is the account’s apparent dormancy. ZachXBT said the account disappeared from public activity in 2022 and resurfaced in September 2026, roughly four years later.

That timing, combined with the movement of funds, prompted him to publicly question the wallet’s connection to the RaidParty-related flows. As of the reports reviewed, @7zarc had not publicly responded to the allegations.

The episode illustrates one of blockchain’s defining characteristics: transactions remain visible long after communities, projects and online identities have disappeared. A dormant account can return years later, but the historical ledger does not disappear with it.

Investigators can therefore reconstruct relationships between wallets, treasury movements and exchange deposits long after an NFT project has faded from public attention. At the same time, Coinbase is pushing crypto toward a very different kind of spectacle.

The exchange has announced an in-person, esports-style trading competition in Singapore scheduled for October 8, with the event to be streamed live on X. Coinbase says the competition will feature 10 traders and $150,000 in prize money, bringing prominent crypto personalities into a format designed to resemble competitive gaming.

Among the personalities involved are traders and crypto commentators familiar to Crypto Twitter, including Ansem and other prominent participants.

Coinbase has also been announcing individual participants, including IzeBel and Taiki Maeda, reinforcing the event’s emphasis on recognizable online trading personalities rather than conventional financial television figures.

The Singapore setting is also significant. Coinbase has described Singapore as one of its important international markets and has been expanding its regional presence, including a permanent Singapore office and plans to grow its local team.

The two stories capture crypto’s continuing contradiction. One side remains focused on tracing old money trails and determining who may be responsible when digital projects collapse. The other is transforming market activity into live entertainment for a global online audience.

That contrast may increasingly define the next phase of crypto. Transparency, wallet surveillance and forensic investigation are becoming more sophisticated, while exchanges are simultaneously building social and entertainment layers around trading.

The blockchain records both dimensions: the transactions that investigators follow years later and the markets that traders now perform before millions of viewers.