Home Blog Page 37

Israel’s Election: What Is at Stake for Palestinians, Israel and the Region

0

Israel’s October 27, 2026 election comes at a moment when the country’s domestic politics and regional conflicts are unusually intertwined. The vote will determine more than who occupies the prime minister’s office.

It will influence Israel’s approach to Gaza and the West Bank, its relationships with Washington and European capitals, and its strategy toward Iran, Lebanon, Syria and Turkey. For Palestinians, the stakes are particularly significant.

The present government has accelerated settlement activity and annexation-related measures in the West Bank while maintaining a military campaign and security presence around Gaza.

A research assessment of the election argues that major Israeli political forces differ over the pace and institutional form of these policies, but that support for maintaining extensive security control remains widespread among leading Zionist parties.

A change of government could therefore alter the language and diplomatic framework surrounding the Palestinian issue without necessarily producing an immediate transformation on the ground.

Opposition figures including Naftali Bennett and Yair Lapid have criticised Netanyahu’s handling of Gaza, but both have maintained hard-line security positions toward Hamas. Analysts note that many opposition parties remain reluctant to make a clear commitment to a two-state settlement.

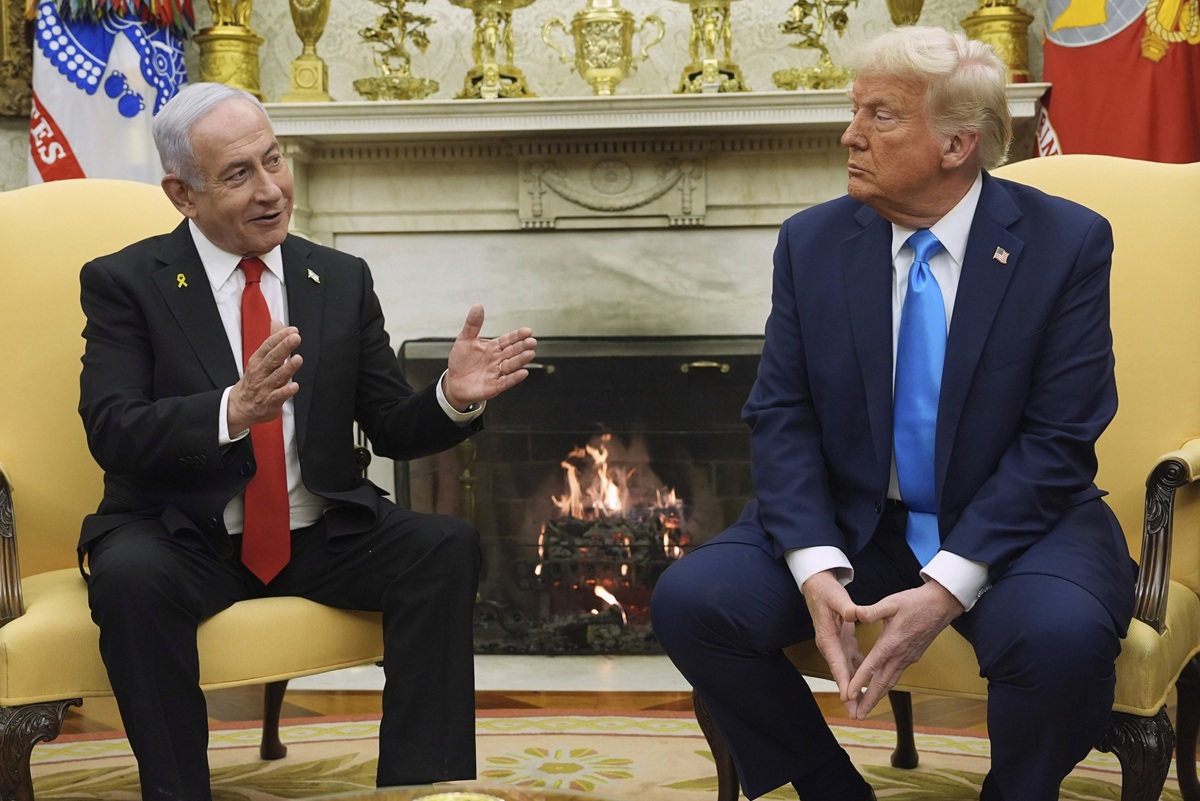
International relations are another major test. Israel’s relationship with the United States remains strategically central, but disagreements between Netanyahu and President Donald Trump over Iran and Lebanon have demonstrated that the alliance does not eliminate differences over military strategy and diplomacy.

A new Israeli government could seek a different style of engagement with Washington, potentially placing greater emphasis on coordination and diplomatic repair. Relations with Europe could also become a political priority.

Israel’s conduct of the Gaza war, settlement expansion and disputes with international institutions have contributed to growing diplomatic friction with European governments and Western publics. A government seeking to rebuild those relationships would face the difficult task of balancing international pressure against domestic security expectations.

The regional picture is equally complicated. On Lebanon, Bennett and Lapid have supported strong military measures against Hezbollah and criticised ceasefire arrangements they consider inadequate.

Their approach therefore suggests that replacing Netanyahu would not automatically mean abandoning Israel’s military posture toward Hezbollah. Syria presents another security challenge, while Turkey has become increasingly critical of Israel’s Gaza campaign.

President Recep Tayyip Erdo?an has continued calling for greater international recognition of Palestinian statehood and pressure on Israel, making relations between Ankara and Jerusalem an important diplomatic issue for any future Israeli government.

Iran may be the hardest question of all. Netanyahu and his principal opponents have broadly supported confronting Tehran, opposition leaders have argued that military power needs to be combined with diplomacy and strategic planning.

The distinction may therefore be less about whether Iran represents a security threat and more about how Israel manages escalation, deterrence and negotiations.  Finally, Israel’s international standing is at stake.

Rebuilding public support abroad would require more than diplomatic messaging. It would involve decisions over Gaza, Palestinian governance, civilian protection, settlements, regional diplomacy and relations with international institutions.

The election can change the government’s direction, but restoring confidence internationally would depend on what the next government actually does after taking office.

Human Judgment in the Age of Autonomous AI Systems, as AI Firms Scale Valuations

0

The future of technology is increasingly being shaped by a deceptively simple question: who gets to decide what machines should do, what they should create, and what kind of digital world humans should inhabit?

In a wide-ranging reflection on decision-making, beauty, operating systems and artificial intelligence, one theme emerges clearly: technological progress is not simply about making machines more capable. It is about determining what those capabilities are used to produce.

Decision-making has traditionally been treated as a distinctly human strength. Computers could calculate, search and execute instructions, but people supplied judgment. Artificial intelligence is changing that division.

AI systems can evaluate enormous quantities of information, identify patterns and recommend actions within seconds. Yet speed and statistical sophistication do not eliminate the need for human judgment. They make the question of responsibility more complicated.

Beauty provides an interesting lens through which to understand this shift. Human appreciation of beauty is rarely based on efficiency alone. It involves context, emotion, culture, imperfection and personal experience.

AI can generate technically impressive images, music, writing and design, but the existence of an attractive output does not necessarily explain why it matters. The growing presence of machine-generated content therefore raises a broader question.

Should technology merely reproduce what humans already recognize as beautiful, or can it contribute to entirely new forms of aesthetic expression? That question becomes even more important when considering the future of the operating system.

For decades, operating systems have primarily provided an interface between humans and computing hardware. Users open applications, issue commands and move information between different programs.

AI could fundamentally alter this model. Instead of navigating dozens of applications, people may increasingly communicate with an intelligent system that understands goals and coordinates software on their behalf.

The operating system of the future could therefore become less visible. Rather than being a collection of menus, windows and icons, it may function as an intelligent layer connecting users, applications, data and autonomous agents.

The computer would not simply wait for instructions; it could anticipate tasks, organize information and execute multi-step workflows. But this evolution also creates a new cultural problem: AI slop.

As generative AI makes content production dramatically cheaper, the internet can become saturated with low-effort articles, synthetic images, recycled videos and automated commentary designed primarily to capture attention.

The problem is not that AI-generated content is inherently worthless. The problem is that abundance can overwhelm scarcity. When almost anyone can generate thousands of pieces of content, discovering something thoughtful, original or genuinely useful becomes harder.

This leads directly to the argument over who is responsible. Blaming AI alone misses the human incentives behind its deployment. Companies build systems, platforms distribute their outputs, creators decide how to use them, and audiences determine what receives attention.

Responsibility is therefore distributed across the entire ecosystem. The central challenge is not stopping technological progress. It is developing better standards for judgment, authorship and accountability as machines become more capable.

The future operating system may be intelligent, creative and deeply autonomous, but humans will still determine what deserves to be built, trusted and remembered.

Technology can automate decisions, manufacture beauty and generate infinite content. It cannot automatically determine which of those things should matter. That remains a human responsibility.

Why AI Companies Are Moving From Pre-Seed to Series A at Record Speed

The traditional startup funding journey is becoming increasingly compressed, particularly for companies operating in artificial intelligence.

A new generation of AI startups is reaching revenue milestones, attracting investors and progressing through funding rounds at a speed that would have been unusual only a few years ago. The pattern suggests that venture capital is increasingly rewarding evidence of rapid commercial adoption rather than simply betting on long-term potential.

Fluencify, for example, raised its pre-seed round after reaching $2 million in annual recurring revenue just six months after launching. Mika reached more than €1 million in ARR before securing its seed financing.

At the Series A stage, Spott reported 10-fold revenue growth during the year, while Biolevate cited 20-fold ARR growth. These figures illustrate what investors increasingly want to see: not merely an impressive technology story, but measurable evidence that customers are willing to pay for it.

Revenue growth can dramatically change the dynamics between startups and venture investors. In the earliest stages, founders often raise capital largely on the strength of their team, technology and market opportunity.

As revenue arrives quickly, the company can present investors with a clearer commercial proposition. Strong ARR growth reduces some uncertainty around product-market fit and gives investors a tangible metric with which to assess momentum.

AI startups are also moving through funding stages at remarkable speed. Cato moved from pre-seed to seed in only five months, while AI Score made the transition in 10 months. Wonderful raised its Series C just six months after its Series B, at 2.5 times the previous valuation.

Such timelines demonstrate how rapidly investor attention can shift when a company combines technological relevance with accelerating commercial performance. The speed of these rounds also reflects the competitive nature of AI investing.

Venture firms risk missing opportunities if they wait too long to see how a promising startup develops. Once an emerging company demonstrates significant revenue growth, competing investors may seek entry before the next valuation increase.

Founders have greater leverage when fundraising momentum is supported by strong operating metrics. The identity of early investors is equally revealing.

High-Tech Gründerfonds led both a pre-seed round for Depotcharge and a seed round for Arcos. Y Combinator participated in four rounds, while Vendep Capital and Keen Venture Partners each backed two seed-stage companies.

Repeated participation by established investors shows how specialized venture networks can become important sources of capital as AI startups move rapidly from experimentation toward scale. Yet rapid fundraising is not automatically evidence of a durable business.

Fast-growing ARR can coexist with high customer-acquisition costs, intense competition and uncertain margins. AI companies may also face rapidly changing technology, infrastructure expenses and pressure to demonstrate that growth is sustainable rather than temporarily driven by market excitement.

Still, the broader signal is clear. AI has created an environment where exceptional startups can move from launch to meaningful revenue and successive funding rounds in a fraction of the traditional timeframe.

The message is to demonstrate commercial traction early. For investors, the challenge is distinguishing genuine, repeatable growth from momentum that merely looks spectacular on a funding announcement.

The new venture-capital cycle is therefore increasingly measured not simply in years between rounds, but in months between milestones. In AI, speed itself has become part of the competitive landscape.


The Innovation Lessons Hidden Inside a 174-Year-Old Glassmaker

0

The story of a 174-year-old glassmaker in upstate New York offers a useful lesson for companies navigating an economy increasingly shaped by artificial intelligence, automation and advanced manufacturing.

Its most important lesson is not that old companies can survive. It is that longevity and innovation can reinforce each other when institutions treat experience as an asset rather than an obstacle.

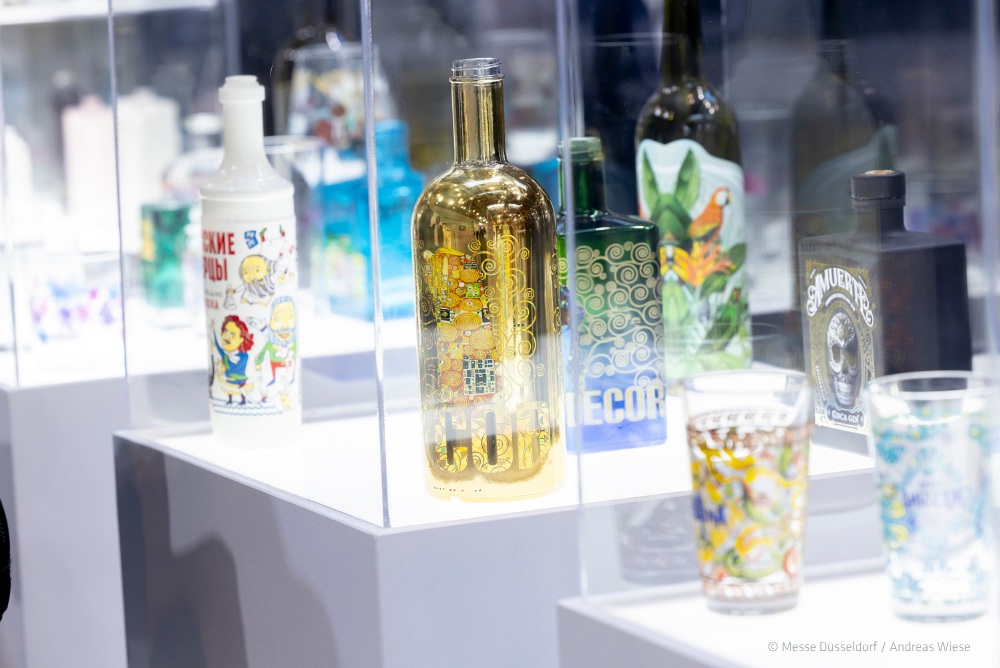
A business that has existed for 174 years has already witnessed enormous technological disruption. Glassmaking itself has evolved from labor-intensive craft production into a sophisticated industrial process involving precision engineering, specialized materials, automation and increasingly complex quality controls.

Surviving those transitions requires more than preserving tradition. It requires repeatedly deciding what tradition is worth keeping and what must change. That distinction matters for modern companies.

Innovation is often presented as a race to discover something completely new. In practice, many successful innovations emerge from improving an existing process, product or capability.

An established manufacturer may understand its materials, customers and production problems better than a young technology company. The challenge is converting that accumulated knowledge into new solutions.

The glassmaker’s experience illustrates another principle: innovation frequently happens at the intersection of disciplines. Modern glass production can involve chemistry, physics, engineering, software, robotics, energy management and materials science.

A company does not necessarily need to become a technology company to benefit from technology. It can use technology to transform what it already understands. This is particularly relevant as artificial intelligence enters industrial operations.

AI can help manufacturers identify defects, optimize production schedules, analyze equipment performance and improve forecasting. But algorithms are only as useful as the operational knowledge surrounding them.

A company with decades of experience may possess valuable institutional knowledge that cannot simply be purchased from a software vendor. The lesson is therefore not to choose between human expertise and technology. It is to combine them.

Another lesson is patience. Innovation is frequently associated with rapid experimentation, but industrial innovation often requires long development cycles. Materials must be tested. Production systems must be redesigned. Customers must validate new products. Safety and reliability cannot be rushed.

Long-lived companies understand that not every experiment will succeed. Their advantage can come from building systems that allow experimentation without threatening the entire business. That means investing in research while maintaining operational discipline.

There is a lesson about adaptability. A company founded in the nineteenth century could not have survived by serving the same markets with the same methods indefinitely. Its survival suggests an ability to respond to changing customer requirements, technology and economic conditions.

For today’s firms, adaptability may be one of the most important forms of competitive advantage. The broader message is that innovation does not have an expiration date. Nor does age automatically make an organization resistant to change.

A 174-year-old glassmaker can be a reminder that innovation is less about constantly abandoning the past and more about using accumulated knowledge to build the future.

For businesses confronting AI, automation and rapidly changing markets, the question should therefore not simply be, “What new technology should we adopt?” It should be, “What do we already know, and how can technology make that knowledge more valuable?”

That is perhaps the enduring lesson of an old glassmaker: innovation becomes powerful when experience and experimentation work together.

Crypto ETFs Attract $3.04B Weekly as Bitcoin Inflows Hit $2.4B; Ethena Expands USDe Into Equities

0

The crypto market is entering a period in which institutional capital and increasingly sophisticated on-chain financial products are moving in parallel. Spot crypto exchange-traded funds recorded about $3.04 billion in weekly inflows.

While Bitcoin ETFs alone attracted approximately $2.4 billion, marking their strongest weekly inflow since October 2025. Ethena is expanding the strategy behind its USDe synthetic dollar into tokenized equities and equity perpetuals on Binance.

Signaling a broader convergence between crypto infrastructure and traditional financial markets. The ETF figures are significant because they show that demand for digital assets is not confined to speculative activity on centralized or decentralized exchanges.

Spot ETFs provide regulated market access through conventional investment structures, allowing institutional investors, wealth managers and other market participants to gain exposure without directly managing wallets or private keys.

A $2.4 billion weekly inflow into Bitcoin ETFs therefore represents a substantial movement of capital through an increasingly established investment channel. The strength of the Bitcoin flows also changes the market conversation.

Rather than simply measuring short-term price momentum, ETF flows provide a window into investor positioning. Persistent inflows can increase the amount of capital competing for available Bitcoin exposure, while withdrawals can have the opposite effect.

The latest weekly figure, being the strongest since October 2025, suggests that institutional demand has regained considerable momentum. Yet Bitcoin is no longer the only asset benefiting from the expansion of regulated crypto investment products.

The broader $3.04 billion inflow indicates that investors are allocating across multiple parts of the digital-asset ecosystem. Ethereum and other crypto ETFs are increasingly becoming part of the same institutional allocation framework, potentially widening the market beyond Bitcoin’s traditional dominance.

Parallel to this institutionalization, Ethena is pushing USDe into a more complex financial environment. USDe was designed as a synthetic dollar, using a combination of crypto assets and derivatives-based strategies rather than relying solely on conventional cash reserves.

Its expansion into bStocks and equity perpetuals on Binance extends that architecture toward tokenized equity exposure and leveraged derivatives.

The development is important because it illustrates how stable-value crypto instruments are increasingly being connected to financial products traditionally associated with banks, brokerages and derivatives markets.

Tokenized equities can bring representations of traditional stocks onto blockchain infrastructure, while perpetual contracts allow traders to maintain leveraged exposure without holding the underlying asset in the conventional manner.

For Ethena, the opportunity is potentially larger than simply adding another trading product. Expanding USDe’s backing strategy into equity-related markets could diversify the sources of yield and market exposure supporting its ecosystem.

However, greater complexity also introduces additional risks, including derivatives losses, funding-rate changes, liquidity constraints, counterparty exposure and the possibility of sharp market dislocations.

The ETF inflows and Ethena’s expansion point toward the same structural trend from different directions. Traditional capital is moving deeper into crypto through regulated investment vehicles, while crypto-native protocols are moving outward into equities and sophisticated derivatives.

The boundary between digital assets and traditional finance is therefore becoming increasingly difficult to define. ETFs are bringing institutional money into crypto, while products such as USDe are attempting to bring traditional market exposure into blockchain-based financial infrastructure.

The next phase of the market may be shaped less by the separation of these systems and more by how successfully they become connected.

Fake GIWA Bridge Scams Users Out of $2M as Circle and Tether Freeze Bitget Hack Funds

0

The latest wave of crypto security incidents highlights two different vulnerabilities in the digital-asset economy: the ability to manufacture convincing blockchain infrastructure and the difficulty of recovering assets once a major exchange breach has occurred.

A fake GIWA bridge reportedly drained about $2 million in Ether, while Circle and Tether moved to freeze a small portion of assets connected to the much larger Bitget hack. The GIWA incident is particularly revealing because the attackers did not simply create a fraudulent website.

They constructed a counterfeit Layer-2 environment that appeared to represent GIWA, an Ethereum-based network developed by Dunamu, the operator of South Korean crypto exchange Upbit. GIWA’s actual mainnet had not launched, yet the fraudulent network presented users with infrastructure that looked sufficiently legitimate to attract deposits.

According to DYORSWAP’s reconstruction, approximately 1,335 addresses deposited around 767.65 ETH into the fake bridge. About 766.25 ETH was subsequently drained, representing roughly $2 million at the time.

The attackers reportedly used GIWA-associated chain information, including Chain ID 9134, alongside an RPC endpoint and bridge infrastructure. The combination created a convincing imitation of a blockchain that users expected to become operational.

The episode demonstrates why blockchain verification cannot depend on a single identifier. A chain ID can help wallets distinguish networks, but it does not establish who controls the network, bridge contracts or RPC infrastructure.

DYORSWAP said its own contracts were not compromised and has begun compensating affected users, reportedly distributing more than 200 ETH from its own funds while continuing to investigate the attackers. The Bitget incident presents a different security problem.

The exchange initially reported that approximately $351.6 million in assets had been affected by unauthorized transfers from some hot wallets. Bitget later revised the estimated amount to approximately $387.5 million after accounting for additional assets on Zcash and TRON.

The company said its cold wallets and separate self-custodial Bitget Wallet were not affected. In response, stablecoin issuers Circle and Tether froze a wallet associated with the attack. The address contained approximately 218,023 USDT and 99,990 USDC.

Meaning only about $318,000 in stablecoins was immobilized. That amount is small compared with the overall losses, but the intervention illustrates an important characteristic of centralized stablecoins: issuers can sometimes blacklist specific addresses and prevent their tokens from being transferred.

The limitations are equally important. Freezing USDC and USDT does not freeze Ether, XRP or other native blockchain assets. Reports indicated that substantial amounts of stolen XRP were moved after the breach, demonstrating how quickly assets can travel beyond the reach of issuer-level controls.

The incidents underline a broader lesson for crypto markets. Security is no longer simply about auditing smart contracts. Users must also verify bridge addresses, RPC endpoints, chain identifiers, deployment status and official announcements.

Meanwhile, exchanges and stablecoin issuers must balance rapid intervention against the decentralized architecture of the networks they serve. As blockchain adoption expands.

Trust increasingly depends on infrastructure verification as much as cryptographic security. The GIWA scam showed how easily legitimacy can be manufactured, while the Bitget response showed how difficult it can be to contain stolen assets once they cross multiple networks.