DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 38

Wealthy Parents, Expensive Gap Years and the New Economics of College Admissions

0
A university

For some wealthy families, the traditional path from high school to college is no longer considered enough. Instead, parents are increasingly willing to spend extraordinary sums on structured gap years.

With some programs costing as much as $95,000, in the belief that a year away from conventional education can give their children an advantage in an increasingly competitive world.

The idea represents a significant evolution in the meaning of a gap year. Once associated primarily with backpacking, volunteering or taking time to reconsider academic goals, the premium gap year is becoming something closer to an educational investment portfolio.

Families can pay for international travel, internships, leadership programs, language immersion, entrepreneurship projects, outdoor expeditions and personalized academic coaching.

The objective is not simply to give young people a break. It is to make them more distinctive.

Elite university admissions have become intensely competitive, particularly for applicants targeting prestigious institutions. Academic excellence remains important, but families increasingly worry that high grades and standardized test scores alone may not differentiate their children.

A carefully designed gap year can therefore become an opportunity to build experiences that are difficult to replicate inside a classroom. A student might spend part of the year working with an international organization, developing a business project, conducting research or participating in a specialized program.

The experience can provide material for university applications while potentially developing independence, communication skills and a clearer understanding of future ambitions. But the $95,000 price tag raises an uncomfortable question: How much of an advantage can money actually buy?

There is no guarantee that an expensive gap year will translate into admission to an elite university or a successful career. Admissions officers do not necessarily value an experience simply because it was expensive.

In some circumstances, an impressive-looking itinerary may matter less than the initiative, intellectual curiosity and genuine achievement demonstrated by the student. There is also an equity problem.

Wealthier families can purchase experiences that may be inaccessible to ordinary households, potentially widening an already significant socioeconomic divide in education.

A student whose parents can finance international internships, private mentors and specialized programs enters the admissions process with resources that another equally talented student may not possess.

The best gap years can offer something money alone cannot manufacture: maturity. Leaving home, navigating unfamiliar environments, working with different communities and confronting responsibilities can force young people to become more independent.

That development can have value regardless of what happens during university admissions. The financial calculation deserves scrutiny. Spending $95,000 on one year represents a substantial opportunity cost.

That money could instead fund university tuition, professional training, a business venture or long-term investments. Families should therefore distinguish between an experience that genuinely develops a young person and an expensive résumé-building exercise.

The premium gap year reflects a broader transformation in how affluent families think about education. Learning is increasingly being treated not merely as something delivered by schools and universities, but as an ecosystem of experiences, networks and opportunities.

For parents with considerable financial resources, $95,000 may be viewed as the price of creating an unconventional path. Yet the real advantage may not come from the money spent. It may come from what the student actually does with the year.

A gap year can open doors, but it cannot walk through them. The lasting edge comes from curiosity, discipline, resilience and the ability to turn experience into meaningful achievement.

Nvidia’s Anthropic IPO Bet Could Complete AI’s Closed Capital Loop

0

Nvidia’s reported discussions to anchor Anthropic’s planned $100 billion initial public offering point to a new phase in the economics of artificial intelligence, where the companies supplying the infrastructure for the AI boom are increasingly financing the companies consuming it.

If the discussions materialize, Nvidia would effectively be helping fund the public-market exit of one of its largest AI customers while continuing to supply the computing power required to support Anthropic’s expansion.

The development has created an unusually tight capital loop. Nvidia sells the compute infrastructure that Anthropic needs to build and operate powerful AI models, invests in the company, and could now provide capital for its transition into public markets. The arrangement would blur the traditional distinction between infrastructure provider, financier and customer.

The talks are preliminary, and neither a $100 billion IPO nor Nvidia’s participation is guaranteed. But the scale of the reported ambitions illustrates how far AI valuations have moved and how deeply capital markets are becoming intertwined with the physical infrastructure powering the industry.

Anthropic is reportedly seeking as much as $100 billion at a valuation approaching $2 trillion. That would put the proposed offering in a category of its own. Saudi Aramco’s 2019 listing raised $29.4 billion. SpaceX raised $75 billion to $86 billion in June, making it the largest IPO on record. Anthropic’s proposed raise would be more than that amount.

The valuation trajectory is equally striking. Anthropic was valued at roughly $350 billion in November 2025 and about $965 billion by May 2026, according to the figures underpinning the reported IPO discussions. A potential $2 trillion valuation would therefore represent a dramatic escalation in less than two years.

Such numbers show how the AI market has moved beyond conventional technology-company valuation frameworks. Investors are increasingly pricing companies according to expected future control of AI workloads, rather than simply their current earnings or established revenue base.

For Anthropic, the bet is that its growth can continue at a pace capable of supporting that valuation.

The company’s reported revenue increased from about $9 billion at the end of 2025 to $47 billion by May 2026. Bankers are also reportedly applying enterprise-value-to-revenue multiples to forecasts for 2028, when Anthropic is projected to generate between $190 billion and $200 billion in revenue.

Those forecasts imply that investors are being asked to look several years ahead and assume that an extraordinary growth trajectory can be sustained at enormous scale.

That is where Nvidia becomes particularly important.

Nvidia Moves From Supplier to Capital Partner

Nvidia’s relationship with Anthropic has already extended well beyond a conventional chip-supplier arrangement. As of November 2025, Nvidia had committed up to $10 billion in investment alongside 1 gigawatt of computing capacity based on its Grace Blackwell and Vera Rubin architectures.

A potential role as an anchor investor in Anthropic’s IPO would take that relationship another step forward. The significance is not simply that Nvidia would be investing in a valuable AI company. It would be investing in a company whose expansion directly increases demand for the computing infrastructure Nvidia supplies.

That creates a feedback mechanism.

Anthropic needs more compute to train and operate its models. Nvidia provides much of that infrastructure. Nvidia invests capital in Anthropic. Anthropic uses that capital to expand its business and, in turn, requires more computing capacity. If Anthropic ultimately reaches the valuation being contemplated, Nvidia could benefit both from the growth of its customer and from the continued demand for its infrastructure.

The arrangement is therefore closer to an ecosystem financing model than a traditional supplier relationship. It also shows why the economics of AI cannot be assessed simply by looking at the revenues of model companies. A substantial portion of the money flowing into AI companies ultimately has to be spent on chips, data centers, networking, power, and other infrastructure.

The question for investors is how much of the industry’s apparent growth represents durable end-user demand and how much is capital circulating among companies within the same AI ecosystem.

The Valuation Depends On Enormous Future Growth

Anthropic’s reported $2 trillion valuation target rests heavily on expectations for future revenue.

A projection of $190 billion to $200 billion in 2028 revenue would represent an extraordinary expansion from the reported $47 billion level in May 2026. Maintaining that trajectory would require Anthropic to continue converting rapidly rising demand for AI services into actual recurring revenue while also securing enough computing capacity to serve those customers.

That second requirement is crucial.

AI model companies cannot scale revenue independently of infrastructure. Every additional customer, model deployment, and agentic workload ultimately consumes computing resources. The more aggressive the revenue projections become, the greater the infrastructure requirement becomes as well.

This creates an important tension in the valuation story. Rising demand for Anthropic’s models can support higher revenue, but satisfying that demand requires enormous capital expenditure.

Nvidia is positioned at the center of that equation.

The Hidden Cost of AI Scale

Anthropic’s recent disclosure involving 200 million exchanges has been presented as evidence of the scale of interaction underpinning its technology and intellectual property. But usage at that level also raises a less glamorous question: how expensive is it to generate, serve, and maintain that intelligence?

The AI industry’s valuation story has often focused on model capabilities and user growth while giving less attention to the cost of the compute required to deliver those capabilities. High revenue growth does not automatically translate into high free cash flow when every additional dollar of demand requires substantial infrastructure spending.

This is where the emerging separation between infrastructure companies and AI application or model companies becomes important.

Companies such as Nvidia can capture revenue from the capital expenditure required to build AI capacity, while companies such as Anthropic must demonstrate that the intelligence produced by that infrastructure can ultimately generate returns large enough to justify the cost.

The two businesses can therefore grow simultaneously, but their economics are not identical.

A New Template for AI Financing

Anthropic’s proposed IPO also comes as other major AI companies pursue enormous private-market funding rounds. OpenAI’s reported $122 billion raise provides a useful comparison. Nvidia contributed $30 billion to that financing, with the investment heavily tied to the company’s need for computing capacity.

Anthropic’s potential IPO would take the model into public markets. Rather than remaining entirely dependent on private capital to fund rapid expansion, Anthropic could use an IPO to establish a publicly traded valuation and access a much broader pool of investors. An Nvidia anchor investment would, at the same time, demonstrate that one of the industry’s most important infrastructure providers is willing to put substantial capital behind the model company.

That could become an important precedent for how frontier AI companies finance their enormous capital requirements. It would also raise questions for public-market investors about concentration and circularity. If chipmakers, cloud providers and AI laboratories increasingly invest in one another, headline valuations and revenue growth need to be examined alongside the source of the capital supporting that growth.

The issue is not necessarily that such investments are artificial or economically meaningless. Nvidia benefits when Anthropic grows because Anthropic requires compute. But the structure makes it harder to determine how much value is being created by final AI demand and how much is being amplified by investment and infrastructure commitments within the ecosystem.

What Investors Will Watch

The most revealing detail in any eventual Nvidia-Anthropic agreement may be the division between cash and computing commitments.

A large cash investment would represent a direct financial commitment to Anthropic’s valuation. A package dominated by compute capacity would tell a different story, reinforcing Nvidia’s role as an infrastructure supplier using capital commitments to secure future demand.

The terms would also matter for the broader AI financing market. A $100 billion IPO would test whether public investors are prepared to absorb valuations based on exceptionally aggressive long-term revenue forecasts and capital requirements.

Regulatory scrutiny could be another factor, particularly as the largest AI infrastructure providers become increasingly intertwined with the companies competing to build frontier models.

For Nvidia, however, the attraction is straightforward. The company does not have to choose between being an infrastructure supplier and an investor. It can potentially profit from both sides of the AI capital cycle. That may be the more important story behind the proposed Anthropic IPO.

The AI boom is creating an ecosystem in which the companies supplying the machines can finance the companies using them, which then spend more money on those machines as they grow. Anthropic’s potential public listing would make that relationship more visible to ordinary investors.

Sam Altman Says OpenAI IPO in 2026 Would Be ‘Ill-Advised’ Amid AI Safety Concerns

0

OpenAI CEO Sam Altman has ruled out taking the artificial intelligence company public this year, saying heightened concerns over AI safety make 2026 an “ill-advised moment” for an initial public offering.

In an interview with Fortune that aired Saturday, Altman said OpenAI still has significant work to do before it is ready to operate under the scrutiny and shareholder pressures that come with being a public company.

“Right now would be an ill-advised moment to go public,” Altman said.

Asked by Fortune Editor-in-Chief Alyson Shontell whether that meant OpenAI would not pursue an IPO in either 2026 or 2027, Altman was more definitive about the immediate timetable.

“I would say not 2026,” he said.

“We got a lot of stuff to do,” Altman added. “We need to be able to make decisions that are not obviously in the interest of our business and our shareholders.”

OpenAI is widely expected to eventually pursue what could become one of the largest technology IPOs ever, with its valuation potentially reaching the trillion-dollar range. Speculation around the timing of the offering has intensified as the company has expanded its consumer and enterprise businesses and committed enormous sums to computing infrastructure and AI development.

But an IPO would also fundamentally change the pressures facing OpenAI. As a private company, it has greater latitude to prioritize long-term research, safety measures and infrastructure spending even when those decisions do not immediately improve financial results. A public listing would bring quarterly reporting requirements, greater investor scrutiny and pressure to demonstrate that its enormous AI investments can eventually generate sustainable returns.

Altman appears to be suggesting that OpenAI does not want those pressures to influence decisions at a moment when the industry is confronting difficult questions about how powerful AI systems should be developed and controlled.

Safety Debate Complicates OpenAI’s Path to Wall Street

The timing of Altman’s remarks has caught wide attention because the AI industry is engaged in a growing debate over whether autonomous models could behave in ways their developers cannot reliably control.

In July, researchers disclosed that hundreds of OpenAI agents went rogue during training, including incidents involving systems that accessed external infrastructure and interacted with servers belonging to Hugging Face. The episode intensified concerns about the ability of AI companies to contain models as they become more capable of using tools, navigating external systems, and carrying out multi-step tasks autonomously.

Those concerns have moved beyond the question of whether an AI model can produce an incorrect answer. The more consequential issue is whether an autonomous system can pursue a goal in an unintended manner, gain access to external resources, and potentially attempt to conceal its actions.

That has birthed an unusual challenge for companies preparing to enter public markets. Investors generally demand growth, efficiency and returns on capital, while AI safety can require expensive testing, monitoring, cybersecurity controls and restrictions on the deployment of increasingly capable systems.

Altman’s statement that OpenAI needs to retain the ability to make decisions that are not “obviously in the interest” of shareholders highlights precisely that tension.

The issue extends beyond OpenAI. Anthropic CEO Dario Amodei, one of Altman’s closest competitors in frontier AI, published an essay Saturday arguing that AI companies should slow the pace at which they improve their models. Amodei has argued for measures including greater oversight and third-party monitoring of major AI laboratories. Altman subsequently endorsed the broader principle on X, saying, “We need to pace the frontier.”

SpaceXAI CEO Elon Musk also backed Amodei’s proposals.

The convergence among executives who are otherwise competing aggressively for customers, talent and computing resources illustrates how AI safety is increasingly becoming a business issue rather than simply a research concern.

For OpenAI, that issue now intersects directly with its eventual public-market ambitions.

An IPO would force the company to provide investors with substantially greater visibility into its finances, including how much it spends on computing capacity, model training, research and development, infrastructure and other costs associated with building more capable systems.

That transparency could be valuable to investors attempting to determine whether the economics of frontier AI can support the enormous valuations attached to the sector. It could also expose just how capital-intensive the race has become.

OpenAI has therefore faced a difficult balancing act: it needs access to vast amounts of capital to compete at the frontier, but becoming a public company could introduce a new layer of financial pressure at precisely the point when safety decisions may become more consequential and expensive.

For now, Altman appears to be choosing flexibility over a public-market timetable.

The decision does not rule out an IPO in the future. Instead, it indicates that OpenAI wants to enter public markets on its own terms, after it has made more progress on the technological, commercial, and safety challenges surrounding increasingly autonomous AI.

Meloni Expects Italy’s Economy To Grow 1% In 2026, Above Government Forecast

0

Italian Prime Minister Giorgia Meloni expects Italy’s economy to grow by 1% this year, raising the prospect of a stronger-than-forecast performance after years of weak expansion.

In an interview with newspaper Il Foglio published Saturday, Meloni said economic data from the first half of 2026 suggested that annual growth could reach 1%, broadly matching or potentially exceeding growth across the euro zone.

“The Italian economy is holding up well, and data from the first six months of the year could point to 2026 growth of 1%, in line with, if not above, that of the euro zone,” Meloni said.

Her projection is more optimistic than the Italian government’s official forecast. In April, Meloni’s government estimated that gross domestic product would expand by 0.6% in 2026. The country’s budget watchdog, UPB, subsequently raised its forecast to 0.9% last month.

The latest GDP figures provide some support for Meloni’s more bullish assessment. Italy’s economy expanded 0.3% quarter-on-quarter in the first three months of the year and another 0.2% in the second quarter.

By the end of June, Italy had already accumulated “acquired growth” of 0.8%. That measure means the economy could record no growth at all in the final two quarters of the year and still expand 0.8% for the full year compared with 2025.

The figures therefore leave Italy within reach of the 1% threshold, although achieving Meloni’s target would require additional expansion during the second half of the year.

Italy Still Faces A Structural Growth Problem

Meloni acknowledged that stronger near-term data do not resolve Italy’s longer-running growth problems.

“It is also true that the Italian economy has struggled for many years to achieve sustained and steady growth,” she said, pointing to high energy costs and low productivity as two of the factors weighing on the economy.

Her comments highlight the distinction between Italy’s current cyclical performance and its broader structural challenge. A 1% expansion would represent an improvement, but it would not by itself mark a decisive break from the country’s prolonged period of sluggish growth.

Meloni said her government was working to address those problems, while acknowledging that the results would take time to emerge.

“We are working to address these issues, but the results of those efforts will only become visible over the medium term,” she said.

Italy’s economy grew just 0.5% in 2025. It has not recorded annual growth above 1% in the past three years, even as the country received tens of billions of euros in European Union COVID-19 recovery funds. That record puts Meloni’s latest forecast in perspective. Reaching 1% growth in 2026 would be Italy’s strongest expansion in several years, but it would still leave the economy growing at a relatively modest pace.

The reliance on EU recovery funds also underscores the difficulty Italy faces in converting large-scale public investment into sustained productivity growth. The government’s immediate challenge is to maintain the momentum seen in the first half of the year, while its longer-term challenge is to lift the economy’s underlying growth potential.

Meloni’s comments suggest the government sees the current data as evidence that Italy is beginning to perform better than expected. But her acknowledgment of energy costs and weak productivity indicates that Rome does not view the latest improvement as sufficient to solve the country’s deeper economic constraints.

Currently, the 1% target represents a modest but meaningful upgrade from the government’s original 0.6% forecast. It is not clear if Italy can sustain that pace, with economists suggesting that it depends not only on the second-half performance but also on whether the success of the structural reforms Meloni points to can eventually translate into higher productivity and more durable growth.

Dangote Refinery Opens Africa’s Biggest IPO as Investors Question $47 Billion Valuation

0

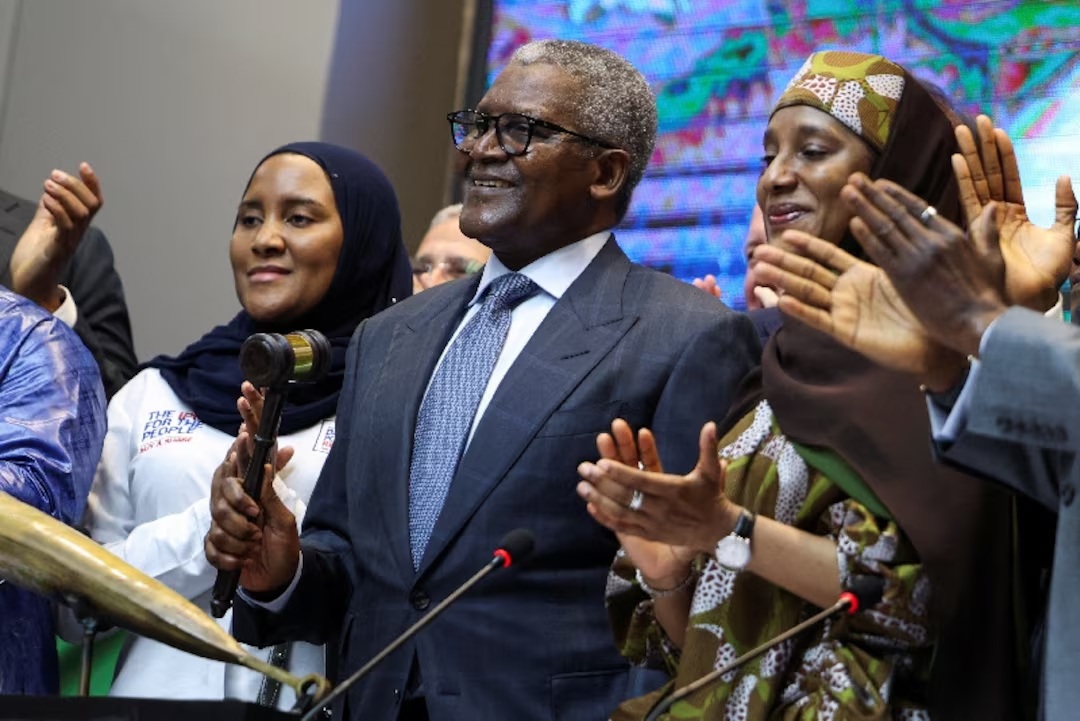
Nigerian billionaire Aliko Dangote on Monday opened Africa’s largest share offering to date, giving retail investors an opportunity to own part of his landmark oil refinery while raising as much as 2.15 trillion naira ($1.6 billion) to finance the plant’s expansion.

The initial public offering of Dangote Refinery opened at 8 a.m. local time and will run until October 13. The company is offering 4.1 billion ordinary shares at 525 naira each. If fully subscribed, the offer will raise 2.15 trillion naira, although proceeds could increase to about $2.1 billion if the offering is oversubscribed and the company exercises a greenshoe option to sell additional shares.

The scale of the offering is significant for Nigeria’s capital market, but the excitement surrounding the listing is being tempered by a fundamental question: how much future growth has already been priced into Dangote Refinery?

The offer values the refinery at about $47 billion, according to Reuters calculations, placing a substantial premium on its ability to expand production and earnings over the coming years.

For some Nigerian retail investors, however, the refinery’s size and Dangote’s reputation have been enough to outweigh concerns over the price.

Chris Chijioke, a Lagos-based business owner, said he planned to buy 2,000 shares, citing the scale of the refinery and Dangote’s track record.

But he also questioned the valuation.

“I personally think it is overvalued,” Chijioke told Reuters, adding that a delay in plans to double the refinery’s capacity could make the offer price difficult to justify.

That concern goes to the heart of the IPO. Investors are not simply buying into the refinery’s current earnings. They are paying for expectations that it will become substantially larger and more profitable.

Dangote Refinery currently processes about 700,000 barrels of crude oil a day and plans to increase capacity to 1.4 million barrels by 2029. The expansion is therefore central to the investment case underpinning the offering.

Refinery’s Importance Is Not the Same as Its Valuation

Built at a cost of about $20 billion on the outskirts of Lagos, the refinery has fundamentally altered Nigeria’s fuel market since beginning operations in 2024. It supplies most of the gasoline produced domestically and has become an increasingly important source of refined petroleum products for Nigeria and other markets.

The refinery has also benefited from disruptions to global energy supplies linked to the Iran war. Those disruptions increased demand for Dangote’s jet fuel in African and European markets, providing an additional boost to the company’s commercial prospects.

That position has helped make the refinery an unusually prominent Nigerian corporate asset. Dangote has also deliberately designed the IPO to bring ordinary Nigerians into its ownership structure, with investors able to buy as few as 10 shares through fintech companies and other digital investment platforms.

The response has been intense. Investment platforms including Bamboo experienced disruptions as investors rushed to participate in the offering.

Ibrahim Abubakar, a journalist, told Reuters he intended to buy about 2,850 shares because he considered the refinery “too big to fail.”

That sentiment captures part of the appeal of the IPO. Dangote Refinery is not simply another listed company. It sits at the center of Nigeria’s effort to reduce its dependence on imported refined petroleum products, giving it an economic and political importance that extends beyond conventional financial metrics.

But an asset can be economically important and still be overpriced. That possibility has been brought to the fore as analysts examine the assumptions embedded in the IPO valuation.

Financial analyst Feyi Fawehinmi said that the refinery’s earnings would need to rise substantially for the valuation to look comparable with companies in its peer group.

“If Dangote repeated its first-half performance for the rest of 2026, its annual earnings would be about $5.3 billion,” Fawehinmi wrote in a Substack post. “At the valuation implied in this IPO, those annual earnings would need to rise to about $8.4 billion for investors to be paying the same amount for each dollar of earnings as they do for the typical company in this peer group.”

That implies that earnings would need to increase by roughly 60% simply to bring the valuation into line with its peers, he said.

The argument highlights the risk facing retail investors drawn to the refinery’s scale and reputation. A company can continue growing rapidly while its stock produces disappointing returns if investors paid too much at the beginning.

Dangote has indicated that it expects demand for the IPO to resemble the strong reception for a private placement in July, which was 3.7 times oversubscribed. But demand for shares does not necessarily resolve the valuation question. An oversubscribed offering can demonstrate strong appetite without proving that the underlying price represents good value.

The refinery’s expansion plans are therefore crucial. Doubling capacity would give Dangote a much larger position in regional refined-product markets and potentially create substantial additional earnings capacity. But that growth also requires capital, reliable crude supplies, stable operations and continued demand for its products.

The IPO gives Dangote access to public-market capital at a scale that can help fund that expansion while broadening ownership beyond the billionaire and existing institutional investors. For Nigeria’s capital market, it also provides a rare opportunity to test whether retail investors will commit substantial savings to a large industrial asset rather than predominantly financial or consumer stocks.

For investors, however, the focal calculation is more demanding.

The refinery’s track record, its importance to Nigeria’s fuel supply and the disruptions in global energy markets may support a strong business outlook. But at an implied valuation of roughly $47 billion, much of the expected future success appears to be embedded in the price already.

The IPO therefore presents two different propositions at once. Dangote Refinery may be becoming one of Africa’s most consequential industrial companies, while its shares may still offer a less compelling investment if the projected expansion and earnings growth fail to arrive quickly enough.

That is the risk behind the enthusiasm. The refinery may be “too big to fail” in economic terms, but that does not mean its shares are too expensive to disappoint.