DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 56

MrBeast’s Next Move Could Put His Brand on Your Wrist

0

MrBeast has built an unusual kind of business empire: one that begins with entertainment but increasingly extends into products, technology and consumer experiences.

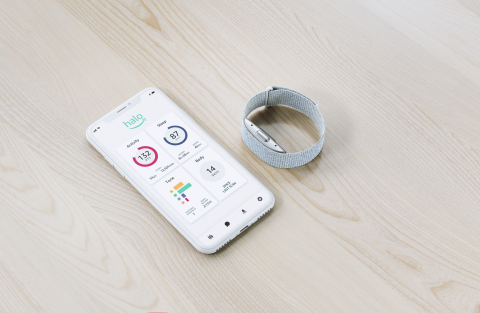
Now, a new trademark filing suggests that Jimmy Donaldson, better known as MrBeast, could be preparing to take another step into the physical technology market with a product called “Beast Band.”

Beast Holdings, LLC filed a U.S. trademark application for the name “Beast Band.” The filing covers wearable activity trackers, smartwatch bands and wearable activity-tracking products.

It was submitted on an intent-to-use basis, meaning the filing signals an intention to use the trademark commercially, but does not establish that a product has already launched. That distinction matters.

A trademark application is not a product announcement, and there is currently no confirmed launch date, pricing information or detailed specification for a Beast Band. But the filing provides a useful glimpse into where the MrBeast business could be heading.

Wearables would represent an interesting extension of the creator’s influence. Activity trackers sit at the intersection of technology, fitness and lifestyle—three areas where a creator with a massive young audience can potentially build a direct consumer relationship.

Instead of watching a MrBeast video for several minutes, a customer wearing a Beast Band could interact with the brand throughout the day. The opportunity also fits into a broader strategy emerging around Beast Industries.

The company has explored businesses beyond Donaldson’s core YouTube operation, including consumer products and other services designed to operate without requiring the creator to personally appear in every transaction.

Previous company planning has included health and wellness products, including nutrition and personal-care categories. A wearable device could therefore become more than another piece of merchandise.

If developed as a genuine technology product, it could potentially connect fitness tracking with challenges, rewards, digital memberships or other elements of the broader Beast ecosystem.

The timing is also notable because the wearable market is already highly competitive. Apple, Google, Fitbit, Samsung, Garmin and numerous specialist companies have spent years building hardware, health platforms and data ecosystems.

A Beast-branded tracker would therefore enter a market where brand recognition alone may not be enough. Accuracy, battery life, software integration, privacy and usefulness would determine whether consumers continue wearing the device after the novelty disappears.

There is another possibility: Beast Band could ultimately be developed through a partnership rather than entirely in-house.

MrBeast’s company has increasingly demonstrated an interest in collaborations that can place its brand inside established consumer categories without necessarily building every piece of infrastructure itself.

The current trademark filing does not reveal who, if anyone, would manufacture the product. The most concrete development is simply the trademark. Beast Holdings has claimed the Beast Band name in a category explicitly covering wearable technology, but there is no confirmed commercial product yet.

The filing illustrates how the MrBeast brand continues to evolve. What began as a YouTube identity is becoming an increasingly diversified consumer platform. If Beast Band eventually reaches consumers, the next chapter may see MrBeast competing not just for attention on screens, but for space on people’s wrists.

Artificial Intelligence Could Get a New Name Under Trump’s Proposal

0

The phrase “artificial intelligence” has become so embedded in technology, business and everyday language that changing it might seem almost impossible.

Yet in September 2026, President Donald Trump proposed doing exactly that, arguing that the word “artificial” makes intelligence sound fake. He initially offered Americans three alternatives: Superior Intelligence, Extreme Intelligence and Supreme Intelligence.

Days later, at the United Nations General Assembly, Trump said the technology would henceforth be referred to by the new name “super intelligence.”

The unusual proposal opens a broader conversation about how technology is framed. Names do not change what a machine can do, but they influence how people understand its purpose, potential and risks. Trump’s suggested alternatives were designed to emphasize capability rather than artificiality.

“Superior Intelligence” implies intelligence that exceeds conventional human performance, while “Extreme Intelligence” emphasizes scale and power. “Supreme Intelligence,” meanwhile, carries the strongest suggestion of technological supremacy.

None of the three is an established technical category in computer science.  The history of the existing term is itself a reminder that technology names are not inevitable. “Artificial intelligence” emerged from the academic work surrounding the 1956 Dartmouth conference.

Where computer scientists including John McCarthy, Marvin Minsky, Claude Shannon and Nathaniel Rochester helped establish the field. Before the terminology became standardized, researchers used descriptions including cybernetics, automata studies and complex information processing.

That history makes Trump’s proposal less about inventing an entirely new concept and more about changing the language surrounding an existing technological revolution.

The proposed alternatives also reveal how dramatically the public conversation around AI has changed. When the term was popularized in the 1950s, computers were primitive compared with today’s systems.

Modern models can generate software, analyze enormous datasets, produce images and video, interact conversationally and perform increasingly sophisticated professional tasks. For Trump, describing these systems as merely artificial understates their capabilities.

At the UN, he said the word made intelligence sound fake and announced that U.S. government documents would use super intelligence instead. There is, however, a practical distinction between political language and technical terminology.

A president can direct terminology used within government communications, but artificial intelligence is not a legally protected name that can simply be erased from global usage. Technology companies, researchers, universities and international institutions have spent decades using AI as the standard description.

The naming debate arrives during a much larger argument over the direction of AI policy. Trump has simultaneously announced plans for an AI Force and a new AI czar, while emphasizing rapid technological development and U.S. competition with China.

Whether the technology is called artificial intelligence, superior intelligence, extreme intelligence or super intelligence does not alter its underlying capabilities. The more consequential question is what governments, companies and societies do with those capabilities.

The terminology may evolve, but the economic, regulatory and technological consequences of increasingly powerful AI will remain the central issue.

How Banks Can Measure the Business Value of Artificial Intelligence

Artificial intelligence is moving from the margins of financial services toward the center of how institutions operate, compete and manage risk.

Banks, insurers, asset managers and fintech companies have spent years experimenting with machine learning, generative AI and automated decision systems. Yet experimentation is proving easier than transformation.

The difficult question is no longer whether financial institutions can use AI, but whether they can deploy it at scale without compromising trust, security or financial discipline. The opportunity is substantial.

AI can process enormous volumes of financial information, identify patterns that humans may overlook and automate repetitive work. In banking, this can mean faster fraud detection, more sophisticated credit assessment, personalized customer services and automated compliance processes.

Asset managers can use AI to analyze market data, corporate disclosures and alternative datasets. Insurers can apply similar technologies to underwriting, claims processing and risk assessment.

Generative AI has expanded the opportunity further by making sophisticated analytical tools accessible through natural language. Employees can potentially summarize documents, generate reports, search internal knowledge and interact with complex datasets without relying entirely on specialized technical teams.

This could reduce administrative costs while allowing professionals to devote more time to decisions requiring judgment. But financial institutions face a fundamental scaling problem. A successful pilot does not automatically become a reliable enterprise system.

An AI model that performs well in a controlled environment can encounter very different conditions when connected to millions of customers, legacy technology and constantly changing financial data.

Institutions therefore need infrastructure capable of supporting AI securely and consistently across business units. Data is central to this challenge.

Financial AI depends on high-quality, accessible and appropriately governed information. Fragmented databases, inconsistent definitions and outdated technology can undermine even the most sophisticated model.

Building a scalable AI strategy consequently requires investment in data architecture, cloud infrastructure, cybersecurity and application programming interfaces alongside investment in the models themselves. The economics of AI demand greater discipline.

Financial executives cannot simply count the number of AI projects launched. They need measurable outcomes. Does an application reduce processing time? Does it lower fraud losses? Does it improve customer retention? Does it increase employee productivity without creating additional operational risk?

These questions turn AI from a technology experiment into an investment decision. Risk management becomes equally important as deployment expands. AI systems can produce inaccurate outputs, inherit biases from training data, expose confidential information or become vulnerable to manipulation.

In highly regulated financial markets, an institution must also be able to explain how important automated decisions are made and establish accountability when systems fail.

This means governance cannot be treated as an obstacle to innovation. Clear human oversight, model validation, access controls, audit trails and continuous monitoring can become part of the infrastructure that makes large-scale adoption possible.

The objective is not necessarily to eliminate human involvement, but to determine where humans remain essential and where machines can safely perform routine tasks.

The competitive landscape is likely to reward institutions that combine technological ambition with organizational discipline. AI adoption will increasingly involve partnerships among executives, engineers, data scientists, compliance professionals and frontline employees.

Institutions that treat AI solely as an IT project may struggle to capture its broader economic value. The transformation of financial services through AI will not be determined by who adopts the most advanced model first.

It will depend on who can integrate AI into real business processes while maintaining reliable data, measurable economics, strong governance and customer trust. The next phase is therefore less about experimentation and more about execution.

AI’s lasting impact on finance will emerge when institutions turn promising demonstrations into dependable infrastructure.

Canada’s Six Biggest Banks Launch Tokenized Deposits Project for 24/7 Blockchain Payments

0

Canada’s banking sector is taking another step toward blockchain-based finance as the country’s six largest banks move to develop a joint tokenized deposits project designed to support 24/7 payments on blockchain networks.

The initiative reflects a broader shift in financial infrastructure, where traditional banks are increasingly exploring how programmable digital money can operate alongside existing payment systems.

Tokenized deposits essentially represent traditional bank deposits in digital form on a blockchain.

Unlike cryptocurrencies, they remain claims against regulated financial institutions and are designed to preserve the familiar relationship between customers and commercial banks.

The technology, however, can allow those deposits to move across blockchain infrastructure, potentially making settlement faster, more automated and available beyond conventional banking hours.

The participation of Canada’s largest banks is significant because it places established financial institutions directly inside the development of digital-asset infrastructure. Rather than treating blockchain as a parallel financial system.

The project suggests that banks are examining how distributed-ledger technology could become part of the banking system itself. The promise of 24/7 payments is particularly important. Traditional financial infrastructure often depends on operating windows, settlement schedules and intermediaries.

Blockchain networks, by contrast, can operate continuously. Tokenized deposits could therefore allow businesses and financial institutions to transfer value at any time, including weekends and holidays, subject to the rules and infrastructure governing the network.

For corporate finance, the implications could extend beyond simply sending money faster.

Tokenized deposits could support programmable payments in which transactions are automatically executed when predetermined conditions are met. A company could, for example, structure a payment so that funds are released when a shipment is verified.

A financial obligation is settled or a digital asset changes ownership. This creates a potential connection between payments, tokenization and capital markets. As stocks, bonds, funds and other financial assets increasingly move onto blockchain infrastructure, the ability to transfer regulated bank money on the same technological rails could become increasingly important.

The development of tokenized deposits is therefore part of a larger effort to build financial markets in which money and assets can interact programmatically. The project also highlights the competitive pressure facing banks from stablecoins and other forms of digital money.

Stablecoins have demonstrated that blockchain-based payment instruments can move value globally and continuously. Banks now face the question of whether traditional deposits can acquire similar technological capabilities without abandoning the regulatory and institutional structures that underpin commercial banking.

However, tokenized deposits will not eliminate the challenges associated with blockchain finance. Regulatory compliance, privacy, cybersecurity, interoperability and consumer protection remain critical considerations.

Banks must also determine how different blockchain networks can communicate with existing payment systems and with one another. A tokenized deposit system that cannot operate reliably across financial institutions would have limited practical value.

There is also a broader question about whether blockchain genuinely reduces costs and settlement friction at scale. Financial institutions must demonstrate that the technology provides measurable advantages over increasingly sophisticated conventional payment infrastructure.

Canada’s initiative nevertheless represents an important experiment in the evolution of banking. The involvement of the country’s biggest banks indicates that blockchain is increasingly being examined not simply as an alternative to traditional finance, but as a potential layer for modernizing it.

If tokenized deposits prove commercially viable, the consequences could reach beyond domestic payments. They could eventually support programmable corporate finance, faster securities settlement and more interconnected digital capital markets.

The most important development may therefore be less about putting bank deposits on a blockchain and more about changing what those deposits can do. A 24/7, programmable form of commercial-bank money could become a foundational component of the emerging tokenized economy.

Paramount and Warner Bros. Discovery Employees Brace for Internal Competition After the Merger

0

A merger can be sold to investors as a strategy for creating scale, efficiency and stronger competition. Inside the companies being combined, however, the same transaction can look very different.

For employees at Paramount and Warner Bros. Discovery, the prospect of a merger brings another reality into focus: once two organizations become one, colleagues who previously worked for separate companies can suddenly find themselves competing for the same jobs, budgets and leadership positions.

The expected combination would bring two major entertainment businesses with extensive film studios, television networks, streaming platforms and intellectual property libraries. On paper, the logic is straightforward.

A larger company could potentially spread production costs across a broader portfolio, strengthen its negotiating position and create new opportunities to package content across traditional television and streaming. Yet achieving those benefits usually requires difficult decisions about overlapping operations.

That overlap is where employees are likely to feel the greatest pressure. Paramount and Warner Bros. Discovery already have large corporate structures supporting finance, marketing, technology, advertising, legal affairs, human resources and content operations.

A combined company would not necessarily need two of everything. Even where executives describe the merger as an opportunity for growth, eliminating duplicated functions can become an important part of realizing expected efficiencies.

For employees, this creates an unusual form of internal competition. Workers who once competed against rival companies in the marketplace may eventually compete against one another inside the same organization.

Two marketing teams could be asked to demonstrate which approach should become the standard. Executives from both sides could compete for senior positions. Different production units could face questions about which projects deserve investment.

Even employees with similar responsibilities could be evaluated against one another as management redesigns the organizational structure.

The uncertainty can be particularly significant for creative industries.

Entertainment companies depend heavily on producers, writers, directors, actors and executives who understand particular audiences and franchises. Cutting too deeply can reduce costs, but it can also remove institutional knowledge and weaken relationships that took years to build.

Management therefore faces a difficult balance between eliminating duplication and preserving the talent responsible for generating valuable content. Streaming adds another layer to the challenge.

The entertainment business has already experienced years of restructuring as companies attempt to balance expensive content production with subscriber growth, advertising revenue and profitability. A merger does not eliminate those pressures. Instead, it combines them.

Leadership would have to determine how streaming strategies, television networks, film releases and advertising businesses fit into a single corporate architecture. For employees, that means the merger is not simply about whether Paramount and Warner Bros. Discovery become a larger entertainment company.

It is also about what happens after the celebration surrounding the transaction ends. Organizational charts must be redrawn, reporting lines established and responsibilities reassigned.

Some employees may gain broader opportunities, while others could discover that their roles overlap with positions already occupied elsewhere in the new organization. The situation also illustrates a broader transformation across traditional media.

Scale has become increasingly important as companies confront streaming competition, changing advertising economics and the enormous cost of premium content. Consolidation can provide financial resources and distribution power, but it can also create significant human consequences.

The success of a Paramount-Warner Bros. Discovery combination would depend on more than the size of the resulting company. It would depend on whether management can integrate two corporate cultures without destroying the creative and operational strengths that made both organizations valuable.

For employees, the immediate question is much more personal: after the merger, who gets to stay, who gets promoted, and whose way of doing business becomes the model for the new company? That uncertainty may make the period after closing just as consequential as the merger itself.

Indian AI Startup Brahma AI Raises $150m at $2bn Valuation, Betting on Hollywood-Grade Generative AI

0

Indian artificial intelligence startup Brahma AI has raised $150 million from private equity firm Multiples Alternate Asset Management at a $2 billion valuation, turning the company into one of India’s more closely watched bets on the commercialization of generative AI for audiovisual content.

The funding round, announced Wednesday, gives Brahma AI substantial capital to expand an enterprise-focused platform that combines artificial intelligence with technologies developed for high-end film and television production.

Brahma AI is owned by Indian media and entertainment company Prime Focus through its UK-based subsidiary DNEG, the visual effects and animation studio behind major productions including the Dune franchise and The Odyssey. Prime Focus said it will retain a 66% stake in Brahma AI through DNEG following the investment.

The funding could also become larger. Brahma AI has received an additional $100 million in investor demand and is considering increasing the size of the round to accommodate some or all of that interest, Prime Focus said.

The investment is notable because it puts a significant private-market valuation on a company operating at the intersection of two industries undergoing rapid technological change: enterprise software and media production.

Rather than positioning itself as another general-purpose AI model developer, Brahma AI is attempting to commercialize the specialized technology developed for Hollywood visual effects, animation and digital humans and make it available to businesses across multiple industries.

“Our ambition is much bigger: to build the AI-native technology platform through which the world’s leading enterprises manage, understand, create and transform their audiovisual assets,” Prabhu Narasimhan, founder and chief executive of Brahma AI, said in the company’s statement.

The company’s strategy is built around the idea that audiovisual data will become an important enterprise asset as businesses generate larger volumes of video, audio and other digital content.

Brahma AI says it is developing tools that can help companies create, manage and transform those assets rather than simply generate synthetic images or videos. That strategy places the company closer to an enterprise infrastructure and workflow provider than a conventional consumer-facing generative AI application.

Its current focus spans four sectors: media and entertainment, sports, healthcare and advertising. Its global anchor customers include Warner Bros., the NBA and Mayo Clinic.

The company is also preparing to expand into interactive digital humans, a technology that could have applications ranging from entertainment and advertising to customer service, training and healthcare.

“We are close to launching interactive digital humans,” Narasimhan said, describing technology designed to replicate the likeness and persona of real individuals to make digital interactions more closely resemble face-to-face encounters.

The technology raises the commercial value of Brahma’s platform while also placing greater emphasis on issues such as identity rights, consent, and the management of digital replicas. For companies working with recognizable individuals, the ability to reproduce a person’s appearance and persona could create new forms of digital content, but it also requires controls around who can authorize and deploy those representations.

Brahma AI is also seeking to avoid being tied to a single underlying AI model. Narasimhan said the company’s technology stack will be model-agnostic, potentially allowing enterprises to use Brahma’s applications and workflows as the underlying AI model ecosystem continues to change.

That could be an important part of its enterprise proposition. The generative AI market is evolving quickly, with model providers competing on price, capability, and specialized performance. An enterprise platform that sits above those models could theoretically retain value even as individual models become obsolete or interchangeable.

Brahma’s origins give it another potential advantage.

In February last year, the company acquired UK-based Metaphysic, a generative AI media company specializing in real-time synthetic content. Metaphysic was included in Time magazine’s list of the 100 most influential companies in 2023.

Brahma is now attempting to combine Metaphysic’s generative AI capabilities with DNEG’s visual-effects expertise and Prime Focus’ broader media technology operations.

Narasimhan said the objective was to combine technology developed across DNEG, Metaphysic and Prime Focus into an AI-native platform aimed at the world’s largest enterprises. That combination is central to the company’s $2 billion valuation. Investors are not simply backing another AI software startup. They are effectively betting that Brahma can turn specialized production technology developed for blockbuster entertainment into a scalable enterprise platform.

The investment also highlights a broader shift in India’s AI market.

India has traditionally been recognized for its large technology-services industry and its role as a major source of engineering and software talent. Increasingly, Indian companies are attempting to build proprietary AI products and platforms that can compete for enterprise spending globally.

Brahma’s connection to DNEG provides it with an unusual route into that market. DNEG has spent years building technology for some of the world’s largest film productions, where visual effects require sophisticated computer graphics, simulation, rendering, compositing, and increasingly machine-learning capabilities.

The challenge is converting those capabilities into repeatable enterprise products.

The $150 million investment gives Brahma considerable financial resources to pursue that transition, but the $2 billion valuation also raises the bar for execution. The company will need to demonstrate that its technology can move beyond high-value media productions into repeatable, scalable enterprise applications across healthcare, sports, advertising, and other industries.

Its decision to remain model-agnostic could help with that expansion, particularly as enterprises become more reluctant to commit their AI strategies to a single model provider. But it also means Brahma will need to establish a differentiated layer of technology and workflow that customers consider valuable enough to pay for independently of the underlying models.

Multiples sees the company’s combination of technology and industry expertise as a central part of the opportunity.

“Brahma AI is built on a unique heritage of Hollywood-grade technology and enterprise innovation,” said Renuka Ramnath, founder, managing director and chief executive of Multiples Alternate Asset Management.

For Prime Focus, the investment provides a way to monetize technology developed across its media and visual-effects businesses while retaining majority ownership of the AI company.

For Multiples, the deal provides exposure to an AI market increasingly moving beyond foundation models toward specialized applications and enterprise infrastructure.

And for Brahma AI, the immediate task is to turn its Hollywood pedigree and growing customer base into a technology platform capable of serving a much larger corporate market. The additional $100 million of investor interest suggests that demand for the round is strong, but the more important test will be whether Brahma can translate that investor enthusiasm into recurring enterprise revenue and a scalable AI business.

At a $2 billion valuation, the company is being priced not merely for its existing audiovisual technology, but for the possibility that AI-generated and AI-managed media becomes a major enterprise software category.