DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 62

Abraxas Capital’s Massive ETH Position Highlights Growing Crypto Market Hedging

0

Abraxas Capital is drawing attention in the Ethereum market after reportedly purchasing another 13,000 ETH, worth approximately $32.39 million, as part of a strategy designed to hedge its enormous short position on Hyperliquid.

According to blockchain analytics platform Lookonchain, the investment comes alongside a short position of roughly 141,180 ETH, valued at about $353.27 million. The unusual combination of spot Ethereum holdings and a large derivatives short highlights how sophisticated crypto traders can manage exposure without making a simple directional bet on whether ETH will rise or fall.

At first glance, buying Ethereum while simultaneously maintaining a substantial short position appears contradictory. A trader who expects ETH to decline would normally benefit from selling or shorting the asset rather than accumulating it.

However, the strategy makes more sense when viewed through the lens of portfolio hedging. By holding actual ETH, Abraxas can offset some of the losses generated by its short position if Ethereum rises sharply.

For example, if ETH increases in value, the short position would lose money because Abraxas would eventually need to close the position at a higher price.

However, the spot ETH holdings would appreciate at the same time. This creates a natural hedge that can reduce the portfolio’s sensitivity to Ethereum’s price movements. Conversely, if ETH falls, the short position can generate gains, while the spot holdings decline in value.

The strategy can become even more attractive when funding rates are favorable. Perpetual futures contracts on platforms such as Hyperliquid use funding payments to keep derivative prices aligned with the underlying asset.

Depending on market conditions, traders holding short positions can receive funding from long-position holders. In such circumstances, a trader can potentially earn funding income while maintaining a relatively hedged exposure to ETH.

This means Abraxas may not necessarily be making a straightforward prediction that Ethereum will collapse. Instead, the firm could be attempting to exploit the difference between spot and derivatives markets.

Using its ETH holdings to reduce directional risk while seeking returns from funding, basis, or other market inefficiencies. The scale of the reported short remains significant. The additional 13,000 ETH represents only a fraction of the approximately 141,180 ETH short position.

Consequently, the latest purchase should not automatically be interpreted as evidence that Abraxas is fully hedged. The overall hedge ratio depends on the firm’s complete portfolio, including other spot holdings, derivatives, collateral, leverage and potentially additional positions that are not publicly visible.

The transaction demonstrates the increasingly sophisticated structure of institutional crypto trading. Large digital-asset investors are no longer limited to simply buying Bitcoin or Ethereum and waiting for prices to rise.

They can combine spot assets, perpetual futures and funding mechanisms to construct market-neutral or partially hedged strategies. For Ethereum, activity of this magnitude can also influence market sentiment.

Traders watching blockchain data may interpret large purchases as bullish accumulation, while the corresponding short position suggests a more nuanced strategy. The important distinction is that the two positions can exist simultaneously without representing a contradiction.

Abraxas Capital’s latest 13,000 ETH purchase therefore offers a glimpse into the complexity of modern crypto markets. Rather than betting exclusively on Ethereum’s next move, sophisticated traders can use opposing positions to manage volatility and potentially generate returns from market structure.

The real question is not whether Abraxas is bullish or bearish, but how effectively its overall portfolio balances the risks and opportunities created by its massive Hyperliquid position.
Why the Magnificent Seven Are No Longer One AI Trade

0

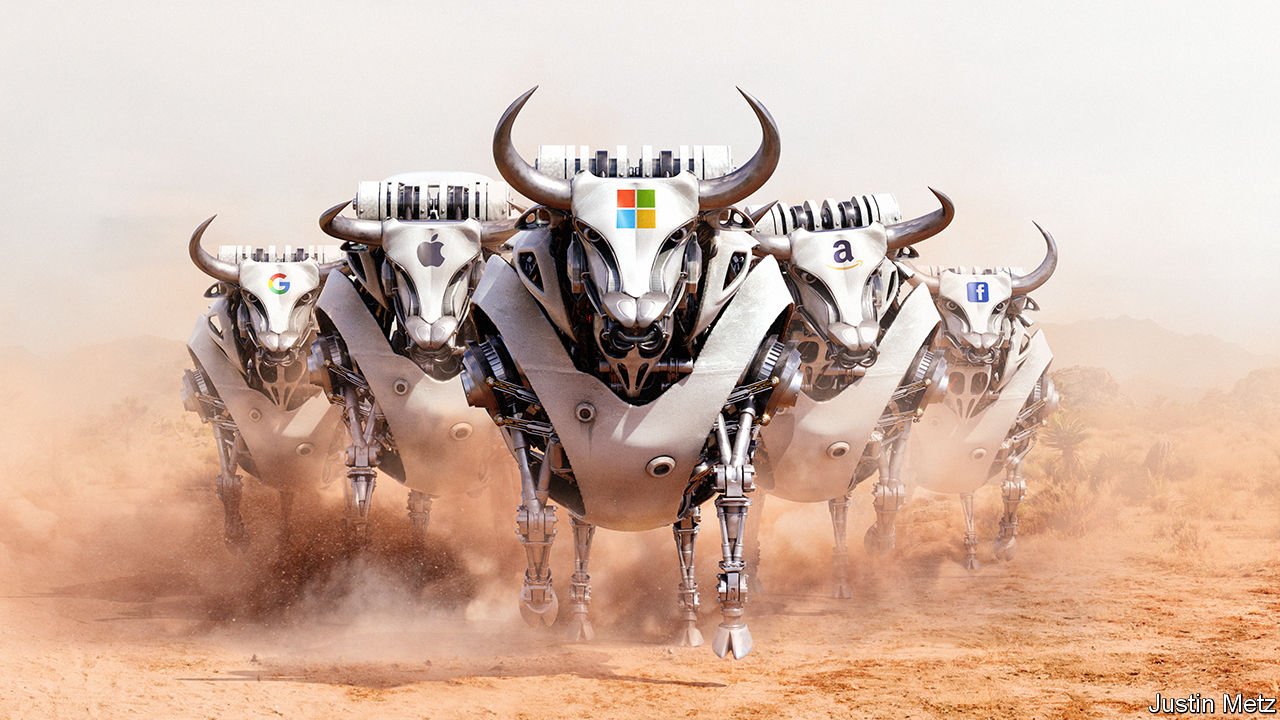
The idea of buying the “Magnificent Seven” as a single artificial intelligence trade is becoming increasingly difficult to justify, according to Plexo Capital founder Lo Toney.

While the seven technology giants are often grouped together as the primary beneficiaries of the AI boom, their business models, exposure to AI infrastructure and ability to generate returns from massive investments are increasingly different.

At the center of Toney’s argument is a simple dividing line: which companies control the infrastructure, and which companies can actually turn that infrastructure into sustainable profits.

The distinction matters because the AI revolution requires unprecedented levels of capital spending. Data centers, advanced chips, networking equipment and energy infrastructure require billions of dollars before companies can determine whether the resulting AI services will generate adequate returns.

Google, Microsoft and Amazon are among the companies making enormous investments in data centers and AI infrastructure.

These investments could strengthen their competitive positions, but they also create significant financial pressure.

Their challenge is not simply building AI capacity; it is demonstrating that the revenue generated from cloud computing, AI products and digital services can justify the enormous capital expenditures required to support them.

Nvidia occupies a different position in this equation. Rather than primarily financing the infrastructure needed to develop AI, Nvidia supplies the critical computing hardware that many of the world’s largest technology companies need.

Its customers are spending heavily on data centers and AI models, while Nvidia collects revenue from the demand for its GPUs and related technology. That distinction gives Nvidia an important position in the AI value chain.

If companies continue competing to build increasingly powerful AI systems, demand for high-performance computing could remain strong. Nvidia is not completely insulated from the broader AI investment cycle.

If customers eventually reduce capital expenditures because AI returns disappoint, demand for its products could also weaken. Meta and Apple represent another category. Both companies can use AI to reinforce businesses that already have established revenue engines.

Meta can integrate AI into advertising, recommendation systems and consumer products, potentially improving the efficiency and value of its enormous digital ecosystem.

Apple, meanwhile, can use AI to make its hardware and software more useful while strengthening the attractiveness of its devices and services.

Tesla presents a different proposition again. Its AI strategy is closely connected to autonomous driving, robotics and physical products. That could create a massive opportunity if Tesla successfully commercializes these technologies.

Yet the path is more complicated because regulatory requirements, manufacturing economics and profitability remain important considerations. For Toney, Google stands out because it combines several advantages.

The company owns significant data-center infrastructure, develops its own custom AI chips and operates businesses capable of monetizing that infrastructure. Search, cloud computing, advertising and emerging AI products provide multiple potential channels through which Google’s AI investments can translate into revenue.

The broader lesson is that investors may need to stop treating the Magnificent Seven as a uniform AI basket. The companies occupy different positions across the AI economy, from semiconductor suppliers and infrastructure owners to advertising platforms, hardware manufacturers and autonomous-technology developers.

As AI spending grows, the key question may therefore shift from who is investing the most to who can capture the most value. Companies that control critical infrastructure or possess established mechanisms for monetizing AI could have an advantage over those still trying to prove that enormous AI investments can become profitable businesses.

China Gold Reserves and the Global Shift Away From Dollar-Dominated Assets

0

China’s central bank has continued its steady accumulation of gold, purchasing another 20 tons in August and matching its largest monthly addition since 2023.

The move reinforces a broader trend among central banks seeking to strengthen their reserves with an asset that carries no direct exposure to another country’s monetary policy or financial system.

The latest purchase is significant because China has been gradually rebuilding and diversifying its gold holdings after a period of strong global demand for the precious metal.

Central-bank buying has become one of the most important structural forces supporting the gold market, particularly as governments reassess the role of traditional reserve currencies in a changing geopolitical environment.

Gold has increasingly been viewed as a strategic reserve asset rather than simply an investment commodity.

Unlike foreign government bonds, gold does not depend on the creditworthiness of an issuing government. It can also serve as a hedge against inflation, currency depreciation, financial instability and geopolitical risk.

For China, these characteristics are particularly relevant as Beijing continues to manage its large foreign-exchange reserves and navigate tensions within the international financial system.

The August purchase comes against a backdrop of elevated gold prices. Strong demand from central banks, investors and consumers has contributed to gold’s resilience even as interest-rate expectations and global economic conditions fluctuate.

When central banks continue buying at relatively high prices, it signals that their objective may extend beyond short-term returns.

China’s strategy can therefore be interpreted as part of a longer-term reserve diversification program.

The country remains one of the world’s largest holders of foreign-exchange reserves, with a substantial portion historically associated with U.S. dollar-denominated assets. Increasing gold holdings provides another layer of diversification and potentially reduces dependence on any single reserve asset.

The trend also reflects a broader transformation in central-bank behavior. After decades in which gold played a smaller role in international monetary reserves, central banks have become increasingly active buyers.

Concerns about sanctions, geopolitical fragmentation, sovereign debt and the future structure of global trade have encouraged policymakers to reconsider how reserves should be allocated.

For China, gold accumulation can also have implications for the yuan. A larger gold reserve does not automatically make the Chinese currency a global reserve currency, but it can strengthen perceptions of the country’s financial resilience.

Over time, continued gold purchases could support Beijing’s efforts to develop a more diversified monetary and financial architecture. However, China’s buying should not be interpreted as an immediate rejection of the U.S. dollar.

Gold remains only one component of national reserves, and China continues to participate deeply in the global dollar-based financial system. Instead, the purchases suggest a gradual effort to reduce concentration risk while maintaining flexibility.

The 20-ton August addition is therefore important beyond the headline figure. Matching the largest monthly purchase since 2023 demonstrates that China’s appetite for gold remains strong despite elevated prices.

If this pattern continues, Chinese demand could remain a major source of structural support for the gold market. China’s gold accumulation illustrates how reserve management is changing in an increasingly fragmented global economy.

Central banks are placing greater emphasis on diversification, liquidity and assets that can retain value during periods of uncertainty. As geopolitical and monetary risks remain elevated, gold’s traditional role as a reserve asset may become increasingly important.

And China’s continued purchases are a clear indication that Beijing intends to maintain that position.

Rising Freight Costs Threaten Small Businesses in Developing Economies

0

The Strait of Hormuz is more than a narrow maritime passage connecting the Persian Gulf with the wider world. It is a critical artery of global trade, carrying enormous volumes of oil, gas and other commodities.

Any prolonged disruption along the route can therefore send shockwaves through international markets. But according to the United Nations Trade and Development agency.

The consequences could be especially severe for small businesses, which risk being permanently pushed out of global supply chains even after trade flows eventually recover.

Small and medium-sized enterprises form the backbone of the global economy. They represent around 90% of companies worldwide and provide roughly 70% of jobs. Their importance extends beyond employment: in developing economies, smaller businesses often connect local producers, workers and consumers to international markets.

Yet their relatively limited financial resources make them particularly vulnerable when transportation, energy and compliance costs rise simultaneously. The disparity in trade costs illustrates the problem.

Small firms in developing economies already spend approximately 19.4% of the value of their imports on compliance, compared with 14.7% for larger competitors. This difference may appear modest under normal circumstances, but during a supply-chain crisis, additional costs can quickly become decisive.

A business operating on narrow margins may be unable to absorb delays, customs expenses, insurance increases or rapidly changing freight rates.

Financing creates another structural disadvantage. Smaller businesses face average borrowing costs of about 15.8%, substantially above the 10.3% paid by larger competitors.

When interest rates and transportation expenses rise together, access to working capital becomes critical. A major corporation may be able to finance inventory, absorb temporary losses or negotiate favorable shipping contracts. A small importer may simply run out of cash before conditions improve.

The Strait of Hormuz disruption therefore presents a risk that goes beyond temporary inflation or delayed deliveries. If smaller firms lose reliable access to international suppliers and customers, their absence could become permanent.

Larger companies may capture their market share, establish alternative supply relationships and strengthen their negotiating power with logistics providers. Once these relationships are established, returning to the global supply chain may be considerably harder for displaced businesses.

This creates a potentially damaging feedback loop for developing economies. Small businesses disappear or retreat into domestic markets, reducing competition and limiting export opportunities. Workers can lose jobs, local suppliers can lose customers, and governments can face weaker tax revenues.

Meanwhile, concentrated markets may become less resilient because fewer companies control a greater share of production and distribution. The warning also highlights why supply-chain resilience cannot be measured simply by whether aggregate trade volumes recover.

Headline statistics may eventually show that global commerce has returned to normal, while thousands of smaller firms remain excluded from the recovery.

Governments and international institutions therefore face a broader policy challenge.

Supporting vulnerable businesses through temporary financing, trade facilitation, lower compliance burdens and improved access to alternative logistics routes could help prevent a temporary disruption from becoming a permanent restructuring of global commerce.

The Strait of Hormuz crisis demonstrates that supply-chain resilience is not only about keeping ships moving. It is also about ensuring that the smallest participants in global trade have enough financial and institutional capacity to survive when those ships cannot. If they are pushed out, the economic damage may continue long after the disruption itself has ended.

Adani Airport Raises $1 Billion as Global Investors Bet on $18 Billion Valuation, Shares Rise 5%

0

Shares of Adani Enterprises rose nearly 5% on Wednesday after its airport subsidiary agreed to raise about 98.25 billion rupees ($1 billion) from a group of global and domestic investors, providing fresh capital for one of the conglomerate’s largest infrastructure businesses.

Adani Airport Holdings has entered into a binding agreement with funds managed by Alpha Wave Global, Premji Invest, Temasek and BlackRock to issue new shares in three tranches. The transaction values the airport operator at about $18 billion on a pre-money basis, according to a company statement.

The investors will collectively own about 5.54% of Adani Airport Holdings once the final tranche is completed, with that stage expected by July 2027. The transaction remains subject to customary closing conditions and regulatory approvals.

The fundraising is the latest major capital-raising exercise by Adani Enterprises as the group continues to strengthen its balance sheet and fund expansion across infrastructure businesses. It follows the company’s 150 billion rupee qualified institutional placement in July.

For Adani Airports, the transaction provides capital at a time when India’s aviation market is expanding, and airport operators are increasingly looking beyond aeronautical revenue to generate returns from commercial development around terminals.

Jeet Adani, a non-executive director at Adani Airport Holdings, described the investment as an “important milestone” in building out the airports platform. He said the company plans to continue investing in airport infrastructure, city-side developments and non-aeronautical businesses.

Chief Executive Arun Bansal said the company aims to become the world’s largest airports platform, pointing to rising passenger demand, increasing consumer spending power in India and the growth potential of city-side developments.

The fresh capital will be used to expand and modernize airport infrastructure, accelerate Adani Airport City projects and scale passenger-facing and other non-aeronautical businesses, including ground handling.

The company expects those investments to increase its capacity to serve about 200 million passengers annually.

That expansion has become necessary because the economics of modern airports extend well beyond landing fees and passenger charges. Retail, food and beverage, advertising, parking, logistics, hotels, commercial property and other services can provide additional revenue streams, potentially making airport assets more valuable as passenger volumes increase.

Adani Airport Holdings currently manages eight airports across India and accounts for more than 23% of the country’s passenger traffic, according to the company. The scale gives the business a significant position in a market where air travel demand has continued to create opportunities for capacity expansion and airport modernization.

The $18 billion pre-money valuation also provides an indication of how investors are pricing Adani’s airport ambitions. The participation of Alpha Wave Global, Premji Invest, Temasek and BlackRock-managed funds gives the transaction a broad institutional investor base and provides an external valuation reference for the airport business.

The investment is also significant for Adani Enterprises because airports are long-duration infrastructure assets that require substantial upfront capital but can generate recurring cash flows as passenger volumes and commercial activity grow.

The challenge will be converting that scale into attractive returns. Airport expansion requires heavy spending on terminals, runways, transport links and surrounding infrastructure, while projects such as airport cities can take years to reach full commercial potential. The company will therefore need passenger growth and non-aeronautical revenues to rise sufficiently to justify the capital being deployed.

Adani Airports’ strategy reflects a broader evolution in airport economics, where operators increasingly seek to turn airports into integrated commercial ecosystems rather than treating them solely as transportation facilities. The development of airport cities is central to that approach, allowing operators to capture spending from passengers, businesses and visitors before and after flights.

The new investment could accelerate that transition while giving Adani Airports additional financial capacity to expand its footprint and upgrade existing facilities.

For Adani Enterprises, the fundraising also demonstrates continued access to institutional capital for its infrastructure portfolio. The July qualified institutional placement and the latest airport transaction together point to an effort to mobilize external capital as the group pursues large-scale expansion.

The immediate market reaction suggests investors viewed the airport fundraising positively, with Adani Enterprises shares rising nearly 5% on Wednesday. The longer-term test, however, will be whether the capital raised translates into higher passenger capacity, stronger commercial revenues and sustainable returns on the expanded asset base.

With a targeted capacity of about 200 million passengers a year, Adani Airports is positioning itself for a much larger role in India’s aviation infrastructure. Aviation experts say the company’s ability to monetize that scale through both airport operations and surrounding commercial developments will determine whether the ambitious valuation and growth strategy can be sustained.