Home Blog Page 6

Broadcom’s $42 Billion AI Bet on Anthropic Reshapes Infrastructure Financing

0

Broadcom’s agreement to lend Anthropic up to $42 billion marks a significant new phase in the artificial-intelligence infrastructure race: the companies building AI systems increasingly need not only chips and data centers, but also sophisticated financing structures to pay for them.

According to Anthropic’s IPO prospectus, the financing could support roughly one-third of the AI company’s $125.2 billion commitment to lease tensor processing unit (TPU) computing capacity over five years.

The arrangement places Broadcom in an unusually powerful position because it is simultaneously involved in supplying compute, leasing equipment and financing the infrastructure Anthropic needs. The numbers illustrate the extraordinary capital intensity of frontier AI.

Training and operating increasingly capable models requires enormous amounts of computing power, while demand for inference is also expanding as businesses integrate AI into software, customer service, research and automated workflows.

For companies such as Anthropic, access to computing capacity can therefore become as strategically important as access to capital. Broadcom’s financing helps address that problem.

Instead of Anthropic funding its entire infrastructure expansion through traditional equity or conventional borrowing, part of the spending can be supported through a financing relationship with a critical technology supplier.

The notes can potentially be converted into Anthropic shares, adding another layer to the relationship as the company prepares for a potential public offering. The arrangement also demonstrates how deeply intertwined the AI supply chain has become.

Broadcom works closely with Google on the development of TPUs, the specialized processors that Anthropic plans to use for future computing capacity. Anthropic has said that its expanded partnership with Broadcom and Google will provide access to next-generation TPU capacity beginning in 2027.

That makes Anthropic an increasingly important customer for Broadcom. Reuters reports that Anthropic is expected to become Broadcom’s largest customer in its chip-design business in 2027.

Broadcom, meanwhile, projects substantial growth in AI semiconductor revenue, reflecting how much the company expects demand for specialized AI infrastructure to expand. But the financing also highlights a central question surrounding the current AI boom.

How much of the industry’s extraordinary growth is being supported by genuine end-user demand, and how much depends on increasingly complex financial relationships between suppliers, customers and investors?

Wall Street has increasingly examined what analysts describe as circular financing. Semiconductor companies can provide funding or financial support to AI developers, which then use the capital to purchase computing infrastructure from those same technology ecosystems.

Such arrangements can accelerate deployment and create enormous revenue opportunities, but they can also increase interconnectedness if future AI revenues fail to match infrastructure commitments.  Anthropic’s own filings acknowledge risks.

The company has warned that Broadcom’s dual role as supplier and financier could create potential conflicts involving pricing, hardware availability and access to computing capacity. Certain defaults could also accelerate lease obligations and restrict access to the financing facility.

For the broader technology market, the $42 billion agreement is therefore more than another AI partnership. It is evidence that the next stage of the AI race is becoming a contest of capital structure as much as computational power.

The companies capable of securing chips, energy, data centers and financing at enormous scale may determine how quickly the next generation of AI reaches the market. The question now is whether the revenue generated by that infrastructure will grow quickly enough to justify the commitments being made today.
Two Programmes, One Mission: Building Companies and Capital-Market Leaders [Join]

0

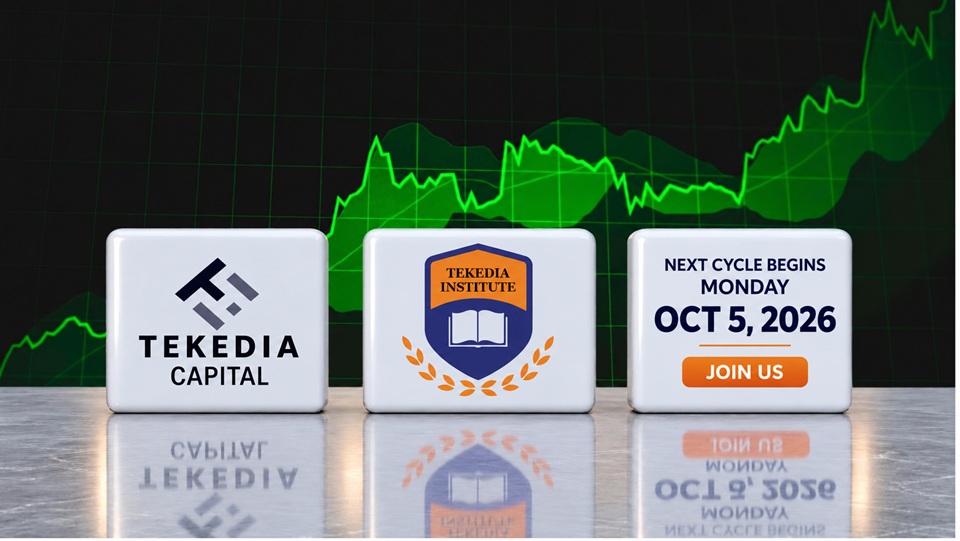
Good People, on Monday, we will begin two important programmes:

  • Tekedia Capital Investment Cycle: Tekedia Capital will open a new investment cycle, presenting 18-20 companies. We hope to support these businesses with capital, knowledge and other resources as they develop solutions capable of improving our world. Learn more and become part of our community.

  • Nigeria Capital Market Masterclass: Tekedia Institute will begin the second edition of the Nigeria Capital Market Masterclass. The programme offers participants opportunities for internships within Nigeria’s capital market. The capital market commands a significant share of global economic activity, and we believe the 2030s will be a defining decade for Nigeria’s capital-market industry.

Through more than 15 practitioner-led modules, participants will gain the knowledge and practical understanding required to operate, innovate and build careers in this expanding sector. Join us and prepare for the future.

Global Markets Steady As Bond Volatility Eases Ahead Of US Jobs Report, Dollar, Yen Rise

0

Global stocks rose on Friday as a sharp sell-off in government bonds and currencies showed signs of easing, while falling oil prices offered some relief to investors ahead of a closely watched U.S. jobs report that could influence expectations for the Federal Reserve’s next interest-rate decision.

The improvement in risk sentiment followed weeks of turbulence across global bond markets, where rising energy prices, persistent inflation concerns and deteriorating public finances have pushed government borrowing costs higher.

In Europe, longer-dated sovereign bonds advanced, although the gains were uneven. Investors favored German debt, widely viewed as a relative safe haven within the euro zone, while bonds issued by more heavily indebted countries such as France and Italy lagged.

Germany’s 10-year government bond yield, the benchmark for the euro zone, fell 10 basis points to around 4.84%. Bond yields move inversely to prices.

France’s 10-year yield was little changed at 4.939%, widening the spread between French and German borrowing costs to more than 150 basis points. That was the largest gap since the euro zone debt crisis in 2011, highlighting growing investor concern about France’s fiscal position.

“I wouldn’t call it a crisis yet, but it looks like it has the potential to be one,” said George Lagarias, chief economist at Forvis Mazars.

“If it goes on for a couple more weeks then we’ll be talking about a crisis in the bond market.”

The widening divergence between Germany and France shows how investors are increasingly differentiating between sovereign borrowers rather than treating European government bonds as a single asset class. Germany’s relative fiscal position has made its debt more attractive as investors seek protection from rising deficits and political and fiscal uncertainty elsewhere.

Oil Retreat Gives Markets Some Breathing Room

The bond-market pressure has intensified in recent weeks as the conflict between the United States, Israel and Iran pushed energy prices higher, threatening to reinforce inflation while adding to pressure on already stretched government finances.

Oil prices, however, moved sharply lower on Friday.

U.S. West Texas Intermediate crude futures fell 3.8% to $89.34 a barrel, while Brent crude declined 2.5% to below $100. European gasoil futures, a key benchmark for diesel prices, dropped about 5% to $1,382.75 a metric ton.

The retreat in energy prices provided some relief to both equity and bond markets as investors focused on signs that supplies from the Middle East were recovering. European countries were also discussing a proposal to release additional diesel stockpiles to ease pressure on fuel markets.

The significance extends beyond the oil market. A sustained increase in energy prices would complicate the inflation outlook by raising transportation, manufacturing, and household costs, potentially limiting the ability of central banks to reduce interest rates. A decline in crude and diesel prices, by contrast, reduces some of that immediate inflationary pressure.

That dynamic has become necessary for the Federal Reserve as investors try to determine whether monetary policy will remain restrictive or become more supportive of economic growth.

Payrolls Become The Next Major Market Test

The next major catalyst was the U.S. employment report for September, due later Friday. Economists were expecting nonfarm payrolls to increase by about 90,000, while the unemployment rate was forecast to remain at 4.1%.

The data could have an immediate impact on expectations for the Federal Reserve’s next move. Markets were pricing only about a 25% probability of another rate increase this month, after two senior policymakers said this week that they wanted more economic data before deciding how to proceed. A rate move in December remained fully priced in.

“With the Fed now myopically focused on inflation and price pressures, a hot wages print could prove particularly influential for US rates, Treasuries and the USD,” said Chris Weston, head of research at Pepperstone.

“Risk assets have so far absorbed the rise in US real yields, and long-end nominal Treasury yields remarkably well. However, a sustained increase in term premium could be far more problematic.”

Against that backdrop, the composition of the employment report has become as important as the headline payroll number. Strong wage growth could reinforce concerns about persistent inflation and push Treasury yields and the dollar higher, while weaker labor-market data could strengthen expectations for easier monetary policy.

European equities advanced, with the pan-European STOXX 600 rising 0.8%. The index was nevertheless heading for a weekly decline of roughly 1%.

U.S. equity futures also pointed to a stronger opening, with Nasdaq 100 futures up 0.7% and S&P 500 futures gaining 0.5%.

Asia was less resilient. MSCI’s broadest index of Asia-Pacific shares outside Japan fell 0.1% on Friday, leaving it down 1.3% for the week. Japan’s Nikkei declined 0.9% on the day but still gained almost 3% over the week.

Mainland Chinese markets remained closed for a public holiday, while Hong Kong’s Hang Seng Index fell 2.7% following its return from a holiday.

Dollar Strengthens As Investors Seek Safety

The turmoil in European sovereign debt markets also appears to have redirected some safe-haven demand toward U.S. Treasuries, the dollar, yen and Swiss franc.

The euro fell to $1.1231, extending losses after declining 0.8% Thursday to reach its lowest level since May 2025.

The U.S. dollar index, which measures the currency against six major peers including the euro and Swiss franc, stood at 102.03, slightly higher on Friday after gaining 0.6% in the previous session to reach its highest level since April 2025. The index was on track for a third consecutive weekly gain of about 1%.

The dollar’s resilience is significant because it comes even as U.S. fiscal concerns remain a major source of volatility in global bond markets. For now, however, the currency is benefiting from its traditional safe-haven role as investors reassess risk across Europe and emerging markets.

The Japanese yen strengthened 0.2% to 157.61 per dollar after data showed underlying inflation in Tokyo accelerated to an annual rate of 2.7% in September. The stronger inflation reading reinforced expectations that the Bank of Japan could raise interest rates further.

Taken together, the moves in bonds, currencies and commodities point to a market still dominated by inflation and fiscal risks rather than a straightforward recovery in risk appetite.

Euro Heads for Fourth Weekly Loss as France’s Fiscal Risks and Fed Outlook Lift Dollar

0

The euro was heading for a fourth consecutive weekly decline against the US dollar on Friday, putting the currency on course for its steepest weekly loss in about four months as concerns over France’s deteriorating fiscal position combined with a more hawkish US interest-rate outlook to weaken demand for the single currency.

The euro fell sharply on Thursday and was broadly stable on Friday as oil prices eased amid discussions over the release of diesel and crude inventories. It was down 0.05% at $1.1240 by 1127 GMT and was on track for a 1.35% decline for the week, its largest weekly fall since mid-May.

The retreat has reversed some of the euro’s earlier strength and illustrates how quickly currency markets can shift when interest-rate expectations, energy prices and sovereign-risk concerns move in the same direction.

The dollar index, which measures the US currency against six major peers, slipped 0.1% to 102.03 on Friday but remained on course for a 1.01% weekly gain, its third consecutive weekly increase.

Higher oil prices have also supported the dollar because investors typically reduce exposure to currencies of major energy importers such as the euro and yen when crude prices rise. Europe and Japan are particularly vulnerable to an energy shock because higher fuel costs can worsen trade balances while simultaneously pushing inflation higher.

France Becomes A Growing Source of Pressure For The Euro

The euro’s weakness is largely tied to concerns about Europe’s fiscal and political outlook, particularly in France. French government bonds have come under heavy selling pressure, pushing the 10-year yield to its highest level since 2002 on Thursday. The spread between French 10-year bonds and benchmark German Bunds, a widely watched measure of the additional risk investors demand to hold French debt, widened beyond 150 basis points on Friday.

That was the largest gap since the euro zone sovereign debt crisis in 2011, highlighting the extent to which concerns over France are being reflected in European bond markets.

The pressure has also begun spreading to other heavily indebted countries, including Italy and Greece, although both have made progress on their fiscal positions.

France’s budget and political uncertainty are weighing heavily on the euro because concerns over government finances can raise borrowing costs, tighten financial conditions and complicate the European Central Bank’s policy decisions.

“Layered on top of worries about low European gas storage, already high energy prices, persistent competition from China, a weakened chancellor in Germany and the risk of hybrid attacks from Russia, the outlook for the euro is clearly on a weakened footing relative to last year,” said Jane Foley, senior forex strategist at Rabobank.

She also pointed to France’s budget and political backdrop as factors weighing on the currency.

The energy question is adding another layer of uncertainty. European Union countries discussed a French proposal on Friday to release diesel reserves following pressure from the United States to help cool surging fuel prices. At the same time, euro zone inflation is expected to rise in the coming months, potentially complicating the ECB’s policy path. Higher energy costs can feed directly into consumer prices while also weakening household purchasing power and economic activity.

That combination puts policymakers in a difficult position: inflation may require tighter monetary conditions even as fiscal concerns and higher borrowing costs place additional pressure on governments and the broader economy.

UBS has taken a more constructive view of the currency at current levels, arguing that France’s fiscal difficulties are unlikely to produce an immediate funding crisis. The bank said a credible fiscal consolidation plan could restore investor confidence and viewed current prices as an opportunity to gradually increase euro exposure.

The contrasting views underpin the uncertainty surrounding the currency. The deterioration in French bond markets has been substantial, but it has not yet established that France faces an imminent sovereign funding crisis.

Fed Expectations Shift As Markets Await US Jobs Data

The euro’s decline has also been reinforced by changing expectations around US monetary policy.

The Federal Reserve raised rates and signaled the possibility of further increases in mid-September, strengthening the dollar by increasing the relative return available on US assets. Fed Chair Kevin Warsh has also reaffirmed the central bank’s independence amid repeated calls from US President Donald Trump for lower borrowing costs.

That policy divergence has made the interest-rate gap between the United States and Europe an important driver of the euro-dollar exchange rate.

However, expectations have shifted again this week after softer US inflation data. Consumer prices rose less than expected in August, while July’s inflation figure was revised lower, prompting traders to reduce bets on another Federal Reserve rate increase later this month.

Two senior Fed policymakers also argued during the week for gathering more economic data before deciding on another move, adding to uncertainty ahead of the latest employment report.

Markets were pricing a 72% probability of the Fed leaving rates unchanged in October, up sharply from 36% a week earlier, according to CME FedWatch.

The US payrolls report therefore became the immediate focus for currency traders. Economists expected job growth to slow in September, while the unemployment rate was forecast to remain at 4.1% for a third consecutive month.

A weaker employment report could reinforce expectations that the Federal Reserve will hold rates steady, potentially limiting the dollar’s recent gains. Stronger labor-market data, however, could revive expectations for tighter policy and provide another source of support for the US currency.

The problem for the euro is that several risks are arriving simultaneously. France’s fiscal position is increasing the premium investors demand to hold its debt, energy costs remain a threat to European inflation, and the region continues to contend with weak competitiveness concerns and geopolitical risks.

The euro’s fourth straight weekly decline therefore represents more than a simple shift in exchange-rate momentum. It shows how fiscal risk in a major euro-zone economy can feed into sovereign bonds and then into the currency, particularly when the US dollar is simultaneously benefiting from relatively higher interest rates and stronger investor demand.

The immediate direction will depend heavily on US employment data and the resulting adjustment in Federal Reserve expectations. Beyond that, however, the euro’s recovery is expected to hinge on France’s ability to restore confidence in its public finances without aggravating the political tensions already weighing on European markets.

What The Lagos Racing Game Trend Means for Nigeria’s Gaming Industry

0

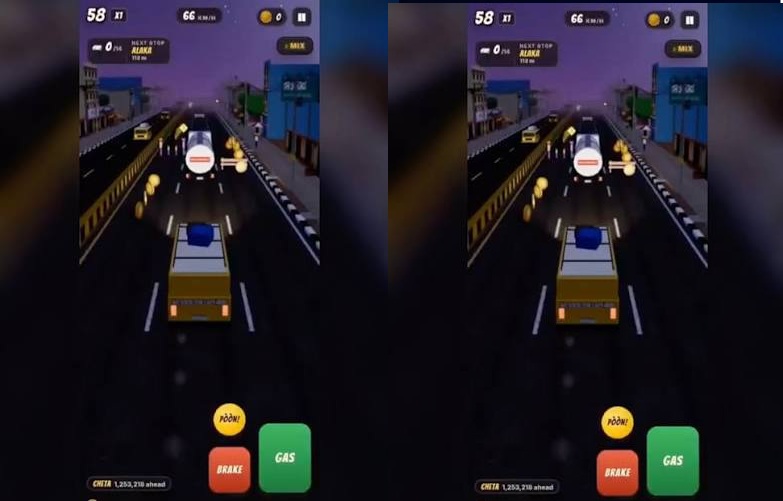
Nigerian Twitter has found a new way to turn the internet into a playground: racing through Lagos. What started with a web-based Lagos racing game created by a game developer has quickly grown into something bigger.

One game appeared, Nigerians noticed, and before long, a small ecosystem of Lagos-themed racing games began appearing across social media. The result is a uniquely Nigerian internet trend where people are not simply watching content—they are actively playing it.

The appeal is easy to understand. Lagos is already one of the most visually recognizable and chaotic cities in Africa. Its streets are crowded, its traffic is legendary, and its daily movement provides endless material for storytelling.

Turning that environment into a racing game transforms familiar experiences into something humorous, competitive and interactive. Instead of racing through fictional cities that could exist anywhere, players are navigating digital versions of places that feel recognizable.

The streets, vehicles and atmosphere can evoke the everyday experience of moving around Lagos, creating a stronger connection between the player and the game.

Lagos Run has been among the games attracting attention, particularly because it can be played directly through the web. That accessibility matters. Players do not necessarily need an expensive gaming console, a powerful computer or a complicated installation process.

A browser can be enough to enter the race. That lowers the barrier to participation and helps explain why these games can spread so quickly on social media. Someone can discover a game through a post, click through, play it, share their experience and challenge friends—all within minutes.

There is also an important cultural element behind the trend. Nigerians have a long history of turning everyday experiences into jokes, memes and online communities. A Lagos racing game takes that instinct one step further by making the city itself part of the entertainment.

The games are also a reminder that African developers do not always need to imitate global gaming franchises to attract attention. Local context can itself become a product.

Lagos has characters, landmarks, traffic patterns, cultural references and stories that can provide raw material for games designed specifically for people who understand the environment.

For developers, the sudden interest could represent something more significant than a temporary Twitter trend. It demonstrates how quickly a culturally relevant idea can generate engagement when it is easy to access and easy to share. It also shows the potential of browser-based gaming as a distribution channel.

Particularly in markets where mobile phones are far more common than traditional gaming hardware. For players, the economics are probably secondary. The immediate attraction is simple: it is fun.

There is something satisfying about seeing a familiar city transformed into a virtual racetrack and competing with friends over who can survive the streets, avoid obstacles and post the better score.

Nigeria’s latest internet craze may eventually disappear as quickly as it arrived. But the experiment is already revealing something important. When developers build around experiences people recognize, social media can become more than a place to discuss culture—it can become the distribution network for the culture itself.

For now, Nigerians are doing what they do best online: turning a simple idea into a movement, one race at a time.