DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog Page 95

Uber Launches Wayve-Powered Robotaxis in London as Britain Accelerates Autonomous Driving Push

0

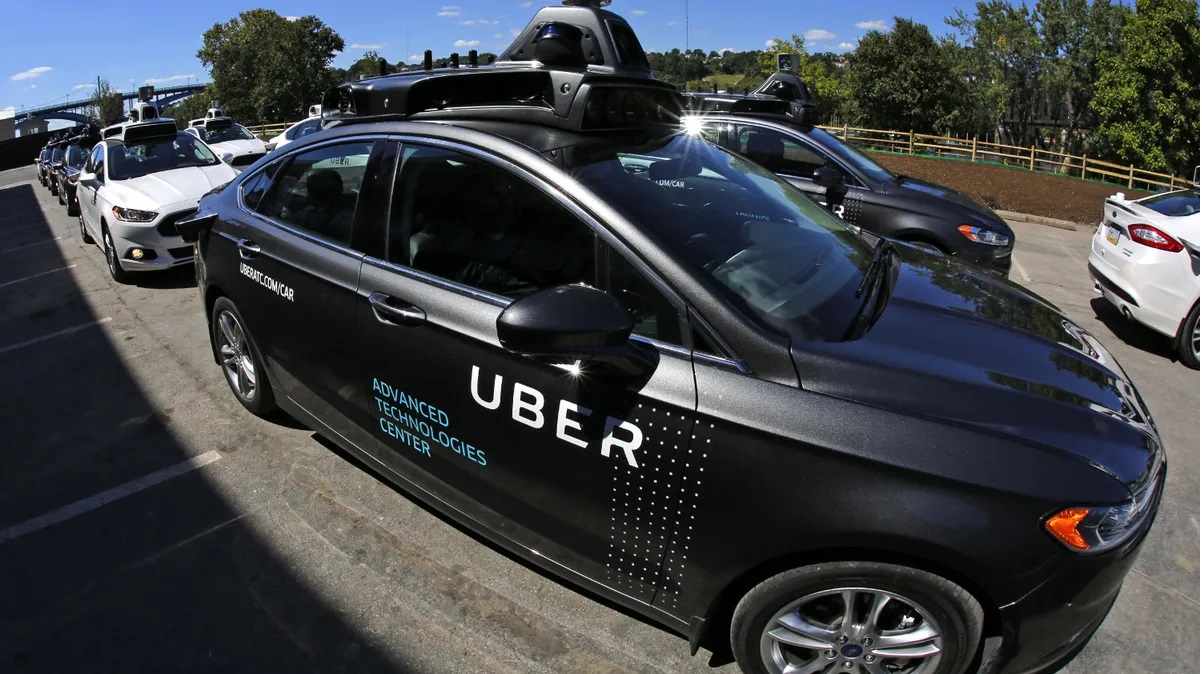
Uber launched autonomous rides in London on Thursday using artificial-intelligence technology developed by British self-driving company Wayve, bringing robotaxis to the British capital as the ride-hailing giant expands its autonomous mobility operations across Europe.

The launch makes London the second European city where Uber offers autonomous rides, following the introduction of robotaxi services in Zagreb.

The initial service will operate with a licensed safety operator in the vehicle to monitor the autonomous system, with fully driverless operations planned for a later stage once regulatory requirements are met, the companies said.

Passengers requesting UberX, Uber Comfort or Uber Electric rides could be matched with a Wayve-powered Ford Mustang Mach-E at no additional charge. Fewer than 20 vehicles will be available when the service launches.

The limited fleet marks an early commercial test of autonomous driving technology in one of Europe’s most complicated urban environments. Uber and Wayve will be able to gather operational data and consumer feedback while regulators assess how the technology performs on London’s roads.

Uber’s Global Head of Autonomous Mobility, Sarfraz Maredia, said the service would help the companies demonstrate the technology’s capabilities to both passengers and policymakers.

The launch would “build credibility with consumers as well as with the government,” Maredia said.

British Transport Secretary Heidi Alexander described the rollout as an important step for the country’s autonomous-vehicle industry.

“This is a major milestone for the future of transport in London, as British innovation brings this technology onto our roads and gives passengers more choice,” Alexander said.

Despite Thursday’s launch, widespread driverless operation in London remains subject to regulatory approval. Transport for London, the city’s transport authority, has yet to authorize fully driverless commercial services, leaving a licensed operator in the vehicle during the initial phase.

That makes the London rollout both a technology demonstration and a test of Britain’s regulatory framework for autonomous vehicles. The companies will need to show that the system can operate safely across London’s dense traffic, complex road layouts, cyclists, pedestrians and frequently changing weather conditions before removing the human safety operator.

Wayve’s autonomous driving system, known as the Wayve AI Driver, is designed to learn from driving experience in a manner similar to a human driver. The company said the system can adapt to new roads, vehicles, weather conditions, and cities rather than relying solely on detailed pre-programmed maps and fixed driving rules.

That approach is central to Wayve’s technology strategy and could give it an advantage as autonomous vehicle companies seek to expand beyond tightly controlled operating zones.

Alex Kendall, Wayve’s chief executive and co-founder, said London was an appropriate location for the company’s first public deployment.

“We’re proud to introduce the Wayve AI Driver to the public for the first time right here in London, our home city and one of the most complex driving environments in the world,” Kendall said.

The rollout builds on Uber’s partnership with Wayve, which began in 2024 and included an investment by the ride-hailing company. The agreement was designed to support the deployment of Wayve-powered autonomous vehicles across multiple markets.

For Uber, autonomous vehicles offer a potential way to expand ride capacity while reducing the industry’s dependence on human drivers over the longer term. Rather than developing its own autonomous-driving system, Uber has pursued partnerships with technology companies and vehicle manufacturers, allowing it to focus on its ride-hailing platform and customer network.

The London launch also comes as competition in autonomous mobility intensifies. Companies across the industry are moving from testing self-driving technology to limited commercial deployments, making regulatory approval, safety performance and consumer acceptance important competitive factors.

Wayve’s London deployment is notable because the company is seeking to demonstrate that its AI-based approach can generalize across different driving environments. Successfully handling London’s unusually complex streets could provide an important validation of the technology as Wayve looks to expand internationally.

For now, the small fleet and continued presence of safety operators mean the service remains far from a fully autonomous transportation network. But the launch marks a transition from testing the technology to putting it directly in front of paying passengers. The next test will hinge on Wayve and Uber’s ability to demonstrate enough safety and reliability to convince regulators to remove the human operator and allow the service to scale beyond a handful of vehicles.
EUR/JPY, Bitcoin and Nvidia: Three Signals Shaping the Market

0

Global markets are entering September with three developments demanding attention: Arthur Hayes’ warning that a falling EUR/JPY could become an early liquidity signal.

Bitcoin’s technical struggle around its neckline with $71,000 in focus, and a major Nvidia insider filing that could test investor confidence in the artificial-intelligence trade.

Hayes, the BitMEX co-founder and current Maelstrom chief investment officer, argues that traders should pay close attention to the euro-yen exchange rate because it can provide an early indication of stress moving through global funding markets.

In his latest analysis, Hayes identified EUR/JPY as his macro “North Star,” arguing that a sharp decline could reveal growing pressure in European financial markets and eventually force additional liquidity support.

The logic is important for Bitcoin. A falling EUR/JPY can reflect changing interest-rate expectations, unwinding carry trades and rising demand for safer funding conditions. Hayes’ thesis is that if funding stress becomes severe enough, central banks—particularly the Federal Reserve—could eventually respond with additional liquidity measures.

Such an environment could become supportive for scarce assets such as Bitcoin, even if the initial market reaction is risk-off. Hayes has suggested EUR/JPY could eventually fall substantially from current levels, making the currency pair a potentially important warning indicator for crypto traders.

Bitcoin itself is currently caught between bullish momentum and a renewed technical test.

The cryptocurrency recently broke above the $71,000 area during its broader recovery, but analysts are now watching whether it can reclaim and hold important technical levels after losing an ascending neckline.

One technical setup identifies $71,000 as a potential downside target if the neckline retest fails. Conversely, a sustained recovery above the neckline would invalidate much of the bearish setup.

The broader chart structure remains more constructive than it was earlier in the year. Reuters noted that Bitcoin’s recent rally pushed it above several major moving averages and broke a sequence of lower highs associated with the previous bearish trend.

However, maintaining levels above roughly $71,781 remains important. A failure there could reopen lower support zones, while a stronger breakout could eventually expose significantly higher resistance.

While crypto traders monitor liquidity and technical levels, Nvidia investors are confronting a different kind of signal: insider selling. Nvidia director Mark Stevens has filed notice relating to the sale of five million Class A shares valued at approximately $1.09 billion.

The filing follows additional disposals this year, bringing the value of his potential and completed sales substantially higher. Yet the market has not interpreted the filing as an immediate bearish signal.

Nvidia shares recently climbed as investors continued to focus on the company’s powerful AI growth, while its acquisition of Hugging Face has reinforced expectations that Nvidia wants to deepen its position across the AI software ecosystem.

Nvidia officially disclosed the acquisition agreement in a September 2 filing. The three stories ultimately point to the same underlying theme: markets are becoming increasingly sensitive to liquidity, positioning and confidence.

EUR/JPY may provide an early macro warning, Bitcoin’s neckline could determine whether its recovery extends or reverses, and Nvidia’s insider activity offers a reminder that even the strongest AI trade can encounter profit-taking.

For investors, the message is not that any single indicator guarantees the next move. Instead, the interaction between currencies, liquidity, technical momentum and equity positioning may determine whether September becomes another leg higher—or the beginning of a broader market repricing.

Yen Surges as BOJ Rate-Hike Bets Intensify, Intervention Fears Return

0

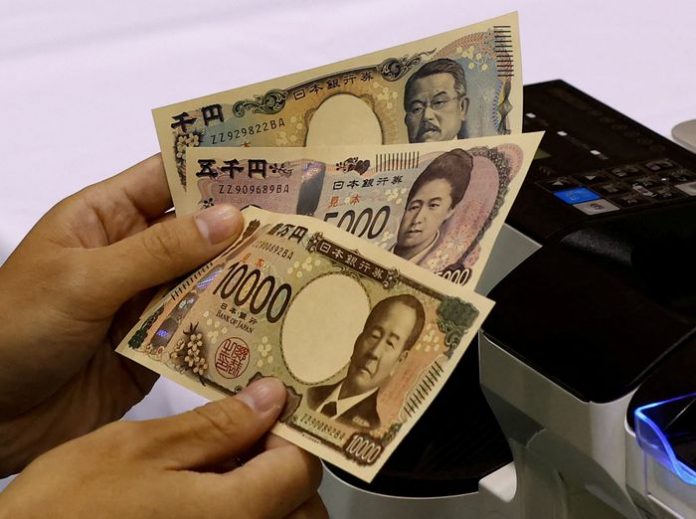
The Japanese yen surged to a one-month high against the U.S. dollar on Thursday as traders increased bets on further Bank of Japan interest-rate hikes and weighed the possibility that Tokyo could intervene again to support the currency.

The yen climbed more than 1% against the dollar, reaching ¥156.15, its strongest level since Aug. 3, according to LSEG data. It was trading around ¥156.40 per dollar at 6:20 a.m. ET and also strengthened against the euro and British pound.

The move marks a sharp reversal from earlier in the week, when the yen breached the psychologically important ¥160-per-dollar threshold. That level has become a key focus for markets because sustained weakness beyond it could increase pressure on Japanese authorities to act.

Atsushi Mimura, Japan’s vice finance minister for international affairs, said Thursday that authorities were “neither satisfied nor reassured” by recent currency moves and remained “on a state of heightened alert,” according to Reuters.

His comments bolstered the perception that Tokyo is closely monitoring the yen and could respond if movements become excessively rapid or disorderly.

Intervention or Rate-Hike Repricing?

Thursday’s rally followed a similar roughly 1% jump in the yen on Wednesday, prompting speculation that Japanese authorities might have intervened in the foreign-exchange market.

Japan has already demonstrated its willingness to deploy substantial resources to support the currency. The Finance Ministry said the country spent a record ¥15.4 trillion, equivalent to about $98 billion, on yen-buying intervention between July 30 and Aug. 26.

The United States also confirmed its participation in a coordinated effort at the end of July, using foreign-currency holdings to purchase yen. Washington has not disclosed the exact amount, although a Reuters photograph of U.S. Treasury Secretary Scott Bessent’s July 31 notepad appeared to reference a plan to buy between $5 billion and $10 billion of yen.

Bessent said Monday that he expected the Japanese government and BOJ to take measures that would strengthen the yen. He has also privately urged Japanese officials to provide clearer communication about the country’s interest-rate trajectory, according to local media reports.

Yet analysts remain divided over whether the latest yen surge represents another intervention.

Takuji Okubo, chief economist at Japan Macro Advisors, said it was “possible” that Thursday’s move reflected intervention, but argued that the more likely explanation was a market reassessment of the BOJ’s policy outlook following recent comments from Governor Kazuo Ueda.

“I do not think [the Ministry of Finance] has done this kind of small stealth intervention in recent history,” Okubo said. “So it is probably just a reaction to BOJ Governor Ueda’s comment cementing the high likelihood of a BOJ rate hike in September.”

ING’s global head of markets, Chris Turner, also questioned whether Wednesday’s move was intervention, pointing to the absence of significant disruption in electronic foreign-exchange matching systems at the time.

But a sustained appreciation driven by monetary policy would be fundamentally different from a temporary move engineered by government purchases of yen.

The BOJ’s next policy meeting is scheduled for Sept. 18, and markets are increasingly pricing the possibility of another rate increase.

BOJ board member Hajime Takata said Wednesday that the central bank should raise rates “nimbly” in response to rising inflation, suggesting policymakers could move faster or make larger adjustments than the roughly semiannual pace seen recently.

Ueda also left the door open to higher rates in comments on Tuesday.

The BOJ’s dilemma is becoming more acute. A weak yen raises the cost of imported energy, food and other goods, potentially keeping inflation elevated. A stronger currency, by contrast, can ease imported inflation but could weigh on exporters and economic activity. The prospect of higher Japanese rates is therefore becoming an increasingly powerful force in the foreign-exchange market because it narrows the interest-rate differential between Japan and the United States.

For years, the yen was heavily used to finance so-called carry trades, in which investors borrowed cheaply in Japan and invested in higher-yielding assets overseas. As Japanese rates rise and the potential return from holding dollars declines relative to the cost of funding in yen, some of those positions become less attractive and can be unwound, creating additional demand for the Japanese currency.

Yen Weakness Is Also A Treasury-Market Issue

The implications extend well beyond Japan’s currency market. Japanese investors are the largest foreign holders of U.S. Treasury securities, with roughly $1.1 trillion of U.S. government debt on their books as of June, according to the U.S. Treasury.

Analysts say a prolonged period of yen weakness could encourage Japanese investors to reduce overseas holdings or increase currency hedging, potentially affecting demand for U.S. government debt. Conversely, a stronger yen could make foreign assets more expensive for Japanese investors in yen terms and alter the attractiveness of U.S. Treasury investments.

That makes the yen an important transmission channel between Japanese monetary policy and global bond markets. The issue is particularly significant while global government bond yields are already elevated. Investors are assessing the combined impact of inflation, large fiscal deficits, heavy government borrowing and divergent central-bank policies.

Japanese government bond yields eased Thursday following a solid auction of 30-year debt, offering some relief after a sharp sell-off in longer-dated bonds.

Japan’s bond market has faced pressure as investors assess the government’s fiscal position and the scale of spending expected under its 2027 budget. Higher long-term yields can increase borrowing costs for the Japanese government while also making domestic bonds more attractive relative to foreign assets.

The interaction between currency, interest rates and government bonds is therefore becoming more relevant. Economists note that if the BOJ raises rates and Japanese bond yields continue climbing, domestic investors may have greater incentives to keep capital at home. That could support the yen while potentially reducing Japanese demand for overseas bonds, including U.S. Treasuries.

Deutsche Bank analysts said markets were also watching the possibility of intervention during thin trading conditions around Japan’s “Silver Week” holidays, which could amplify currency movements.

Fed Policy Limits The Yen’s Upside

The yen’s rally nevertheless faces an important counterforce: U.S. interest rates. Markets have recently increased expectations for another Federal Reserve rate hike this month following hawkish comments from Fed Chair Kevin Warsh. Higher U.S. rates would preserve a substantial yield advantage for dollar-denominated assets, limiting how far the yen can strengthen without a more decisive shift from the BOJ.

Turner said a sustained yen recovery would probably require a significantly more hawkish BOJ as well as new measures designed to encourage domestic investment in Japan.

The result is a three-way contest between monetary policy, government intervention and capital flows.

Tokyo can intervene directly in foreign-exchange markets, but intervention alone is unlikely to produce a durable change in the yen’s underlying trend if the interest-rate differential with the United States remains wide. A credible BOJ tightening cycle, meanwhile, could strengthen the currency more sustainably by changing the economic incentives behind global capital flows.

For investors, the ¥160 threshold may therefore remain less important than what happens after it, according to economic experts. They believe that if the yen continues strengthening toward ¥155 and below without intervention, it would suggest that expectations of higher Japanese rates are increasingly driving the market. If the currency repeatedly approaches ¥160 and then experiences abrupt rallies, speculation about official intervention is likely to remain intense.

The Sept. 18 BOJ meeting has consequently become a critical event for global markets, with the yen, Japanese government bonds and potentially U.S. Treasuries all exposed to the central bank’s next move.

A Fractured Global Economy Meets a Global Bond Rout

0

The global economy is entering a more complicated phase, where geopolitical fragmentation and financial-market stress are increasingly reinforcing one another.

This week offered a stark demonstration of that reality as divisions among the world’s largest economies became visible at a G20 finance meeting while government bond markets simultaneously came under intense pressure across major economies.

The US-hosted G20 finance meeting ended without a joint communiqué, highlighting the difficulty of achieving consensus among countries facing increasingly different economic and strategic priorities.

China rejected proposed language concerning “non-market policies,” reflecting longstanding disagreements over state intervention, industrial policy and the role of government in economic activity.

European objections also prevented Russia’s finance minister from appearing in the traditional group photograph, underscoring how geopolitical tensions continue to shape even forums designed for economic cooperation.

The significance extends beyond diplomatic symbolism. The G20 was established in part to provide a platform where major economies could coordinate during periods of financial instability.

Its inability to produce a unified statement suggests that the international system has become more fragmented precisely when coordinated responses may be most necessary.

At the same time, bond markets delivered another warning signal. UK long-term borrowing costs climbed to a 28-year high, while benchmark government bond yields in the United States and Germany reached multi-year highs.

Japan’s 10-year yield moved above 3% for the first time since 1996. The simultaneous rise in borrowing costs across these major economies suggests that the pressure is not isolated to one country’s fiscal position or monetary policy.

Higher government bond yields matter because they represent the cost of financing for states and influence borrowing conditions throughout the economy.

When yields rise sharply, governments face larger interest expenses, while households and businesses can also encounter higher borrowing costs. For highly indebted economies, sustained increases can create difficult fiscal choices between spending, taxation and debt management.

The Japanese move is particularly important because Japan spent decades operating with exceptionally low interest rates and subdued bond yields. A sustained transition toward higher yields could therefore represent a structural change in global capital markets.

Japanese investors have historically played an important role in international bond markets, and changing domestic returns could influence where capital is allocated globally. The US and Germany face different economic circumstances.

But rising yields in both markets point toward a broader repricing of sovereign debt. Investors may be demanding greater compensation for inflation risks, fiscal deterioration, economic uncertainty or the prospect that interest rates will remain elevated for longer than previously expected.

This creates an uncomfortable feedback loop. Geopolitical fragmentation can increase uncertainty and encourage governments to pursue strategic industrial policies, defense spending and supply-chain restructuring.

Those policies can require greater public expenditure, potentially adding to fiscal pressures. At the same time, higher bond yields make financing that expenditure more expensive. For financial markets, the combination is particularly important.

Equities, cryptocurrencies and other risk assets are sensitive to changes in liquidity and interest rates. A sustained bond-market selloff can therefore tighten financial conditions even without a conventional recession.

The deeper message from this week is that the global economy is not merely slowing or accelerating in a conventional cycle. It is being reorganized. Political rivalry, fiscal pressures, changing monetary regimes and shifting capital flows are converging at the same time.

The absence of G20 consensus and the simultaneous bond-market rout illustrate the same underlying problem: the institutions and assumptions that supported global economic coordination are under increasing strain.

For investors, policymakers and businesses, that means volatility may become less of an exception and more of a defining feature of the new global economic landscape.

Bhutan Sells 400 BTC Worth $30.62 Million as Bitcoin Reserves Decline

0

Bhutan’s latest Bitcoin transfer is putting renewed attention on one of the most unusual sovereign crypto stories in the world.

The Royal Government of Bhutan has reportedly moved another 400 BTC, worth roughly $30.62 million, from wallets associated with Druk Holding, according to blockchain intelligence platform Arkham.

The transaction is more than a routine wallet movement. It adds another chapter to Bhutan’s gradual decision to monetize a Bitcoin reserve that once became extraordinarily large relative to the country’s economy.

Bhutan’s Bitcoin strategy began quietly through state-backed mining, taking advantage of the country’s abundant hydropower resources. Rather than relying entirely on conventional foreign-exchange reserves.

Bhutan effectively converted surplus renewable electricity into Bitcoin. That strategy became increasingly significant as Bitcoin appreciated and the country accumulated thousands of coins. At its peak in late 2024, Bhutan was estimated to hold around 13,000 BTC.

At Bitcoin’s higher valuations, that stash was worth more than $1.4 billion—an extraordinary figure for a small Himalayan economy. The reserve was reportedly equivalent to more than 40% of Bhutan’s gross domestic product.

Illustrating just how consequential the digital asset had become to the country’s balance sheet. But the strategy has increasingly shifted from accumulation to realization. Throughout 2026, Bhutan has reportedly been selling Bitcoin in relatively modest increments.

With transactions often structured in $5 million to $10 million clips through over-the-counter desks. The approach matters because OTC transactions can allow a large holder to dispose of substantial amounts without immediately flooding public exchange order books.

For a sovereign seller, that can reduce visible market impact while converting digital assets into conventional liquidity. The latest 400 BTC transfer therefore fits a broader pattern rather than representing an isolated event.

At roughly $30.62 million, the transaction is large enough to attract attention but still consistent with the measured sales strategy that Bhutan has followed this year.

Arkham’s more consequential observation concerns the potential endgame. If Bhutan continues selling at approximately $50 million per month, its sovereign Bitcoin holdings could potentially be exhausted by the end of September.

That projection, if the current pace persists, would mark a remarkable transformation from one of the world’s most notable government Bitcoin holders into a state with little or no Bitcoin exposure.

Bhutan’s selling is important for a reason beyond the absolute size of the transactions. Sovereign Bitcoin holdings are closely watched because governments are generally considered long-term holders rather than short-term market participants.

When a government begins systematically reducing its position, traders may interpret the activity as a signal about liquidity needs, portfolio management or changing attitudes toward Bitcoin.

However, Bhutan’s situation should not automatically be interpreted as a rejection of Bitcoin. The country’s original mining strategy demonstrated a willingness to embrace the asset at a national level.

Selling can simply represent portfolio monetization: transforming an exceptionally successful digital-asset position into cash or funding other economic priorities.

The bigger story is therefore not merely that Bhutan is selling 400 BTC. It is that a country that once accumulated Bitcoin through renewable-energy infrastructure is now methodically unwinding a reserve that became enormous relative to its economy.

If the current pace continues, September could represent the final stage of Bhutan’s sovereign Bitcoin experiment—or simply the end of one chapter before a new strategy begins.