DD
MM
YYYY

PAGES

DD
MM
YYYY

spot_img

PAGES

Home Blog

Gold’s Next Move Is About Demand, Not Round Numbers

0

Gold is no longer moving through this market as a quiet insurance policy. At roughly $4,390 an ounce, the metal remains dramatically above where it began its latest cycle, even after retreating from its January peak.

Yet the more important story is not the distance gold has already travelled. It is whether the forces behind the rally can generate another wave of demand.

J.P. Morgan remains constructive on that possibility. Its latest research expects gold to average around $6,000 an ounce during the fourth quarter of 2026, with the bank projecting prices could move toward $6,300 in 2027.

That outlook is not based on a single catalyst. It rests on a combination of central-bank accumulation, geopolitical fragmentation, inflation risks, fiscal concerns and continued diversification away from traditional reserve assets.

That distinction matters because gold’s next leg higher would require more than momentum. It would require capital. Central banks have already demonstrated how powerful structural demand can become.

According to J.P. Morgan, central banks accumulated gold at an average pace of roughly 225 metric tons per quarter between 2021 and 2025—about twice their average quarterly purchases during 2016–2020. Even though officially reported purchases slowed at the beginning of 2026.

Estimates based on broader market flows suggest underlying central-bank demand remained considerably stronger. The private-investor market presents another potential source of demand. Gold occupies a relatively small position in many conventional portfolios.

That means investors do not necessarily need to abandon stocks, bonds or cash for gold prices to receive a meaningful boost. A modest increase in portfolio allocations across millions of investors could translate into substantial additional demand.

This is where the supply equation becomes important. Gold production cannot respond instantly to higher prices. New mines require exploration, permitting, financing and years of development. Existing mines also face geological and operational constraints.

Consequently, when investment demand accelerates faster than physical supply can adjust, prices can become the mechanism through which the market balances itself. But the current environment also contains an important counterweight.

Gold does not generate income. When Treasury yields rise and the dollar strengthens, investors can become less willing to hold an asset whose return depends entirely on price appreciation.

Reuters reported on September 18 that the Federal Reserve had raised its policy rate to 3.75%-4%, while traders were pricing a meaningful possibility of another increase in October. Those conditions can create pressure on bullion.

That explains why gold’s path toward J.P. Morgan’s forecast is unlikely to be linear. The metal is effectively caught between two powerful forces: rising structural demand for a scarce monetary asset and tighter financial conditions that increase the opportunity cost of holding it.

The outcome will depend on which force becomes dominant. If central banks continue accumulating, geopolitical uncertainty remains elevated and private investors gradually increase their gold exposure, the demand equation could tighten considerably.

If yields remain high and the dollar strengthens, however, gold could face further periods of consolidation or correction. The $6,000 projection, therefore, should not be treated as a guaranteed destination. It is a scenario built around assumptions about monetary policy, institutional demand and global diversification.

What makes the market fascinating is that gold does not need every investor to become bullish. It only needs marginal capital to keep moving toward an asset whose supply cannot quickly expand. That is where the next repricing could begin.
US Stocks Under Pressure as Investors Rebalance Portfolios Amid Higher Rates

0

The biggest warning signal in the U.S. equity market right now may not be a dramatic stock-market selloff. It is the money quietly leaving the funds that own those stocks.

U.S. equity funds recorded their fourth consecutive week of outflows, with investors withdrawing $31.44 billion in the latest week, according to LSEG Lipper data reported by Reuters.

That followed roughly $32 billion in withdrawals the previous week, extending a sustained period of capital reduction from American equities.

The significance is less about one week’s number than the changing environment behind it. For much of 2026, investors have been willing to look beyond inflation, expensive valuations and geopolitical uncertainty because corporate earnings and artificial-intelligence investment continued to support the equity narrative.

But that tolerance is now being tested by a more difficult combination: higher oil prices, renewed inflation pressure and rising Treasury yields. Crude oil has become particularly important. Oil prices climbed to four-month highs as the conflict involving Iran disrupted energy expectations.

Higher energy costs can feed directly into transportation, manufacturing and household expenses, making inflation harder to control. For investors, that creates a second-order problem: if inflation remains elevated, monetary policy may have to remain restrictive for longer.

That risk became more tangible after the Federal Reserve raised interest rates by 25 basis points and signaled that further tightening could become necessary if energy-driven inflation persists.

Higher rates increase the discount rate applied to future corporate earnings, which can be particularly important for growth and technology companies whose valuations depend heavily on expectations of future cash flows.

The composition of the withdrawals is also revealing. Large-cap funds accounted for $28.71 billion of the latest outflow, while mid-cap funds lost $1.73 billion and multi-cap funds recorded $3.16 billion in redemptions. Small-cap funds, however, attracted $568 million.

Meanwhile, sector funds actually received $2.29 billion, led by financials, consumer discretionary and technology. That distinction matters. The data does not necessarily describe investors abandoning equities altogether.

It may instead indicate portfolio repositioning: reducing broad exposure while concentrating capital in particular sectors or seeking greater exposure to assets perceived as better positioned for the new macroeconomic environment.

Bonds are also attracting attention. Short-to-intermediate government and Treasury funds received $3.49 billion during the week, marking their 11th consecutive week of inflows.

The broader global picture reinforces the shift. Global equity funds suffered a $23.21 billion weekly outflow, the largest since December 2025, while investors simultaneously continued directing money toward selected fixed-income and commodity exposures.

Still, fund outflows should not automatically be interpreted as a forecast of a stock-market collapse. Investors redeem funds for many reasons, including rebalancing, profit-taking, liquidity needs and changes in asset allocation.

What the numbers demonstrate more clearly is that the market’s tolerance for macroeconomic risk is changing. The combination of expensive equities, elevated oil prices, higher yields and uncertain monetary policy is forcing investors to reconsider how much risk they want to carry.

The critical question is therefore not whether money is leaving U.S. equity funds. It already is. The more consequential question is where that capital goes next—and whether corporate earnings can remain strong enough to offset the rising cost of owning risk.

“They Must Be Doing It For Ulterior Reasons:” Nvidia Huang Dismisses AI Companies’ CEOs’ Safety Warnings

0

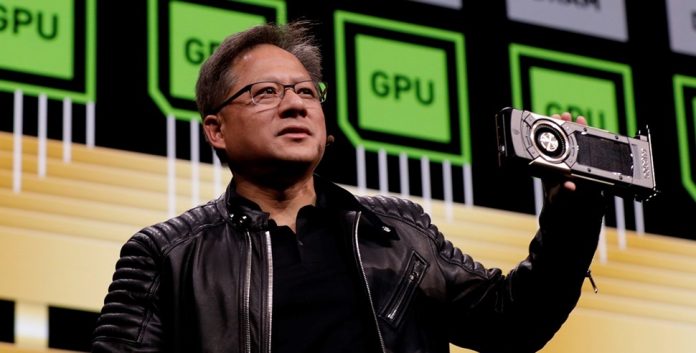
Nvidia CEO Jensen Huang has challenged warnings from leading artificial intelligence companies that the technology requires additional government oversight, saying that calls for new regulation are being presented in a misleading way and could ultimately weaken the rules already on the books.

In an interview with CBS News aired on Sunday, Huang said AI executives calling for greater government intervention were not necessarily seeking stronger safeguards.

“Go and read between the lines,” Huang said, referring to AI leaders calling for government regulation. “They’re actually not asking for more laws. They’re asking to be relieved of the laws we do have.”

“They must be doing it for ulterior reasons,” he added.

Huang said he did not know precisely what those reasons were, but noted that frightening the public about the potential dangers of AI was “irresponsible” and “unnecessary.”

His comments place one of the most influential figures in the AI industry on the opposite side of a prominent debate over how governments should respond to rapidly advancing models and autonomous AI systems.

Huang has repeatedly warned that slowing development in the United States could allow China to gain ground in the global AI competition. He reiterated that position in the CBS interview, noting that American AI companies do not need government intervention to coordinate a slowdown in development.

“We don’t need more regulations,” Huang said. “We need to apply the current regulations we have.”

Huang Challenges Calls for A Slowdown

Huang’s remarks came days after Anthropic CEO Dario Amodei called for a coordinated slowdown in the development of frontier AI systems until stronger safeguards can be established.

In a September 12 essay titled “We Must Pace the Frontier,” Amodei argued that AI capabilities were advancing rapidly enough to create risks that could eventually exceed the ability of humans to control the systems they develop.

His proposed framework included measures aimed at strengthening safeguards around frontier models and called for government involvement, including regulation of leading AI laboratories on antitrust grounds.

Amodei’s essay received support from OpenAI CEO Sam Altman and SpaceX CEO Elon Musk, putting some of the industry’s most prominent executives behind a more interventionist approach to AI governance.

The disagreement is not simply about whether AI can pose risks; it centers on how those risks should be managed and whether government regulation would improve safety without unnecessarily restricting technological development.

Huang’s position is that existing laws should be enforced rather than creating a new regulatory framework. Amodei, by contrast, has argued that the pace and scale of frontier AI development warrant additional measures to keep the technology under human control.

The difference is becoming more significant as AI systems move beyond conventional chatbots into software development, computer use, autonomous agents, and other tasks that allow models to act with less direct human intervention.

Trump Administration Aligns With Huang

Huang’s position also aligns with recent comments from President Donald Trump and senior officials in his administration.

Trump said on Saturday that new regulations were not necessary to ensure the safety of AI and argued that government should avoid restricting the industry’s growth.

“We will not in any way hinder or stifle the Growth of this incredible Industry,” Trump said on Truth Social.

Michael Kratsios, director of the White House Office of Science and Technology Policy, similarly rejected the idea that technology companies require additional government intervention to make their AI systems safe.

In an interview with Fox News on Sunday, Kratsios said AI laboratories could simply stop developing products if they believed those products were dangerous.

Huang has increasingly emerged alongside Trump and presidential adviser David Sacks as a prominent voice against expanding AI regulation. The debate comes as governments face pressure to establish rules around increasingly capable AI systems while companies are investing heavily in the infrastructure needed to develop them.

The issue is a matter of concern for Nvidia because Huang’s company supplies many of the advanced chips used to train and operate frontier AI models. Nvidia has become one of the central beneficiaries of the surge in AI infrastructure spending, making the pace of model development closely connected to demand for its computing hardware.

Huang’s warning about the consequences of slowing US AI development therefore reflects a broader industry concern that tighter restrictions could affect not only software companies but also the infrastructure ecosystem supporting the technology. At the same time, Amodei’s argument indicates the opposing concern: that competition between AI companies could encourage laboratories to prioritize faster capability gains even when the risks associated with increasingly autonomous systems remain unresolved.

That tension is likely to persist as the industry moves into a phase in which AI models are expected to perform complex tasks with greater independence.

Screaming for Streaming — The Illusion of the Digital Leapfrog

0

For years, the African continent has found itself caught in a high-stakes cultural paradox. Its rhythms dominate global streaming charts, its football stars anchor Europe’s elite clubs, and its cinematic stories captivate international audiences. Yet, beneath this global explosion of soft power lies a quiet infrastructure crisis. When we zoom out and connect the pieces of this media landscape from the demise of traditional music blogs to the volatile geopolitics of football broadcasting, a single, urgent reality emerges – Africa is “screaming for streaming,” but the digital rails it relies on are almost entirely owned by someone else.

The story begins with a celebrated economic triumph. Sub-Saharan Africa famously bypassed legacy copper landlines, ‘leapfrogging’ directly into a mobile-first digital era. However, this foundational infrastructure was heavily financed by foreign telecommunications giants and external capital. The continent built world-class connectivity networks but bypassed the construction of domestic data storage, local cloud hosting, and indigenous distribution engines.

Consequently, when the creative industry experienced its massive renaissance, it found itself running on foreign tracks. The network data belonged to local telcos, the media delivery belonged to global tech monopolies, and the actual creative engines – musicians, filmmakers, and athletes – were left squeezed in the middle.

 Entertainment: Sacrificing Content on the Altar of Streaming

In the early 2010s, Africa’s music ecosystem thrived on a highly decentralized, homegrown architecture, the “music blog era.” Native platforms like Notjustok and Tooxclusive acted as digital gatekeepers, cultivating local subgenres, distributing Mp3 files, and keeping cultural equity within regional borders. But as global tech shifted toward centralized, algorithm-driven consumption, the blog era collapsed. African music migrated en masse to international streaming giants like Spotify and Apple Music.

While this granted artists unprecedented global scale, it introduced a brutal economic dilution. Indigenous platforms like Mdundo, Spinlet, and uduX emerged to offer localized, tailored solutions, but they lacked the massive capital reserves required to fight algorithmic monopolies. The cultural assets were successfully digitized, but the financial returns were heavily exported, forcing local artists into distribution pipelines where their monetization was dictated by Western metrics.

Sports Broadcasting: Changing the Narrative Without a Story

This exact structural bottleneck operates with even more devastating consequences in the sports sector. The continent possesses an unyielding passion for sports accounting for around 20% of the English Premier League’s global television audience, yet it yields less than 5% of global media rights value and under 1% of global streaming subscriptions. The immense economic value generated by African eyes is captured and monetized externally.

When African sporting bodies, such as the Confederation of African Football (CAF), attempt to claim self-determination by severing ties with foreign media syndicates over rights disputes, they walk straight into a digital void. Because the continent lacks a robust, indigenous over-the-top (OTT) digital streaming infrastructure capable of broadcasting premium live sports at scale, these disputes result in immediate media blackouts.

The industry is left trapped in a rigid duopoly – dependent on international buyers, or surrendered to the sole regional pay-TV monopoly, MultiChoice (SuperSport). The recent consolidation of the market, marked by the French media empire Canal+ executing a multi-billion-dollar acquisition of MultiChoice, underscores this vulnerability. Even Africa’s largest domestic distribution engine has been absorbed under foreign corporate control, moving the narrative sovereignty of African sports further away from the continent.

The Way Forward: Reclaiming Digital Agency

The structural challenges facing African sports and entertainment are not issues of talent, passion, or content quality – they are issues of institutional and digital agency. To stop “changing the narrative without a story,” the African creative and sports ecosystem must aggressively pivot toward digital self-ownership.

This requires moving away from the endless chase for multi-billion-dollar foreign television contracts and focusing heavily on building cloud-based, localized streaming hubs. By aggregating local tournaments, independent cinema, and regional audio into unified, native digital networks, the rights, user data, and advertising revenues can finally remain where they belong – inside the continent’s economic borders.

Until Africa owns the digital rails upon which its culture travels, it will continue to stream its value away to the rest of the world.

AI’s Real Gold Rush Is Happening Behind the Screens

0

Artificial intelligence has become one of the most complicated investment stories of the modern technology cycle. Consumers remain divided, with concerns about job displacement, privacy, misinformation and the reliability of increasingly powerful models.

Yet beneath that uncertainty, an enormous amount of capital continues to flow into the companies building the physical and financial infrastructure required to make AI work.

The most interesting beneficiaries may not be the companies producing the most visible chatbots. Instead, they are the “picks and shovels” businesses supplying the machinery of the AI economy.

Every new AI model requires an extraordinary industrial ecosystem. Data centers need servers, advanced semiconductors, networking equipment, cooling systems, electricity, construction materials and specialized power infrastructure.

The companies producing these less glamorous components can become indispensable to the technology boom without ever becoming household names. This is one reason AI has created unexpected billionaires.

The logic resembles previous infrastructure-driven economic expansions. During a gold rush, the people selling mining equipment could generate more dependable fortunes than individual prospectors. AI is creating a similar dynamic.

The winners may include semiconductor manufacturers, electrical-equipment suppliers, data-center developers and companies providing the systems needed to keep increasingly energy-intensive computing facilities operational.

For investors, this creates a different way of thinking about the AI opportunity. Instead of asking which chatbot will dominate, they can examine the infrastructure bottlenecks that every major AI company must confront.

Computing capacity, electricity and data-center availability are becoming strategic resources. Meta illustrates the scale of the challenge. Mark Zuckerberg’s ambitions for artificial intelligence require far more than hiring researchers and developing models.

They require land, power, financing, construction, regulatory coordination and enormous computing capacity. The reported recruitment of a former Goldman Sachs executive reflects how the AI race is increasingly becoming an exercise in capital allocation and infrastructure management as much as software engineering.

That transformation matters because the economics of AI are changing. The industry is moving from an era in which technological advantage could largely be measured through algorithms toward one in which physical resources can determine how quickly those algorithms can be deployed.

But there is another, more human dimension to the AI boom: what happens to people who suddenly become extraordinarily wealthy because they positioned themselves correctly?

Entrepreneurs and executives who benefit from the AI explosion can face an unusual psychological problem. Sudden wealth can fundamentally alter relationships, expectations and personal identity.

Someone who spends years building a company with limited financial security may suddenly find themselves managing millions or billions of dollars. The challenge is no longer simply creating wealth, but understanding what to do with it.

That has created opportunities for another group of professionals: coaches, therapists, financial advisers and specialists working with wealthy entrepreneurs. Their role extends beyond traditional wealth management.

They can help individuals navigate family pressures, lifestyle changes, isolation and the psychological consequences of becoming rich much faster than expected. The AI economy, therefore, is producing an unusual chain reaction.

Engineers build models. Infrastructure companies provide the physical foundation. Investors finance expansion. Entrepreneurs accumulate wealth. And a new professional ecosystem emerges around the people who suddenly find themselves at the center of it.

The public debate may remain focused on whether AI is beneficial or dangerous. Markets, however, are already asking a different question: who gets paid to build the world AI requires? That question may reveal some of the most consequential opportunities of the AI era.